Guernsey's States of Deliberation approve the tax reform package including a GST, with commencement conditional
This change is proposed and is not law. The rules below describe what would change if it is adopted.
- Jurisdiction
- Guernsey
- Tax
- GST
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 2 October 2026
- Authority
- States of Guernsey (States of Deliberation)
- Systems
- ERP, Invoicing, Tax engine, POS, E-commerce
- Verified
- Fetched from official source · high confidence
Guernsey businesses and residents, including small independent food producers and eligible users of wheelchair- and stretcher-adapted vehicles.
Plan for a Guernsey GST registration and invoicing project; monitor P&R's draft GST legislation and the commencement date it sets.
ERPInvoicingTax enginePOSE-commerce
On 2 October 2026 the States of Deliberation carried proposition P.2026/49 Prop 1 (Billet d'État XII, 'Tax Reform 2026', as amended by Amendments 16, 52, 55 and 58) by 22 votes to 17 with 1 'ne vote pas'. It directs the Policy & Resources Committee to implement the tax reform package set out in sections 9 and 10 of the policy letter dated 8 June 2026 at the rates and thresholds in Appendix 7, which includes a Goods and Services Tax, save that food produced or grown by small independent suppliers is to be taxed at 0% and not 3%. The resolution bars GST from being brought into operation until the associated income tax and social security mitigations, the GST-related benefit increases and the Essential Costs Relief Payment arrangements are in force, and requires GST commencement to be deferred if those conditions cannot be met. Prop 1.1, carried 36 to 4, adds zero-rating of GST on the supply or importation of wheelchair- and stretcher-adapted motor vehicles to eligible persons. This is a States resolution directing legislation to be prepared; no GST law has yet been made and no commencement date is fixed in the resolution text.
What changed in detail
On 2 October 2026 the States of Deliberation carried proposition P.2026/49 Prop 1 (Billet d’État XII, “Tax Reform 2026”, as amended by Amendments 16, 52, 55 and 58) by 22 votes to 17 with 1 “ne vote pas”.
It directs the Policy & Resources Committee to implement the tax reform package set out in sections 9 and 10 of the policy letter dated 8 June 2026, at the rates and thresholds in Appendix 7. The package includes a Goods and Services Tax, save that food produced or grown by small independent suppliers is to be taxed at 0% and not 3%.
The resolution bars GST from being brought into operation until the associated income tax and social security mitigations, the GST-related benefit increases and the Essential Costs Relief Payment arrangements are in force. It requires GST commencement to be deferred if those conditions cannot be met.
Prop 1.1, carried 36 to 4, adds zero-rating of GST on the supply or importation of wheelchair- and stretcher-adapted motor vehicles to eligible persons.
This is a States resolution directing legislation to be prepared. No GST law has yet been made and no commencement date is fixed in the resolution text.
What it means
The States have decided the policy but not enacted a tax. There is no GST law, rate in force or start date, so businesses cannot yet register or charge it.
The resolution makes commencement conditional on the supporting measures being in place, and requires deferral if they are not. That is a stronger statement than a timetable, so any date quoted in the press should be treated as unconfirmed until legislation sets it.
Proof
save that, in relation to GST, food produced or grown by small independent suppliers is to be taxed at a rate of 0% and not at 3%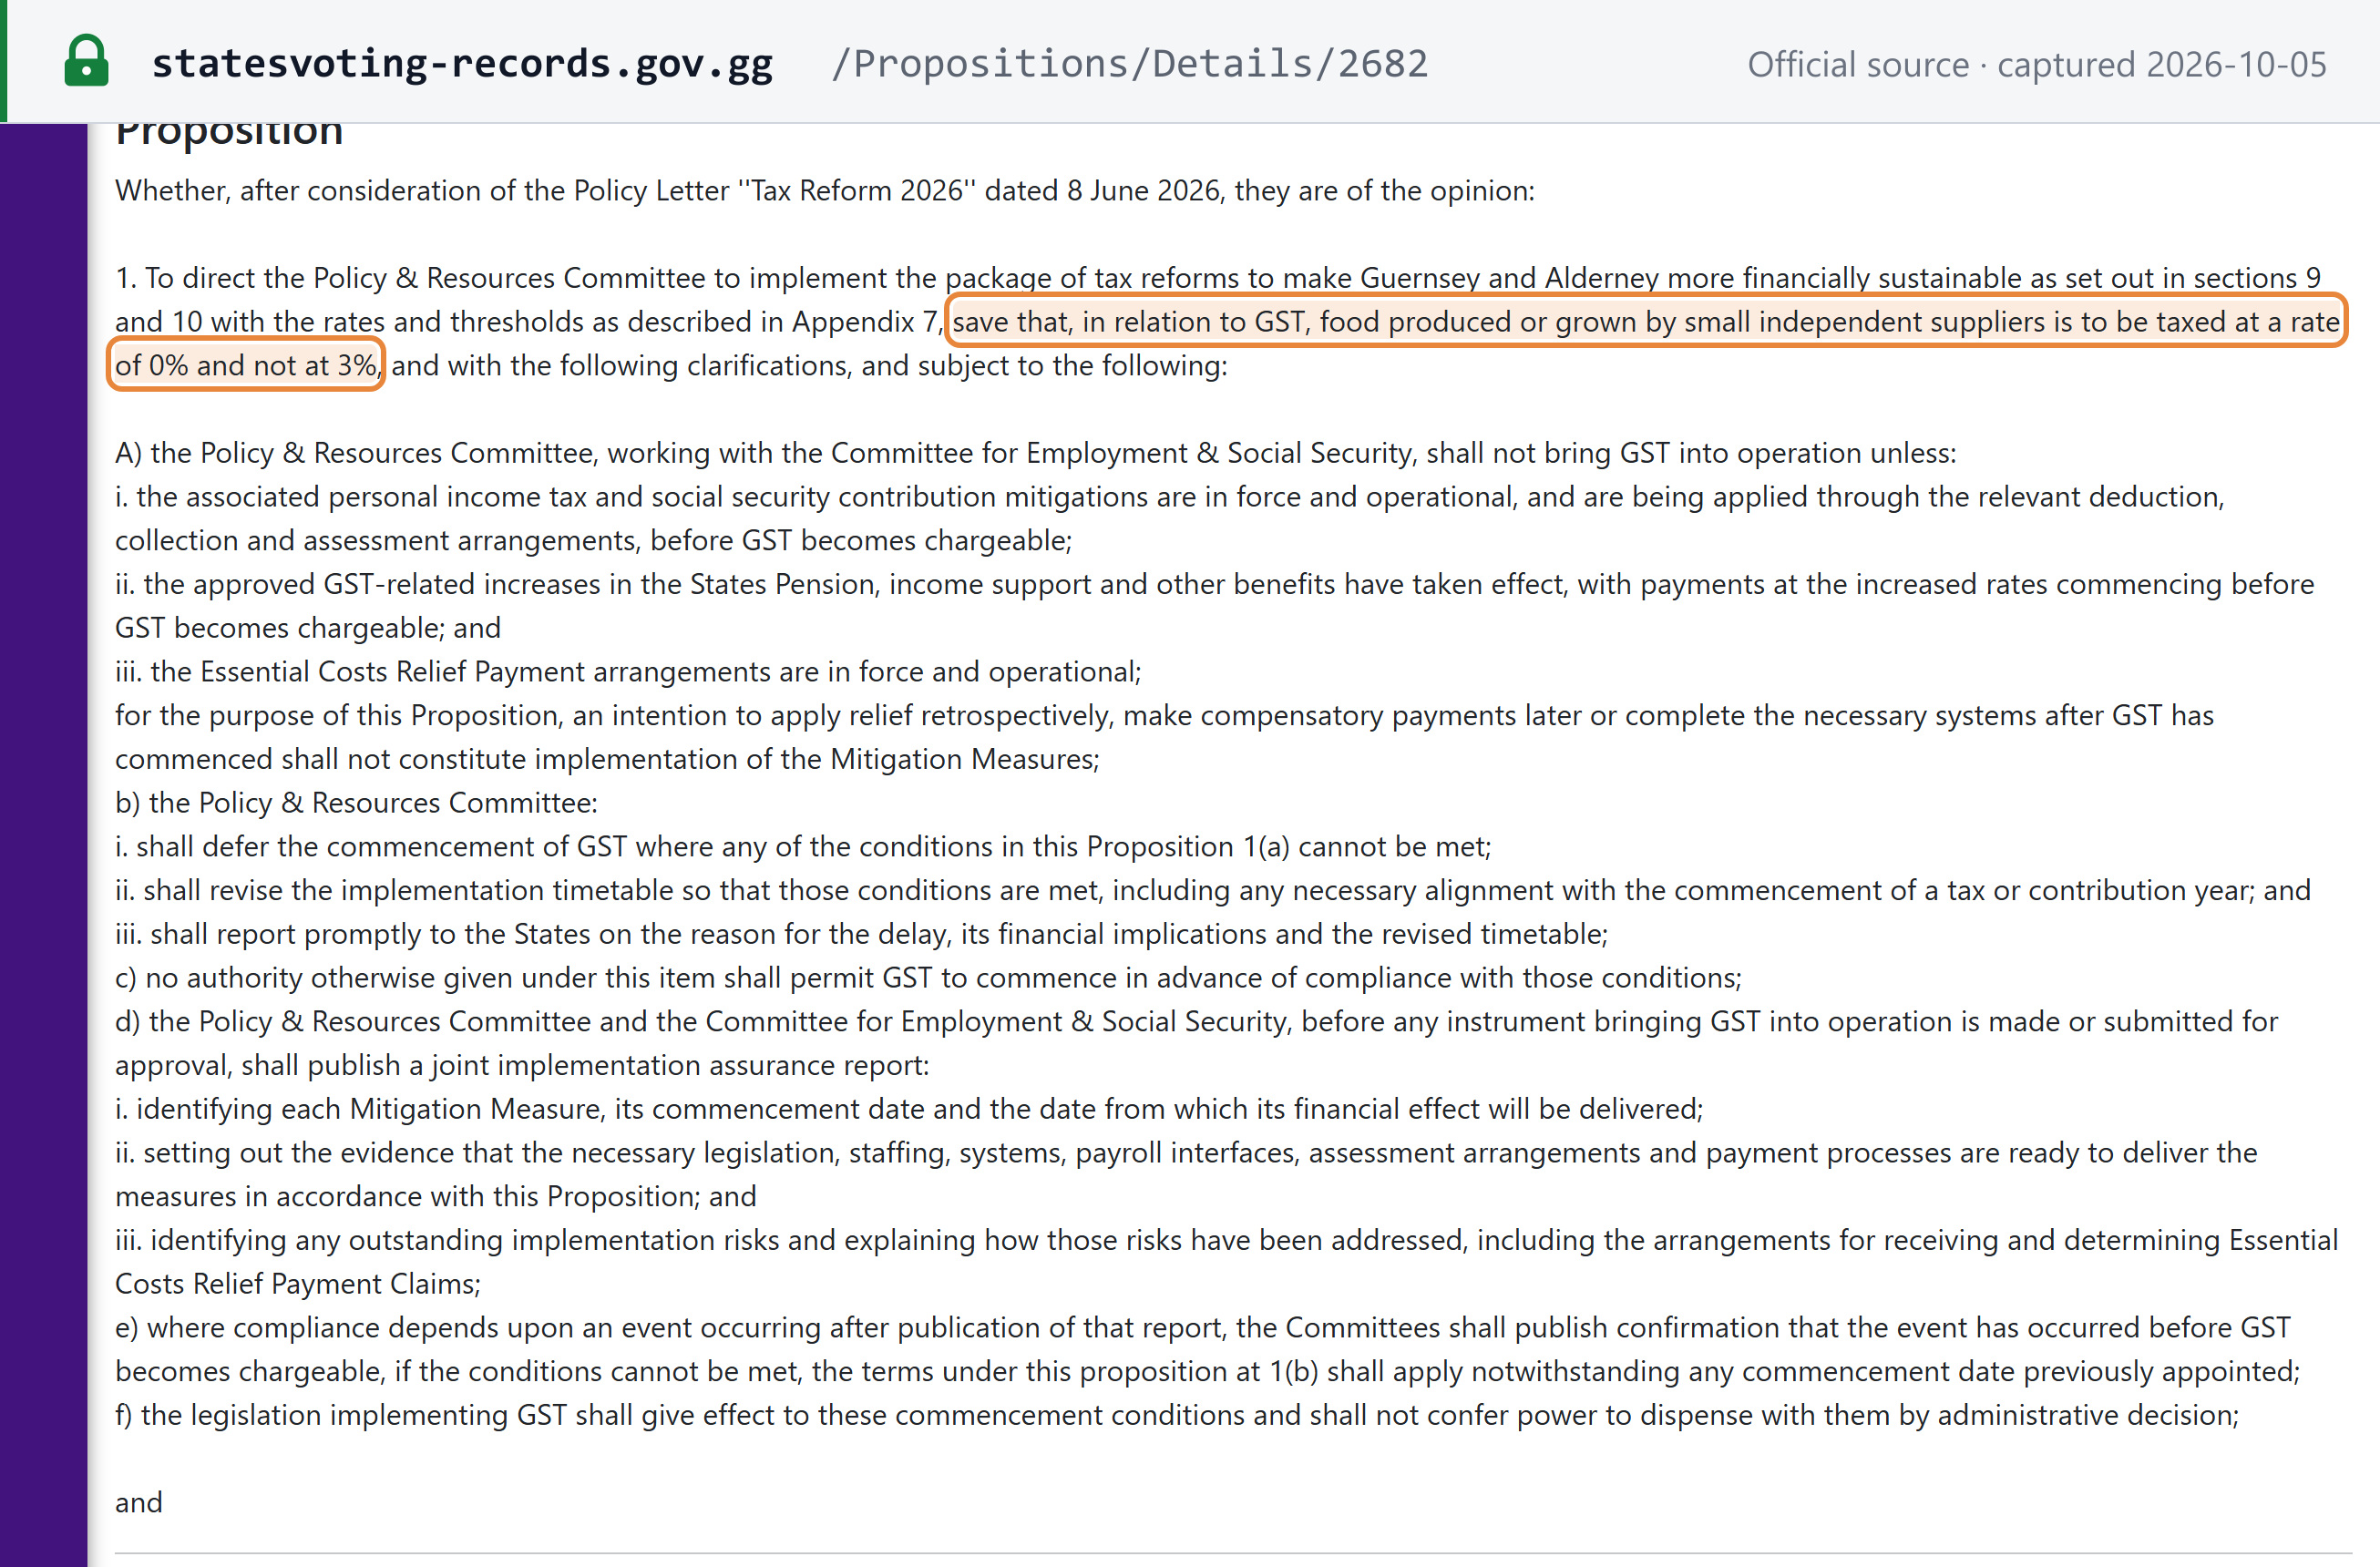 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Guernsey defers its 2026 Tax Reform Package to the 30 September sitting effective 1 January 2028