Hungary's 5% firewood VAT rate does not cover loose sawdust and wood waste
This page records one dated change. For the rules in Hungary as they stand today, see the Hungary guide →
- Jurisdiction
- Hungary
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 1 September 2026
- Effective
- 15 September 2026
- Authority
- Magyar Közlöny (Official Gazette of Hungary)
- Systems
- Tax engine, POS, ERP
- Verified
- Fetched from official source · high confidence
Sellers of wood heating fuel into Hungary. Row 62 of Annex 3 (5% rate) covers only sawdust and wood waste agglomerated into pellets, briquettes or similar form (CN 4401 31, 4401 39); loose, uncompressed sawdust and wood waste (CN 4401 41, 4401 49) is not listed and stays at 27%. Row 61 — firewood in logs, stumps, brushwood or bundles (CN 4401 11, 4401 12) — is unaffected by this correction.
Map only vtsz 4401 11/12 and 4401 31/39 to the 5% rate; keep loose sawdust and wood waste (4401 41/49) at 27%.
Tax enginePOSERP
Act XLVIII of 2026 (Magyar Közlöny 2026/122) inserts two rows into Annex 3 of the Hungarian VAT Act, at the 5% rate from 15 September 2026: row 61, firewood in logs, stumps, brushwood, bundles or similar form (vtsz 4401 11, 4401 12); and row 62, heating sawdust and wood waste and scrap compressed into pellets, briquettes or similar form (vtsz 4401 31, 4401 39). Loose, uncompressed sawdust and wood waste (vtsz 4401 41, 4401 49) is not listed and stays at 27%. This corrects hu-firewood-vat-5pc-act-xlviii-2026 (2026-W37), which listed sawdust at 5% without the compression condition.
What changed in detail
This corrects an earlier record of Act XLVIII of 2026, which listed sawdust and wood waste at the 5% VAT rate without the compression condition. Annex 3 of the VAT Act gets two new rows at the 5% rate, and they are narrower than that record stated:
- Row 61 (unaffected by this correction) — firewood in logs, stumps, brushwood, bundles or similar form (CN 4401 11, 4401 12).
- Row 62 (corrected) — sawdust and wood waste and scrap for heating compressed into pellets, briquettes or similar form (CN 4401 31, 4401 39) — not sawdust and wood waste as such.
Loose, uncompressed sawdust and wood waste (CN 4401 41, 4401 49) does not appear in Annex 3 at all and stays at the 27% standard rate. Both rows took effect 15 September 2026.
What it means
The line the earlier record missed is packaging state, not product category: pellets and briquettes qualify for 5%, loose sawdust from the same sawmill does not. A single reduced-rate code covering “sawdust and wood waste” following the earlier reading over-relieves the loose material. Split the catalogue by CN subheading — 4401 31/39 against 4401 41/49 — rather than by product description.
Proof
Fűtési célú fűrészpor és fahulladék és -maradék, pellet, brikett vagy hasonló alakra tömörítveSawdust and wood waste and scrap for heating purposes, agglomerated into pellets, briquettes or similar form
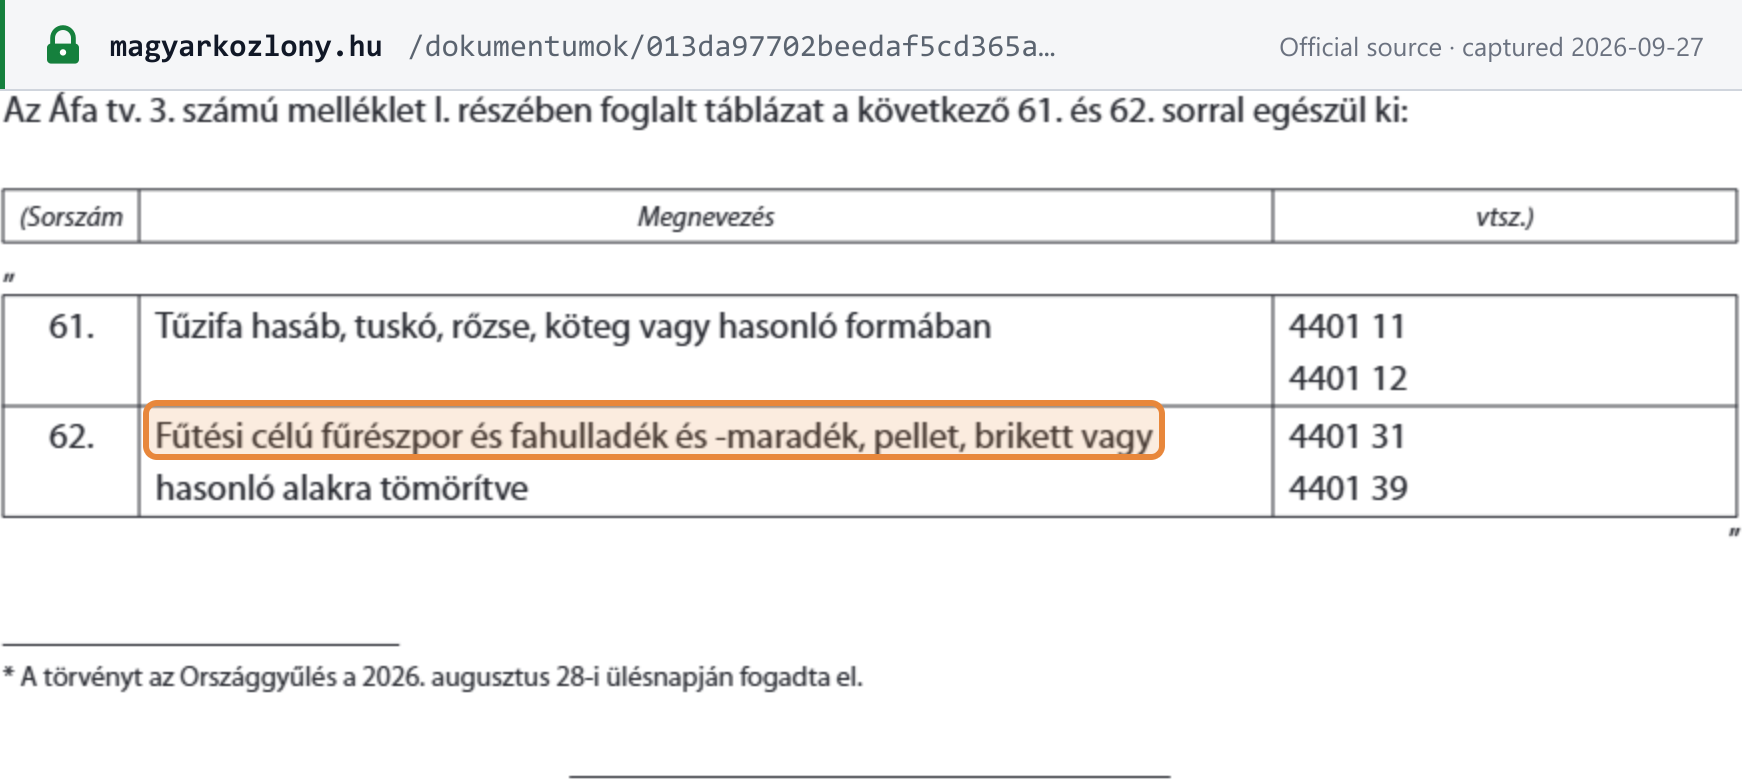 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Hungary cuts VAT on firewood from 27% to 5% from 15 September 2026 effective 15 September 2026