Hungary VAT guidelines
Overview
Hungary's indirect tax is the általános forgalmi adó (áfa) — value added tax — governed by 2007. évi CXXVII. törvény az általános forgalmi adóról (the VAT Act, "Áfa tv."). It is administered by the Nemzeti Adó- és Vámhivatal (NAV), the National Tax and Customs Administration. [1]
VAT amounts and thresholds are denominated in Hungarian forint (HUF) — Hungary is an EU member state but has not adopted the euro. The standard tax period (adómegállapítási időszak) runs on the calendar month, calendar quarter or calendar year, depending on which filing frequency a taxpayer falls into (see Filing and payment) — not a single uniform "tax year" as such. [2]
Hungarian áfa is a single national tax — there is no state, provincial or municipal layer added on top, unlike US sales tax or Canada's GST/PST split.
Registration
Who should register. Any person or entity independently carrying out an economic activity, wherever conducted or whatever its purpose or result, is an adóalany (taxable person) under §5 of the Áfa tv. and must register with NAV before commencing taxable activity in Hungary. Hungarian-incorporated entities receive their adószám during the Court of Registry incorporation process; sole traders and other taxpayers register directly with NAV. [1] For the format of the adószám itself — including the VAT-status digit that determines whether it belongs on an invoice — see our Hungary tax ID guide.
Threshold. There is no general VAT registration threshold in the sense of "register once turnover exceeds X" — registration as a taxable person is triggered by carrying out economic activity at all. What Hungary has instead is the alanyi adómentesség (small-business exemption), an optional election available to a taxpayer whose Hungarian-source turnover did not exceed a set ceiling in the current or preceding calendar year. That ceiling is HUF 20,000,000 for 2026 (up from HUF 18,000,000 in 2025), rising to HUF 22,000,000 in 2027 and HUF 24,000,000 in 2028. [3] [1] A taxpayer under this ceiling can elect to charge no output VAT and deduct no input VAT; above it, or without the election, standard VAT applies from the first forint of turnover.
Non-resident threshold. There is no threshold at all for a non-established business — a company with no Hungarian economic establishment that makes even a single taxable supply in Hungary must register from that first transaction. The alanyi adómentesség election in the paragraph above is open to a taxpayer whose seat — failing that, domicile — is in Hungary (§187) or in another EU member state: since the EU SME scheme was transposed, §195/G(1) lets an EU-established taxable person apply the Hungarian exemption to its Hungarian supplies, subject to the same HUF 20,000,000 domestic ceiling plus a cumulative EU turnover cap of EUR 100,000 (§195/G(3)), with the election declared in its home member state (§195/G(4)). Only a business established outside the EU is shut out. [1] Non-EU companies must additionally appoint a Hungarian fiscal representative before registering — see the Hungary tax ID guide for the current capital requirements and process.
How to register. Domestic incorporation and the adószám happen together via the Court of Registry filing; changes and most other filings, including registration by sole traders and foreign taxpayers, go through NAV's ONYA (Online Nyomtatványkitöltő Alkalmazás) e-services portal at onya.nav.gov.hu, reached after Ügyfélkapu+ (Client Gateway) authentication. NAV publishes no service standard for how long registration takes once the documents are filed. [4]
Voluntary registration. A taxpayer whose turnover is under the alanyi adómentesség ceiling can instead choose to register for standard VAT rather than take the exemption — worthwhile where the business has significant input VAT to recover (e.g. a startup with heavy upfront costs, or a business selling mainly to VAT-registered customers who are indifferent to the VAT charged).
Deregistration. The alanyi adómentesség exemption is chosen through the end of the calendar year (§190) and ceases where: the taxpayer elects not to continue it into the following year; the taxpayer's actual turnover in the given year breaches the threshold; or the taxpayer ceases without a legal successor meeting the conditions. [1] Full deregistration of an adószám on cessation of business requires a closing VAT return and NAV cancellation of the number; a group's csoportazonosító szám (group identifier) similarly triggers an out-of-cycle closing return within 30 days of cancellation. [5]
Group registration. Available. Under §8 of the Áfa tv., taxable persons established in Hungary that are kapcsolt vállalkozások (related/affiliated undertakings) may apply jointly, in writing, to NAV for csoportos adóalanyiság (group VAT status). Once approved: transactions between group members cease to be economic activity for VAT purposes (no VAT is charged member-to-member), the members' individual taxable-person status otherwise ends, and the group is treated as a single taxable person for transactions with third parties — for whose VAT debts all members are jointly and severally liable. A taxpayer already in one VAT group cannot apply to join or form another. Group formation and any member joining or leaving triggers an out-of-cycle return within 30 days. [1] [5]
Rates
Hungary's standard VAT rate is 27%. [1]
| Rate | Basis | Applies to |
|---|---|---|
| 27% | Áfa tv. §82(1) | The default rate — everything not listed in a reduced-rate annex, e.g. electronics, clothing, fuel |
| 18% | Áfa tv. §82(3), Annex 3/A | Certain staple foodstuffs (e.g. milk and dairy products, bakery/cereal products) and on-premises restaurant/catering services |
| 5% | Áfa tv. §82(2), Annex 3 | Authorised human medicines that are not prescription-only, books and periodicals, firewood and wood heating fuels (from 15 September 2026), district heating, internet access services, commercial accommodation services, and — subject to conditions — new residential property (until 31 December 2026, with a transitional rule to 31 December 2030 — see below); also imports of specified artworks under §82(5) |
| 0% | Áfa tv. §82(4), Annex 3/B | A narrow list of specified goods — from 1 September 2026 including prescription-only medicines and human magistral preparations [14] |
[1] Exports of goods and related intra-EU supplies are separately zero-rated with input-tax recovery under the exemption-with-credit rules in §§89 and 98 (Chapter VI), which is a different mechanism from the §82(4)/Annex 3/B "0% rate" list.
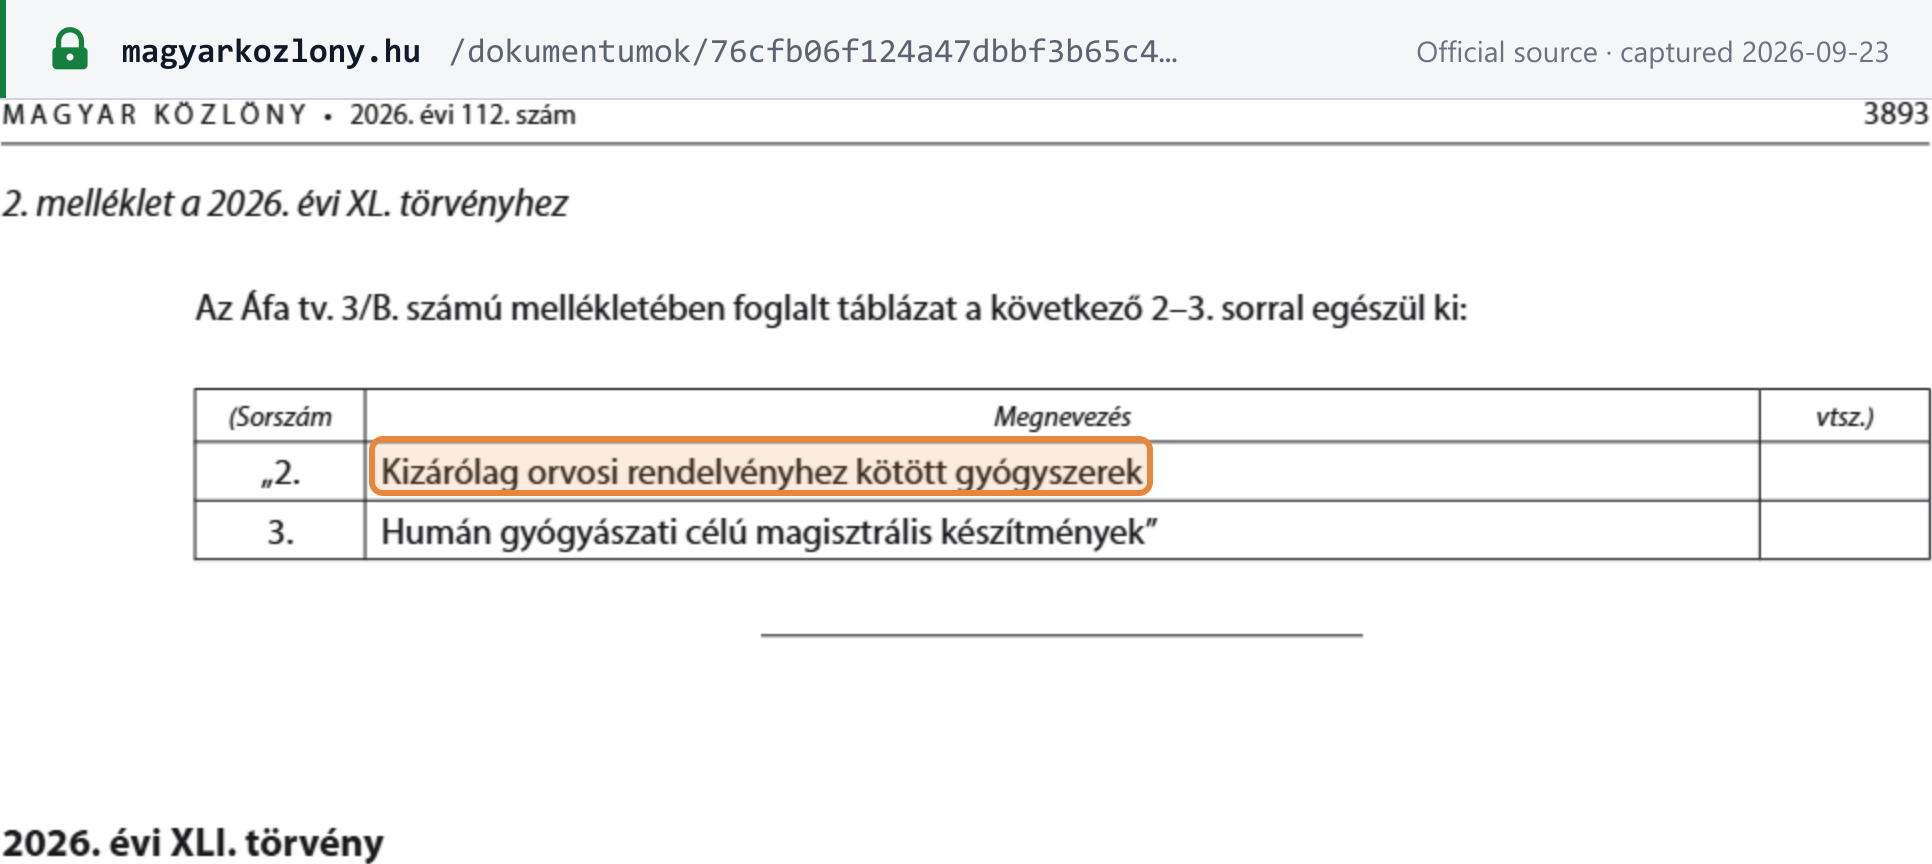
Prescription medicines at 0% from 1 September 2026. 2026. évi XL. törvény (Act XL of 2026, adopted by the Országgyűlés on 11 August 2026 and published in Magyar Közlöny 2026/112 on 13 August 2026) added two rows to Annex 3/B — "kizárólag orvosi rendelvényhez kötött gyógyszerek" (medicines available only on medical prescription) and "humán gyógyászati célú magisztrális készítmények" (magistral preparations for human medical use) — so both are taxed at 0% from 1 September 2026. The Annex 3 5% entry for authorised human medicines now expressly excludes the prescription-only products that moved to Annex 3/B, so authorised over-the-counter medicines stay at 5%. [14]
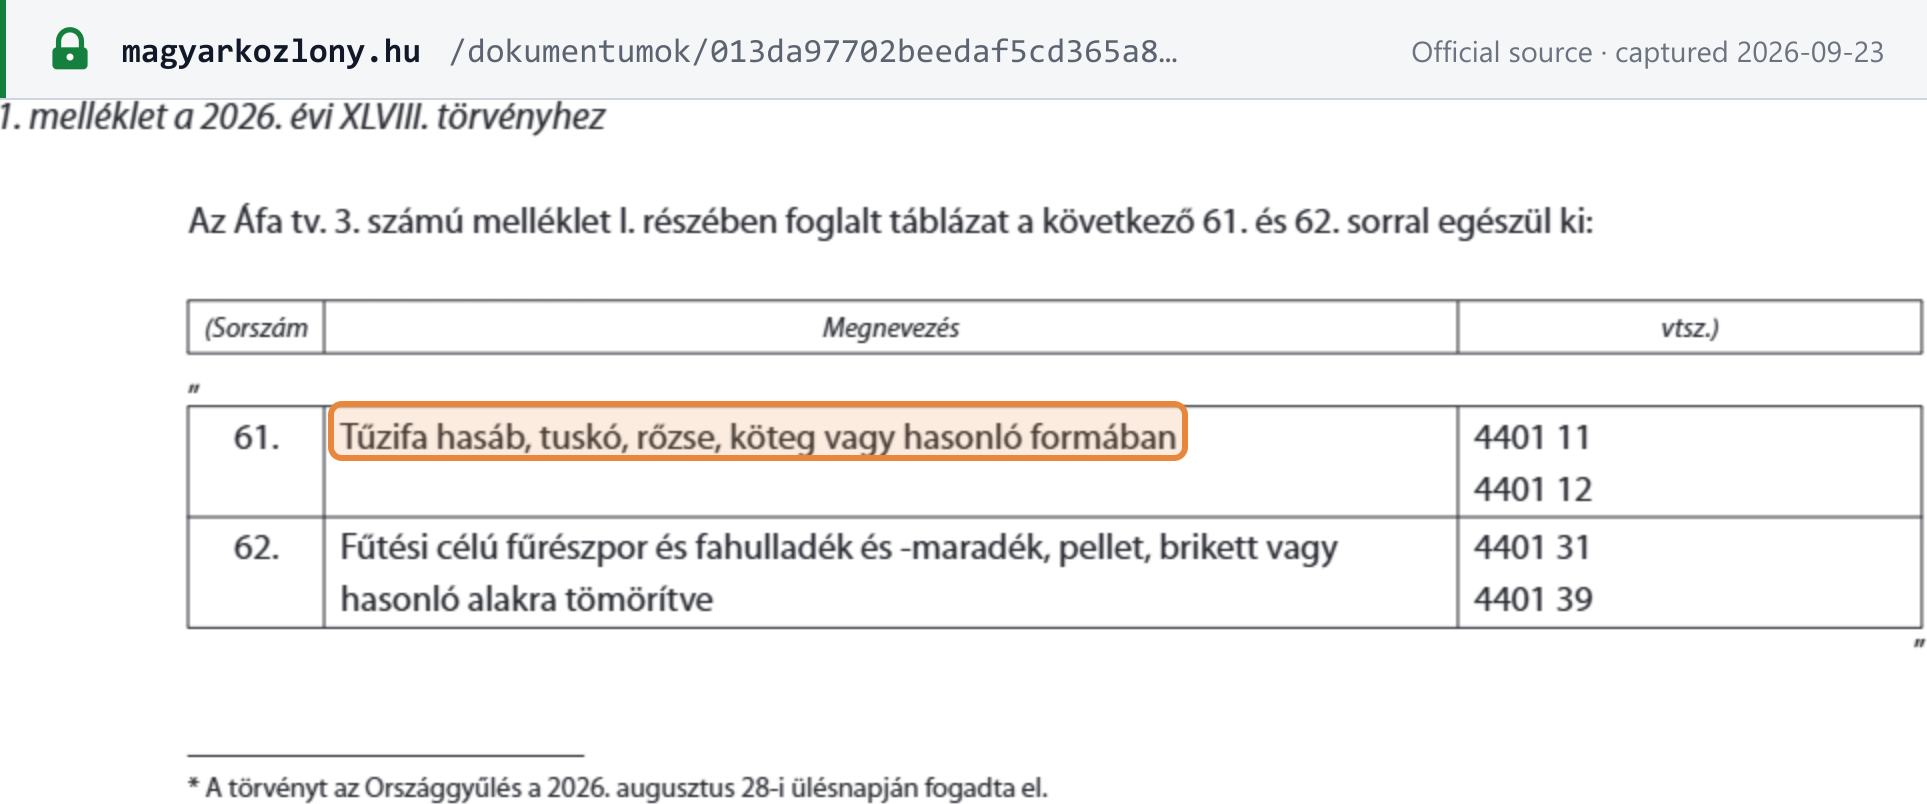
Firewood at 5% from 15 September 2026 — enacted. 2026. évi XLVIII. törvény (Act XLVIII of 2026, adopted by the Országgyűlés on 28 August 2026 and published in Magyar Közlöny 2026/122 on 1 September 2026) added two rows to Annex 3, moving firewood (tűzifa) from the 27% standard rate to 5% from 15 September 2026: firewood in logs, stumps, brushwood, bundles or similar forms (vtsz 4401 11, 4401 12), and heating sawdust, wood waste and scrap compressed into pellets, briquettes or similar forms (vtsz 4401 31, 4401 39) — loose sawdust and scrap are not covered. [15]
New homes at 5% — ends 31 December 2026. Under Act LV of 2024, the 5% rate for sales of new homes applies until 31 December 2026 and is withdrawn from 1 January 2027. It covers flats of up to 150 m² in multi-dwelling buildings outside brownfield action areas, and single-dwelling houses of up to 300 m². A transitional rule (§371 of the Áfa tv., in force from 1 January 2027) keeps 5% for advances received and supplies made from 1 January 2027 to 31 December 2030 if any one of three conditions is met: the building permit became final by 31 December 2026; a simple notification was filed by 30 September 2024; or a simple notification under the Hungarian architecture act was acknowledged by 31 December 2026. Otherwise 27% applies. New flats of up to 150 m² in designated brownfield (rozsdaövezeti) action areas stay at 5% after 1 January 2027. Sales and advances that straddle 1 January 2027 need the date and the qualifying condition checked. (Source: NAV)
Cross-border rules
Imports and exports. Import of goods from outside the EU is subject to Hungarian import VAT collected alongside customs duty, based on customs value; export of goods out of the EU is exempt with the right to recover input VAT (§98). A Hungarian VAT-registered business receiving a service from a supplier established outside Hungary self-assesses VAT under reverse charge (§140(a)) — the customer both charges itself the output tax and, to the extent the purchase is for taxable business use, deducts it as input tax in the same return. [1]
Digital products and services. Electronically supplied services, telecommunications and broadcasting services follow the EU-wide rule: B2C supplies are taxed where the private consumer is located, and a non-established seller can report EU-wide B2C digital sales through a single EU One Stop Shop (OSS) registration rather than registering in every member state where it has customers, once its pan-EU cross-border B2C sales exceed the €10,000 EU-wide threshold (or immediately if it opts in below that).
Foreign sellers — B2B and B2C differ.
- B2B: for services, the general place-of-supply rule (§37(1)) puts the transaction where the Hungarian business customer is established, and that customer self-assesses VAT under reverse charge (§140) — a foreign B2B service supplier typically does not need to register in Hungary for that supply alone. For goods delivered to a Hungarian business, ordinary intra-EU acquisition or import VAT rules apply instead.
- B2C: a foreign seller of goods or digital services to Hungarian consumers must charge Hungarian VAT once it is liable to do so — via OSS/IOSS registration for an EU or non-EU e-commerce seller respectively, or via full Hungarian VAT registration (with a fiscal representative if established outside the EU) where OSS/IOSS does not apply. There is no threshold shielding a non-established seller once the relevant EU distance-selling threshold is crossed. [1]
Marketplace / platform deemed-supplier liability. Under §12/C, where an electronic interface (marketplace/platform) facilitates certain B2C supplies — notably distance sales of low-value imported goods and, for a non-EU underlying seller, EU-to-EU B2C goods sales — the platform is deemed to have received and supplied the goods itself and becomes the party liable for the VAT, per the EU-wide e-commerce platform rules Hungary implements. [1]
Place of supply.
- Goods (§§25–27): if the goods are not dispatched or transported, the place of supply is simply where the goods physically are at the time of supply. If they are dispatched or transported (by or for the seller or buyer), the place of supply is where the goods are when dispatch or transport begins — i.e. goods are generally taxed at their point of departure, not arrival (subject to the separate distance-selling/OSS destination rules for B2C).
- Services (§37): B2B — where the business customer is established (or, absent that, domiciled/habitually resident); B2C — where the supplier is established (or domiciled/habitually resident). Numerous exceptions override this general rule, most importantly services directly connected with immovable property (§39), which are always taxed where the property is located, regardless of either party's establishment. [1]
Invoice requirements
A számla is any document settling a supply of goods or services, whether issued as a structured electronic invoice or as a paper/PDF invoice — invoice validity under the Áfa tv. is a separate question from the real-time reporting obligation covered in E-invoicing status below.
Mandatory content
Every számla must contain the particulars listed in §169 of the Áfa tv.: [1]
| Required field | Notes |
|---|---|
| Date of issue | §169(a) |
| Sequence number | §169(b) — must identify the invoice beyond doubt |
| Supplier's adószám | §169(c) — the tax number under which the supply was made |
| Buyer's adószám | §169(d) — required where the buyer is the party liable for the tax (reverse charge), where an intra-EU exempt supply is made to it, or — for a domestically registered business buyer — the first eight digits of its adószám (or group identifier) |
| Both parties' name and address | §169(e) |
| Description and quantity of goods, or nature and extent of services | §169(f) |
| Date of supply / date payment received, if different from the issue date | §169(g) |
| "pénzforgalmi elszámolás" | §169(h) — where the cash-accounting scheme is used |
| Taxable amount, unit price net of VAT, and any discount not already reflected in the unit price | §169(i) |
| The VAT rate applied | §169(j) |
| The VAT amount charged, unless its display is excluded by law | §169(k) |
| "önszámlázás" | §169(l) — where the invoice is self-billed by the customer |
| Reference to the exemption (statute or the VAT Directive) | §169(m) — for an exempt supply |
| "fordított adózás" | §169(n) — where the customer is liable for the tax (reverse charge) |
| New-means-of-transport data | §169(o) — for the specific §89 sale of a new vehicle |
| Margin-scheme wording | §169(p)–(q) — "különbözet szerinti szabályozás" for travel agents, used goods, art, or collectors' items/antiques, as applicable |
What a compliant invoice looks like
NAV does not publish a single annotated specimen invoice the way some other tax authorities do, so the sheet below is one we built — each §169 field placed where it sits on an issued számla, with the clause printed next to it. Every name, number and amount is fictional.
Számla — VAT invoice
| Description and quantity§169(f) | Unit price (net) | Net amount |
|---|---|---|
| Grafikai tervezési szolgáltatás — 10 óra | 25 000 Ft / óra | 250 000 Ft |
- Taxable amount§169(i)
- 250 000 Ft
- VAT rate§169(j)
- 27%
- VAT amount§169(k)
- 67 500 Ft
- Gross total
- 317 500 Ft
- The conditional wordings sit on the face of the invoice, not in a schedule: "fordított adózás" for a reverse-charge supply §169(n), "önszámlázás" where the buyer self-bills §169(l), "pénzforgalmi elszámolás" under cash accounting §169(h), and the statute or VAT Directive reference for an exempt supply §169(m).
- Names, addresses and both adószám values above are invented. A real domestic B2B invoice carries the buyer's actual number, of which the first eight digits are the operative part for §169(d).
A nyugta receipt (see Document types below) carries a shorter, separately defined field set under §173, not the §169 list above.
Issuance deadline and numbering
A taxable person must ensure a számla is issued by the time of supply at the latest, or — for an advance payment — by the point the tax on it becomes due, subject to a "reasonable time" allowance (§163(1)). That reasonable time is, in the most common case (a domestic supply where reverse charge under an EU-equivalent rule does not apply and the consideration is not settled by the point of supply), 8 days; for a cross-border reverse-charge supply of services or an intra-EU supply of goods, the invoice must be issued by the 15th of the month following the month of supply (§163(2)). Numbering must be sequential and assigned once only by the issuer, but §169(b) prescribes no particular numbering format or single unbroken series. Consolidated "gyűjtőszámla" invoicing covering multiple supplies to the same customer within a period is permitted by agreement (§164). [1]
Credit and debit notes
The Áfa tv. does not use separate "credit note" / "debit note" instruments; corrections are made by a módosító/helyesbítő számla referencing the original invoice. Where the taxable amount changes after the fact (§153/B) — a discount, a partial cancellation, a bad-debt write-off meeting the conditions of §77 — the supplier adjusts the return for the period in which the correction is recognised. A self-billed correction (§169(l), "önszámlázás") must likewise reference the original document. [1]
Currency and language
The Áfa tv. does not require invoices to be denominated in forint, but the VAT itself must be expressed and accounted for in HUF; where the underlying transaction is in a foreign currency, the tax amount is converted at the exchange rate used for the VAT return (§172, cross-referencing §80). On language the statute is explicit, not silent: §178(2) allows an invoice in Hungarian or any living foreign language, and §178(3) lets NAV require the issuer to produce a certified Hungarian translation at its own cost during an audit. A nyugta, by contrast, may be issued only in Hungarian (§178(4)) — a hard constraint for foreign-owned retail.
Document types
- Számla (full invoice) — required for B2B and any supply where the buyer needs to support input-tax deduction; carries the full §169 particulars.
- Nyugta (receipt) — a simplified cash document under §173, permitted in place of a számla under §165 only where: the buyer settles the full VAT-inclusive consideration by the time of supply — payment method is irrelevant, so card and transfer qualify as well as cash — and does not ask for a számla (§165(1)(b)). This simplification is not available for intra-EU supplies, distance sales, any supply to another business or non-taxable legal person, or a supply to a private individual where the gross consideration reaches HUF 900,000 (§165(3)(b)). A nyugta must show: issue date; sequence number; issuer's adószám, name and address; the VAT-inclusive consideration; a description (and, where applicable, quantity) of the goods/services; the VAT rate; and, for an exempt or margin-scheme supply, the relevant reference (§173). [1]
Self-billing
Permitted. Where the parties agree in advance, the buyer (or a third party it commissions) may issue the invoice on the supplier's behalf — the invoice must then carry the word "önszámlázás" per §169(l).
Retention
A person or entity exercising rights or bearing obligations under the Áfa tv. must retain, for control purposes, every document it issued or that is otherwise in its possession — until the tax authority's right to assess the underlying tax lapses (elévülés) (§179). Paper originals may be archived electronically; a document that originated as an electronic invoice may only be kept electronically. There is no separately shortened retention period for a nyugta versus a számla under the VAT Act itself. [1]
Audit trail. §179's storage obligation is expressly tied to keeping "the completeness and accuracy of the tax assessment verifiable" — a general audit-trail requirement — and any change in an electronic invoice's format must still meet the authenticity-of-origin, integrity-of-content and legibility conditions set by §168/A. In practice this is the same EN-aligned triad (unaltered origin, unaltered content, readable throughout the retention period) used elsewhere in the EU VAT Directive; NAV's real-time Online Számla feed (see E-invoicing status) additionally gives the authority its own independent, contemporaneous record of each invoice's content, separate from whatever the taxpayer retains. [1]
E-invoicing status
Status as of 2026-09-30: no general mandatory e-invoicing regime for invoice validity — but comprehensive real-time invoice DATA reporting is mandatory, and is being extended to receipts. These are two different obligations and it is easy to conflate them.
- Invoice validity: a paper or plain-PDF számla remains valid; an electronic invoice needs only the recipient's consent unless law provides otherwise (Áfa tv. §175(3)), and any invoice issued and received electronically, a PDF included, counts as one (§259 point 5). Hungary has not adopted a mandate requiring invoices to be issued as structured documents. [1]
- Energy-sector rule: electricity traders and distributors, and gas traders and system operators, must invoice non-household customers electronically only (Govt. Decree 273/2007 §21/B(1a); Govt. Decree 19/2009 §115/E(1a)); no format is prescribed. Paper was still allowed for bills due between 1 July 2025 and 1 July 2026 under existing contracts where the customer gave no e-invoice address; that tolerance has ended. (273/2007; 19/2009)
- Water-utility rule: from 1 January 2026, water utilities must also invoice non-household users electronically only (Govt. Decree 58/2013 §65(5a)). (58/2013)
- Future structured e-invoicing (ViDA): the Ministry for National Economy and NAV published an official e-invoicing concept, put to consultation from 21 November 2025 to 20 January 2026, that plans mandatory EN 16931 e-invoicing for domestic and intra-EU B2B. As at 2026-09-30 it has no start date and no bill, so it is a plan, not law. (NAV)
- Real-time invoice data reporting (Online Számla / RTIR): mandatory since 2018, and covering essentially all domestic invoices — B2B and B2C, any amount — since 2021. Invoice data is transmitted to NAV via the Online Számla platform, either machine-to-machine from invoicing/ERP software or manually through NAV's web interface. Only XML schema v3.0 has been the only accepted version since 1 April 2021 — submissions on 1.0, 1.1 or 2.0 are rejected. [12] [7] For the schema-migration detail and enforcement escalation from advisory to blocking errors, see the Hungary tax ID guide.
- Receipt data reporting (nyugtaadat-szolgáltatás) — the newest layer: from 1 September 2026, data on both manually issued and computer/cash-register-generated receipts (nyugta) must also be reported to NAV, within three calendar days of issuance, aggregated daily by tax rate — lighter-touch than the transaction-level invoice reporting above. See Recent changes. [8]
- Scope: RTIR/Online Számla applies to B2B and B2C domestic invoices alike.
- B2G: since 18 April 2019, contracting authorities must receive and process e-invoices conforming to EN 16931 (Kbt. §27/A, inserted by Act LXXXIII of 2018). The rule binds the public buyer only; it names no platform or CIUS and does not oblige suppliers to issue e-invoices. (Kbt.)
- Phase timeline by taxpayer size: none currently in force. Unlike jurisdictions rolling out e-invoicing by revenue band, Hungary's RTIR obligation already applies uniformly to all VAT-registered taxpayers regardless of size — there is no size-based threshold left to phase in for invoices. The receipt data-reporting extension above is time-phased (a flat four-month transition to 1 January 2027), not size-phased.
For the full picture (reporting timing, schema, onboarding, penalties and the ViDA concept), see the Hungary e-invoicing guide.
Filing and payment
Filing frequency is set annually, based on the taxpayer's net VAT payable (elszámolandó adó) for the second preceding tax year, per Annex 2, Part I/B of Art. (2017. évi CL. törvény): [2] [5]
| Frequency | Trigger | Return due |
|---|---|---|
| Monthly | Net VAT payable, summed on an annual basis, was positive and reached HUF 1,000,000 in the second preceding year; also the default for newly formed taxpayers (registration year and the following year), for members of a VAT group, and for certain special categories (indirect customs representatives, bonded-warehouse operators) | 20th of the following month |
| Quarterly (default) | Taxpayers who fall into neither the monthly nor the annual category; also taxpayers who would otherwise file annually but hold an EU (community) VAT number | 20th of the month following the quarter |
| Annual | Net VAT payable under HUF 250,000 in the second preceding year, annual net turnover ≤ HUF 50,000,000, and no EU VAT number | 25 February of the following year |
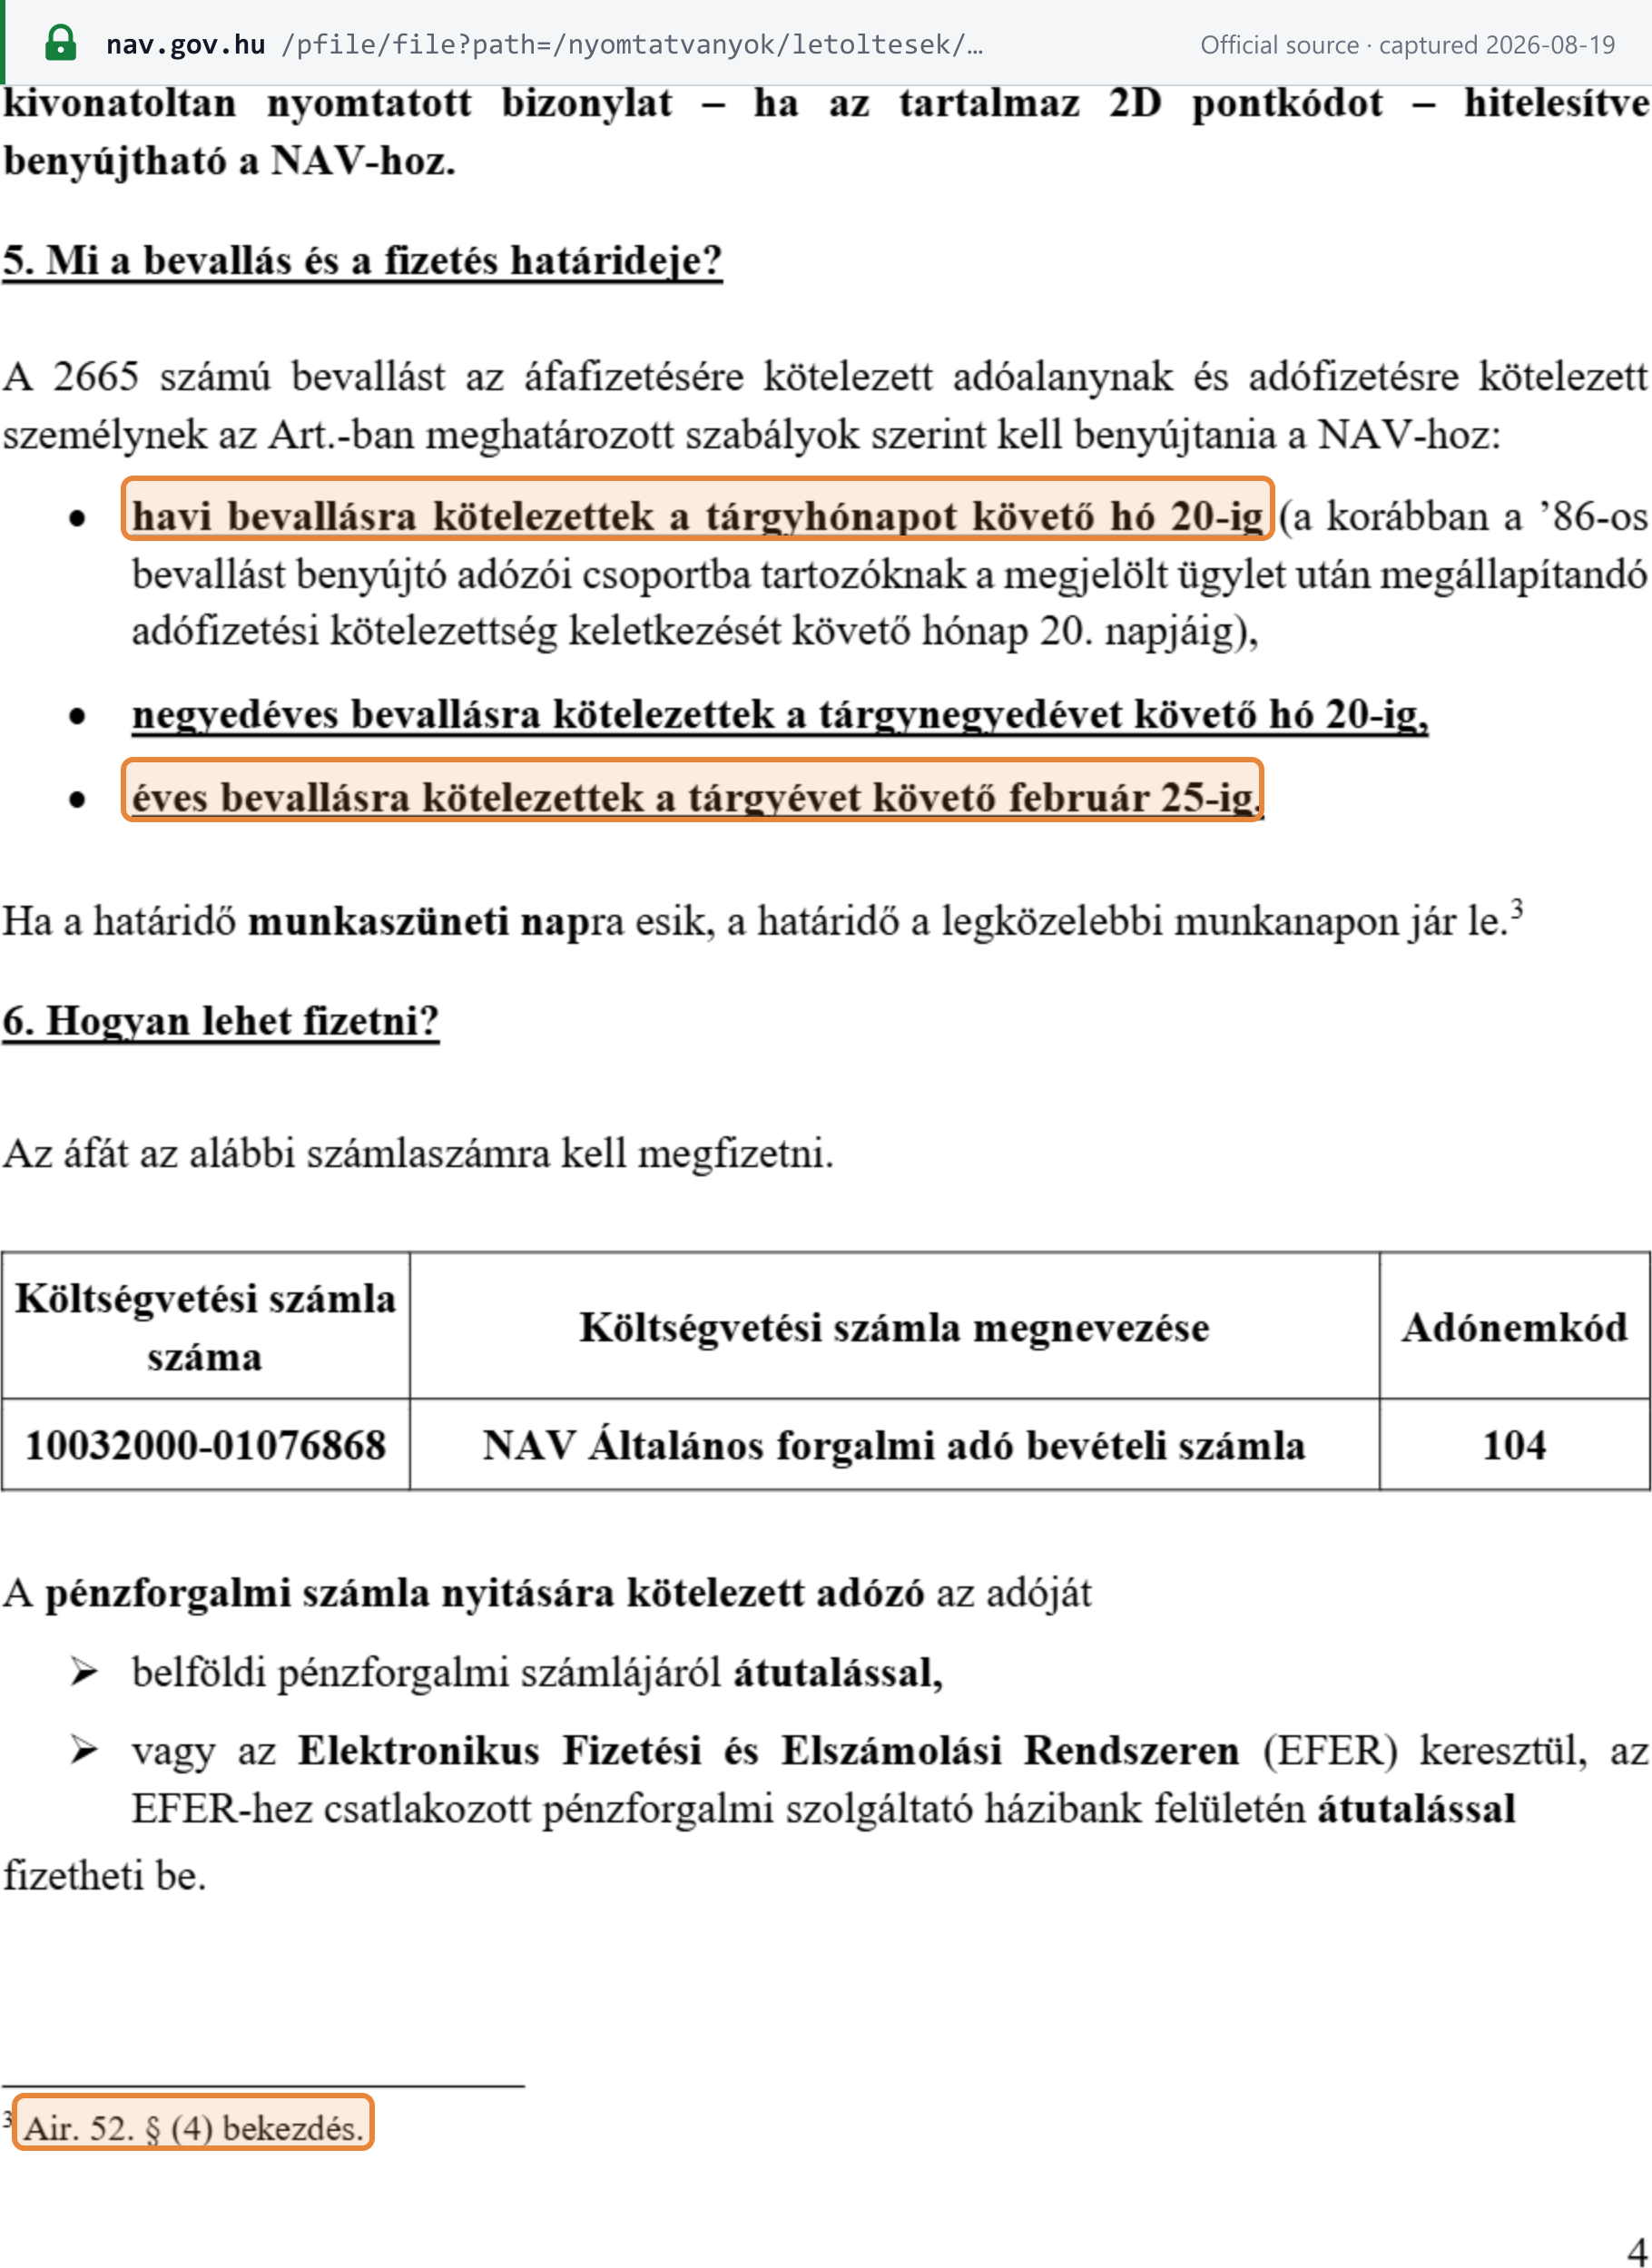 Source snapshot captured 2026-08-19 — original
VAT-exempt taxpayers (alanyi adómentesség), those carrying out only non-deductible activity, and special-status agricultural taxpayers file — where a residual obligation actually arises — monthly.
Payment is due on the same date as the corresponding return. Filing is via the '65 series return form (e.g. "2665" for the 2026 tax year) submitted electronically, or through the eÁfa self-service system, which pre-populates a draft from NAV's own invoice data and lets the taxpayer approve, edit or supplement it. [5]
Additional listings. Businesses with intra-EU (community) trade must additionally file a recapitulative statement — the 'A60 összesítő nyilatkozat — electronically, alongside the VAT return.
ÁNYK form-filler is being retired from 2027. NAV confirms that, from 2027, its general-purpose ÁNYK (Általános Nyomtatványkitöltő Keretprogram) form-filler client is being entirely replaced by newer digital channels — ONYA, eÁFA/eVAT, and machine-to-machine (M2M) submission — for filing tax returns, including VAT returns. [13] Anyone still filing Hungarian returns (VAT or otherwise) through the classic ÁNYK client should move to ONYA, eÁFA/eVAT, or an M2M integration during 2026. NAV has not published a closing date for the ÁNYK channel — its transition hub segments guidance by taxpayer type, not by cut-over date — and NAV has published a dedicated mailbox ([email protected]) for transition questions. This is a filing-channel change only — it does not alter the VAT return forms, frequencies, or due dates set out in the table above.
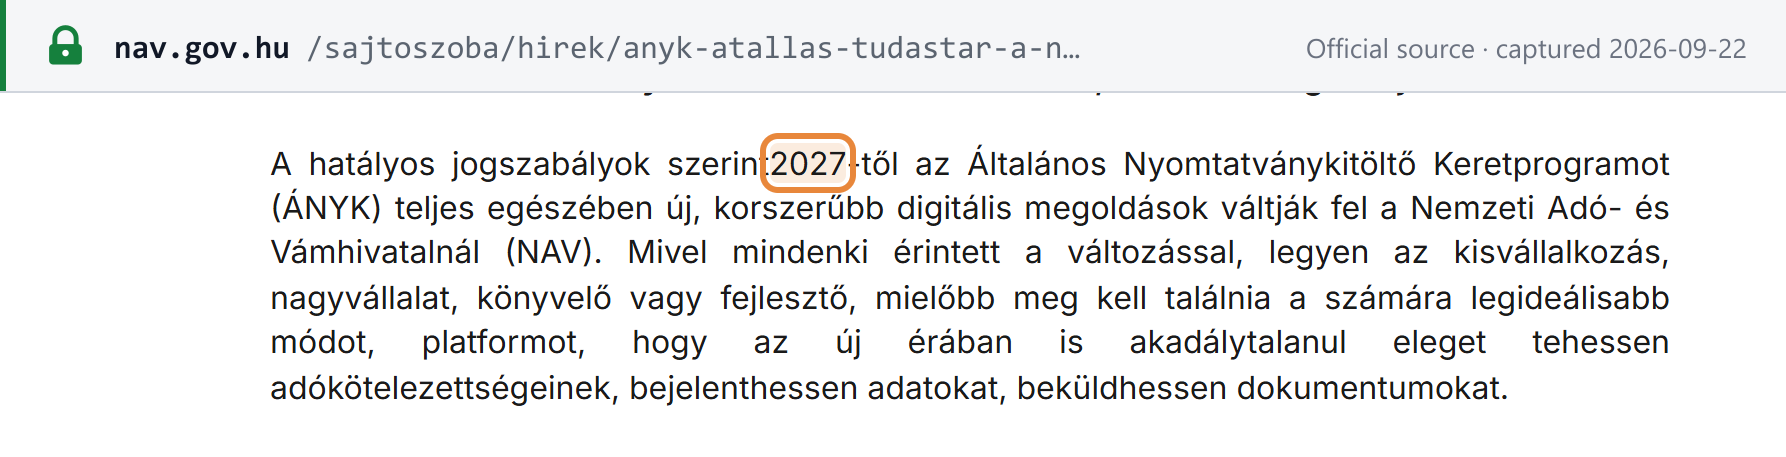 NAV, 15 July 2026 — the sentence states a 2027 replacement and gives no closing date for the ÁNYK channel.
Input-tax recovery and blocked items. Input VAT is generally deductible against output VAT to the extent goods/services are used for taxable business activity. §124 blocks deduction on a specific list regardless of that general right, including: motor fuel and other goods/services needed to run or maintain a passenger car; passenger cars themselves (other than hearses); motorcycles over 125cm³; yachts and other water vehicles used for sport or leisure; residential property and goods/services for building or renovating it; food and beverages; taxi services; parking; road-usage/toll services; catering/restaurant services; and entertainment services. [1]
Refunds. A resident taxpayer with input VAT exceeding output VAT in a period may carry the excess forward, or reclaim it from NAV under the conditions of §186. A non-established EU business reclaims Hungarian input VAT through its home member state's portal under the EU cross-border refund directive (2008/9/EC) mechanism rather than filing a Hungarian VAT return; a non-EU business follows Hungary's domestic 13th-Directive-equivalent refund route. [1]
Exemptions
Hungary distinguishes exemptions by the public-interest nature of the activity (§85 — e.g. universal postal services, patient transport and closely related services, and a broader public-interest list covering healthcare, education, welfare and similar activities) from other exemptions (§86 — notably financial and insurance services, and the sale or leasing of most immovable property other than new buildings/building plots, which a taxpayer may elect to tax under §88). [1]
Exempt is not the same as zero-rated. An exempt supply (§85/§86) carries no output VAT, but the supplier also cannot deduct the input VAT attributable to it — a real cost that sits in the price. A zero-rated / exemption-with-credit supply (exports under §98, most intra-EU supplies under §89) also carries no output VAT, but the supplier can still deduct the related input VAT in full. Conflating the two is the most common source of Hungarian VAT-compliance error for readers new to the system.
Special regimes. The alanyi adómentesség small-business exemption is covered under Registration above. Hungary also operates the standard EU-aligned margin scheme for travel agencies and for used goods, artworks, collectors' items and antiques (Chapter XV–XVI, referenced in the §169(p)–(q) invoice wording), and a cash-accounting scheme (pénzforgalmi elszámolás, flagged on invoices per §169(h)) available to small taxpayers who account for output VAT only once payment is actually received.
Offences and penalties
Hungary keeps unlawful conduct (offences) and monetary sanctions (penalties) in separate statutes — Art. (2017. évi CL. törvény) for administrative penalties, and the Criminal Code (Btk., 2012. évi C. törvény) for criminal offences.
Offences. VAT fraud is prosecuted under the consolidated "költségvetési csalás" (budget fraud) offence at Btk. §396, which covers deceiving the tax authority, making false statements, or claiming ineligible tax benefits in connection with a payment obligation to, or funds from, the state budget. Penalties escalate with the financial damage caused and with aggravating factors (organised or business-like commission): the base offence carries up to 3 years' imprisonment; this rises to 1–5 years where the damage is "significant" or the base offence is committed in a criminal association or as a business; 2–8 years where the damage is "particularly large" (or the significant-damage version is committed in association/as a business); and 5–10 years where the damage is "particularly significant" (or the particularly-large-damage version is committed in association/as a business). A defendant who repays the damage before indictment can have the sentence mitigated without limit, except where the offence was committed by an organised or criminal group. [9]
Penalties (mulasztási bírság — administrative fines). Under Art., unless a specific provision sets a different figure: the general default penalty (§220) for breaching an obligation under tax law is up to HUF 400,000 for a natural person and up to HUF 1,000,000 for a non-natural person (company). Specific higher caps apply to particular breaches — notably §228: failure to issue a számla, egyszerűsített számla or nyugta, or issuing one for other than the true consideration, or failing to meet document-retention duties, is punishable by up to HUF 2,000,000; a bare retention failure (failing to keep printed invoices/receipts) is capped instead at HUF 200,000 (natural person) / HUF 500,000 (non-natural person) per missing document. Failures in the domestic áfa összesítő jelentés (Áfa tv. Annex 10, not the EU recapitulative statement) are capped under §229 at the number of affected invoices multiplied by the general maximum. Annex 10 covers both the supplier's Online Számla invoice data reporting and the buyer's per-invoice M-sheet declarations in the VAT return, so a missed, late, incomplete or wrong Online Számla report can cost up to HUF 1,000,000 per invoice for a company and HUF 400,000 per invoice for an individual. [2]
Tax shortfall penalty (adóbírság). Separately from the above, where an audit finds unpaid tax, an adóbírság of 50% of the shortfall applies (§215), rising to 200% where the shortfall involves concealed revenue, or falsified/forged books, records or documents. This is on top of — not instead of — késedelmi pótlék (late-payment interest), which continues to accrue regardless of any penalty. [2]
Frequently asked questions
I'm a foreign business selling to Hungary — do I need to register for áfa, and does it differ for B2B versus B2C?
It depends on who you're selling to. For B2B services, the general place-of-supply rule (§37) puts the transaction where the Hungarian business customer is established, and that customer self-assesses VAT under reverse charge (§140) — you generally do not need a Hungarian VAT number for the supply alone. For B2C — goods, or digital/electronic services, or once you exceed the EU-wide €10,000 distance-selling threshold — you must charge Hungarian VAT, typically via the EU OSS registration for an EU seller, IOSS for low-value imported goods, or full Hungarian VAT registration (with a fiscal representative if you're established outside the EU). There is no registration threshold for a non-established seller's first taxable Hungarian supply. [1]
What is the alanyi adómentesség threshold in 2026, and can a foreign company use it?
HUF 20,000,000 for 2026, up from HUF 18,000,000 in 2025, rising to HUF 22,000,000 in 2027 and HUF 24,000,000 in 2028. It is open to a taxpayer whose seat — failing that, domicile — is in Hungary (§187), and, since the EU SME scheme was transposed, to an EU-established taxable person applying the same Hungarian exemption to its Hungarian supplies under §195/G, subject to the HUF 20,000,000 domestic ceiling and a cumulative EU turnover cap of EUR 100,000. Only a business established outside the EU cannot use it. [3]
 Source snapshot captured 2026-08-19 — original
Does Hungary have mandatory e-invoicing?
Not in the sense of requiring a structured document for legal invoice validity — a PDF or paper számla remains valid. What is mandatory is real-time invoice data reporting via Online Számla (RTIR), covering essentially all domestic B2B and B2C invoices since 2021, on XML schema v3.0, the only version accepted since 1 April 2021. From 1 September 2026 a lighter, three-day aggregated version of this reporting extends to receipts (nyugta) too. Sector rules for electricity and gas (from 1 July 2025) and water utilities (from 1 January 2026) require electronic invoices to non-household customers; a ViDA concept for mandatory B2B e-invoicing exists but has no date and no bill. See the Hungary e-invoicing guide. [7] [8]
What is the new nyugta (receipt) data-reporting rule starting 1 September 2026?
From that date, both manually issued and computer/till-generated receipts must have their data reported to NAV within three calendar days of issuance, aggregated daily by tax rate. NAV runs a four-month, penalty-free transition from 1 September to 31 December 2026 while businesses adopt the free ePénztárgép app, the KOBAK portal, or a direct system integration; fines apply only from 1 January 2027. [8]
What's the difference between a számla and a nyugta, and when can I issue just a receipt?
A számla carries the full §169 particulars, including both parties' identity, needed for the buyer to deduct input VAT. A nyugta is a simplified cash document (§173) that can be issued instead of a számla, under §165, only where the customer pays the full price in cash (or equivalent) at the point of supply and does not request an invoice — this simplification never applies to intra-EU supplies, distance sales, or a supply to another business or non-taxable legal person. A business customer that needs to deduct VAT should always ask for a full számla. [1]
Important websites
| Purpose | Site |
|---|---|
| Registration / e-services / VAT returns | ONYA — Online Nyomtatványkitöltő Alkalmazás — NAV's online forms and filing portal |
| ÁNYK-to-ONYA/eÁFA/M2M transition hub | NAV — ÁNYK-átállás — guidance for moving off the ÁNYK client, segmented by taxpayer type |
| Real-time invoice / RTIR reporting | Online Számla — mandatory invoice data-reporting platform and XSD schema documentation |
| Receipt data reporting (from 1 Sept 2026) | NAV's free ePénztárgép app and the KOBAK web portal, both reached via nav.gov.hu |
| Road-freight registration (EKAER) | ekaer.nav.gov.hu — mandatory declarations for qualifying road shipments |
| VAT rate lookup | NAV — Áfakulcsok és tárgyi adómentes tevékenységek |
| VAT number verification (Hungary and EU-wide) | EU VIES portal — see our EU VAT verification guide |
| Legislation (VAT Act, Art., Btk.) | Nemzeti Jogszabálytár — Hungary's official consolidated legal database |
Recent changes
Dated, officially-sourced changes to Hungarian VAT, newest first. The full history is in our worldwide tax-updates feed.
- 2026-09-15 — Firewood and wood heating fuels (logs, stumps, brushwood, bundles; heating sawdust and wood waste compressed into pellets or briquettes) moved from 27% to 5% under 2026. évi XLVIII. törvény, published in Magyar Közlöny 2026/122 on 1 September 2026 (updated from the August 2026 bill) — see Rates. (Magyar Közlöny) — see issue — see event record
- 2026-09-01 — Prescription-only medicines and human magistral preparations moved from 5% to 0% (Annex 3/B) under 2026. évi XL. törvény, published in Magyar Közlöny 2026/112 on 13 August 2026; authorised over-the-counter medicines stay at 5% — see Rates. (Magyar Közlöny) — see issue
- 2026-09-01 — Data on both manually issued and computer-generated receipts (nyugta) must be reported to NAV within three calendar days of issuance, aggregated daily by tax rate — extending the real-time reporting regime that already applies to invoices. A four-month transition (1 September–31 December 2026) carries no penalty; fines apply from 1 January 2027. (NAV) — see issue
- 2026-07-31 — 2026. évi XXXV. törvény (promulgated in Magyar Közlöny 2026/102 on 30 July 2026) reversed a planned tightening of the M-lap (received-invoice data reporting) rules: instead of the stricter content requirements otherwise due to take effect from 1 July 2026 under 2025. évi LXXXIII. törvény, the law restores the pre-1-July-2026 per-invoice M-lap content rules with no end date, and its new §380 applies them to returns for the tax period that includes 1 July 2026. (Nemzeti Jogszabálytár) — see issue
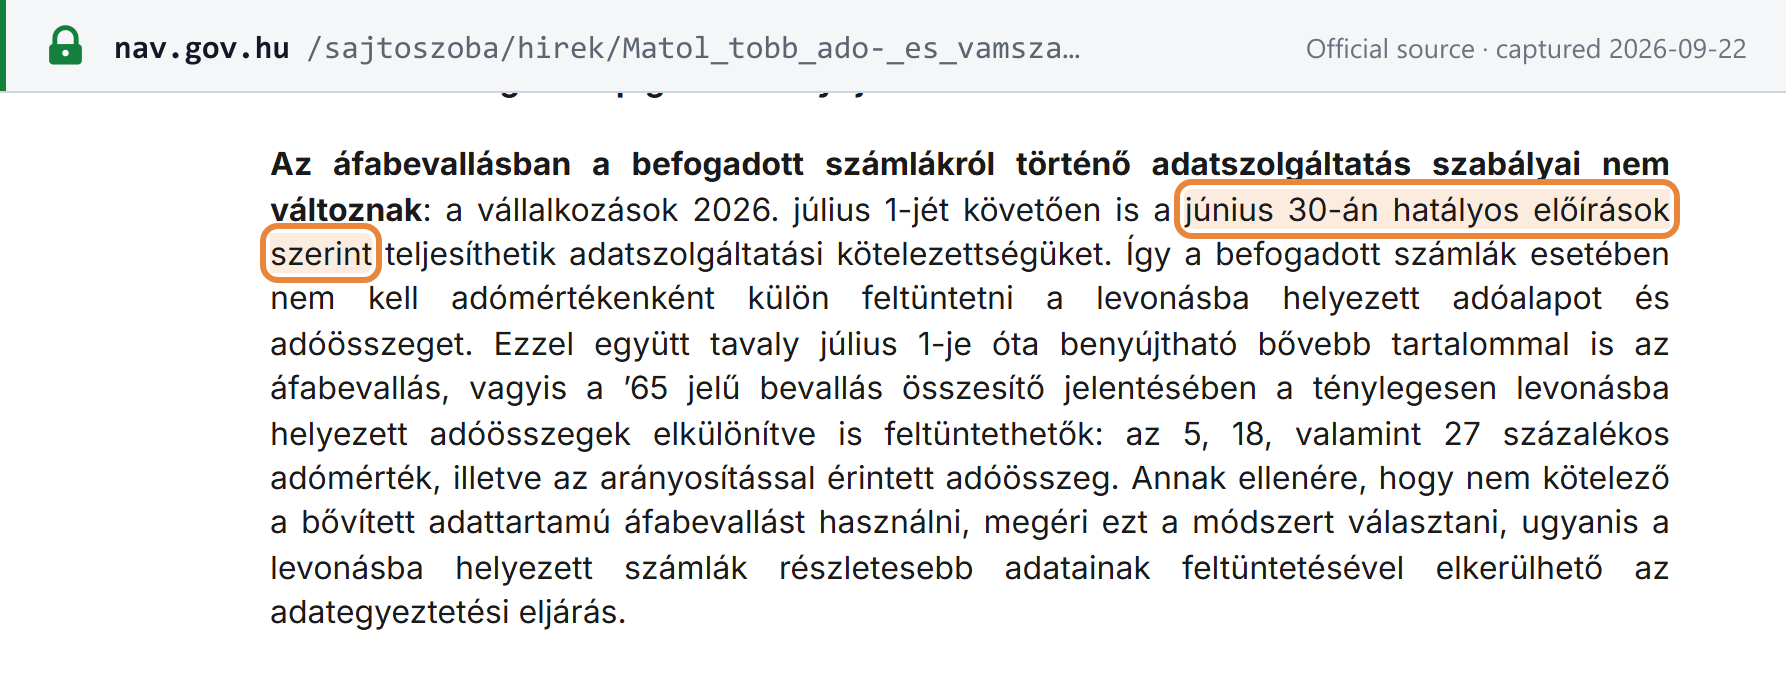 NAV, 31 July 2026 — the planned M-sheet tightening was reversed; the rules in force on 30 June 2026 continue to apply.
- 2026-01-01 — The alanyi adómentesség (small-business VAT exemption) threshold rose from HUF 18,000,000 to HUF 20,000,000, with further scheduled rises to HUF 22,000,000 (2027) and HUF 24,000,000 (2028). (NAV)
Ahead — scheduled changes that have not yet taken effect:
- 2027-01-01 — The 5% VAT rate for sales of new homes is withdrawn (Act LV of 2024); §371 keeps 5% to 31 December 2030 for advances and supplies that meet a permit or notification condition, and new flats of up to 150 m² in brownfield action areas stay at 5%. Otherwise 27% applies. (NAV) — see event record
- 2027-01-01 — The small-business exemption (alanyi adómentesség) threshold rises from HUF 20,000,000 to HUF 22,000,000, and to HUF 24,000,000 from 2028 (Áfa tv. §188(2)). (NAV) — see event record
- 2027-01-01 (NAV gives no ÁNYK closing date, only the 2027 replacement) — NAV confirms that from 2027 the general-purpose ÁNYK (Általános Nyomtatványkitöltő Keretprogram) form-filler client is being entirely replaced by ONYA, eÁFA/eVAT, and machine-to-machine (M2M) submission for filing tax returns, including VAT returns — see Filing and payment. (NAV) — see issue
Reference links
- 2007. évi CXXVII. törvény az általános forgalmi adóról (VAT Act) — Nemzeti Jogszabálytár
- 2017. évi CL. törvény az adózás rendjéről (Art.) — Nemzeti Jogszabálytár
- 2012. évi C. törvény a Büntető Törvénykönyvről (Btk.) — Nemzeti Jogszabálytár
- 2026. évi XXXV. törvény — Nemzeti Jogszabálytár
- NAV — Emelkedik az alanyi adómentesség értékhatára
- NAV — A NAV segít: négy hónapos átállási időszak a nyugtaadat-szolgáltatásban
- NAV — Bevallási, adófizetési információk
- Magyar Közlöny 2026/112 — 2026. évi XL. törvény (prescription medicines at 0%)
- Magyar Közlöny 2026/122 — 2026. évi XLVIII. törvény (firewood at 5%)
- NAV — Online Számla
- NAV — ÁNYK-átállás: tudástár a NAV-tól
For the Hungarian tax identifier formats — the personal adóazonosító jel and the entity adószám, including the VAT-status digit and EKAER — see our Hungary Tax ID Guide. To verify a Hungarian VAT number, see our EU VAT verification guide.