Poland Tax ID Numbers — NIP, PESEL, VAT-UE, REGON and KRS Explained
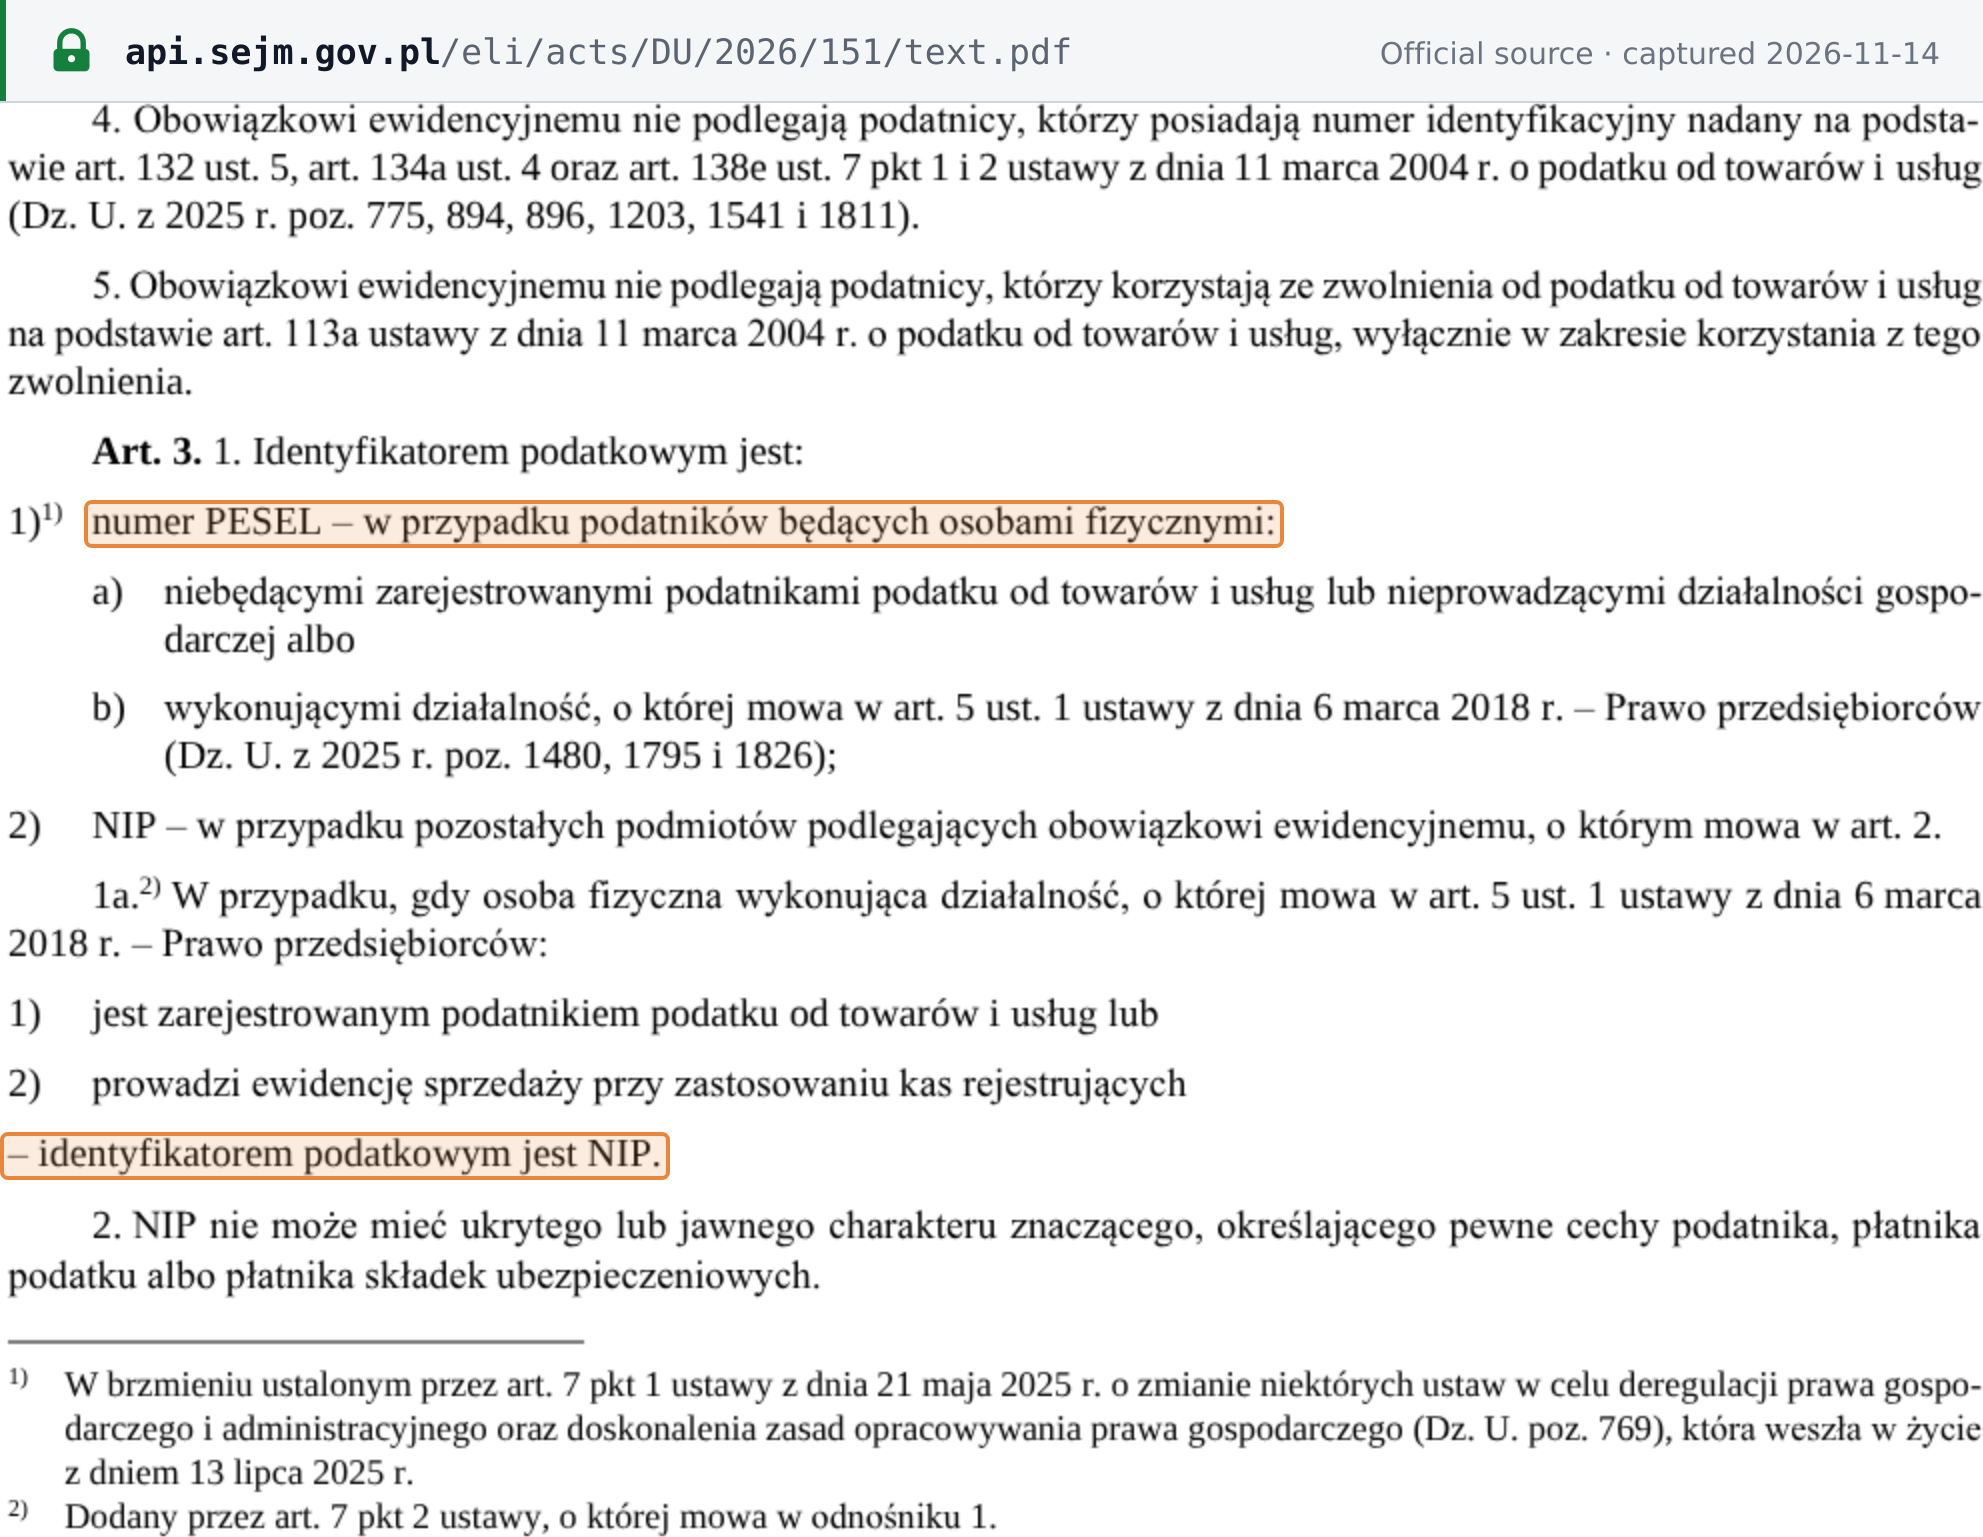
Poland has two tax identifiers (identyfikatory podatkowe) in law: the NIP (numer identyfikacji podatkowej, tax identification number) and the PESEL (numer Powszechnego Elektronicznego Systemu Ewidencji Ludności, the national population-register number). Under article 3 of the Act of 13 October 1995 on the registration and identification of taxpayers and payers, the PESEL is the tax identifier of individuals who are not VAT-registered and not in business, or who carry out "unregistered activity"; everyone else subject to the registration duty uses the NIP. [1] The NIP is assigned by the head of the tax office (naczelnik urzędu skarbowego) through the central taxpayer register CRP KEP, which the Head of the National Revenue Administration (Szef Krajowej Administracji Skarbowej, KAS) runs. [1] The PESEL is assigned by the minister responsible for computerisation (minister właściwy do spraw informatyzacji). [3] A business trading within the EU uses its NIP with the prefix PL as its VAT-UE number. Two further numbers appear next to the NIP on company documents but are not tax IDs: the REGON statistical number, kept by the President of Statistics Poland (GUS), and the KRS number of the National Court Register, kept by the registry courts. For VAT rates, invoicing and filing, see the Poland VAT guide.
Poland's Tax IDs at a Glance
| Number | Format | Example | Who has it | Issued by | Tax ID? |
|---|---|---|---|---|---|
| NIP | 10 digits; ^[1-9]((\d[1-9])|([1-9]\d))\d{7}$ | 2234567895 — Ministry of Finance sample | Companies, partnerships, sole traders, VAT-registered persons, tax payers (withholding agents) and social-contribution payers | Head of the tax office, through CRP KEP | Yes |
| PESEL | 11 digits; ^\d{11}$ | 02070803628 — Ministry of Finance sample | Individuals not in business, not VAT-registered and not payers; unregistered-activity persons without VAT registration or a cash register | Minister responsible for computerisation | Yes |
| VAT-UE number | PL + NIP; ^PL\d{10}$ | PL2234567895 — illustrative | Taxpayers registered as podatnik VAT UE | Head of the tax office (confirmed on form VAT-5UE) | VAT, intra-EU transactions |
| REGON | 9 digits (entity) or 14 digits (local unit); ^(\d{9}|\d{14})$ | none published | Legal persons, units without legal personality, individuals running a business | President of GUS | No — statistical |
| KRS number | 10 digits with leading zeros; ^\d{10}$ | 0000000000 — illustrative layout | Companies, partnerships, foundations, associations | Registry courts (sądy rejestrowe) | No — court register |
Which Number You Use: NIP or PESEL
Article 3(1) of the registration act sets the split, in the wording in force since 13 July 2025 (Act of 21 May 2025, Dz.U. 2025 poz. 769): [1]
- PESEL is the tax identifier of an individual taxpayer who (a) is not a registered VAT taxpayer and does not run a business, or (b) carries out activity under article 5(1) of the Entrepreneurs' Law (Prawo przedsiębiorców), known as działalność nierejestrowa (unregistered activity).
- NIP is the tax identifier of every other entity subject to the registration duty.
- Article 3(1a): an individual doing unregistered activity who is a registered VAT taxpayer or keeps sales records on a cash register uses the NIP.
- Article 3(2): the NIP may have no hidden or open meaning describing its holder.
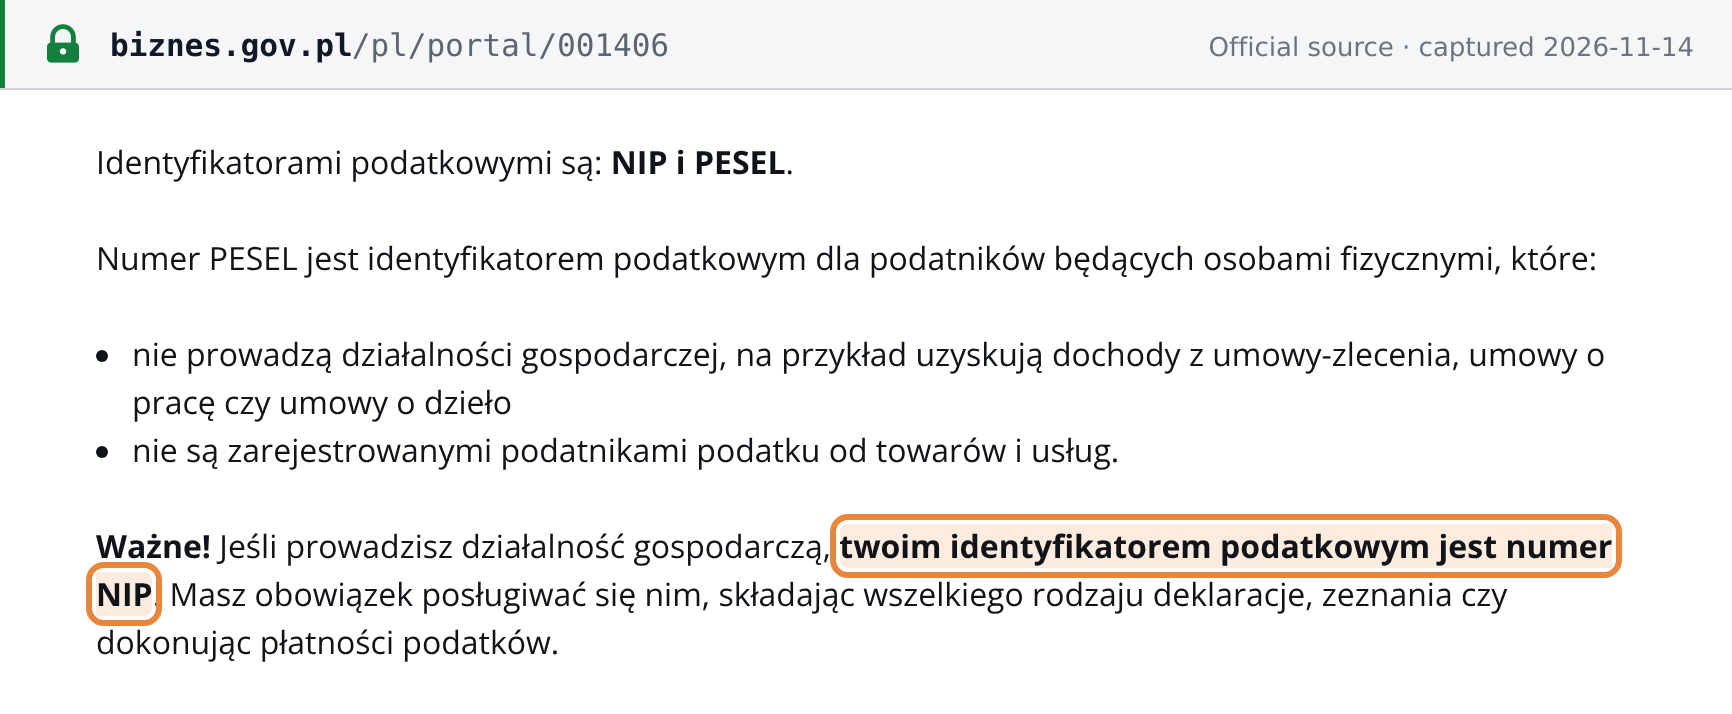
The government's business portal puts the same rule in plain words: "Identyfikatorami podatkowymi są: NIP i PESEL" (the tax identifiers are the NIP and the PESEL). The PESEL is the identifier of individuals who do not run a business — for example people earning from an employment contract, a contract of mandate (umowa-zlecenie) or a contract for specific work (umowa o dzieło) — and who are not registered VAT taxpayers. "Jeśli prowadzisz działalność gospodarczą, twoim identyfikatorem podatkowym jest numer NIP" — if you run a business, your tax identifier is the NIP. [2]
The Ministry of Finance's ZAP-3 form, in force from 1 January 2026, describes the PESEL user as a person who meets all of these at once: has a PESEL, runs no business, is not a registered VAT taxpayer, is not a tax payer (płatnik podatków, e.g. an employer withholding income tax) and is not a payer of social and health insurance contributions — or who does unregistered activity without VAT registration or a cash register. [14] An individual who employs staff therefore needs a NIP even without a business.
Unregistered activity. Under article 5(1) of the Entrepreneurs' Law, activity by an individual is not business activity where the revenue due from it does not exceed 225% of the minimum wage in any quarter and the person has not run a business in the last 60 months. [11] Such a person is not entered in the business register (CEIDG) and, since 13 July 2025, uses the PESEL unless article 3(1a) applies.
History. The NIP is older than the PESEL-as-tax-ID rule. The 1995 Act entered into force on 1 January 1996 (article 23), and identification numbers issued under the earlier law became NIPs (article 20). [1] The reform effective 1 September 2011 changed who uses the PESEL instead of the NIP; it did not start NIP issuance.
NIP (Numer Identyfikacji Podatkowej)
| Field | Detail |
|---|---|
| Official name | Numer identyfikacji podatkowej (NIP) |
| Format | 10 digits; the first three are the tax-office code and the last is a check digit |
| Regex | ^[1-9]((\d[1-9])|([1-9]\d))\d{7}$ — the Ministry of Finance schema pattern, with anchors added |
| Example | 2234567895 — the Ministry of Finance's sample NIP |
| Written as | A plain string of digits, without spaces or dashes |
| Issued by | Head of the tax office, through CRP KEP (run by the Head of KAS) |
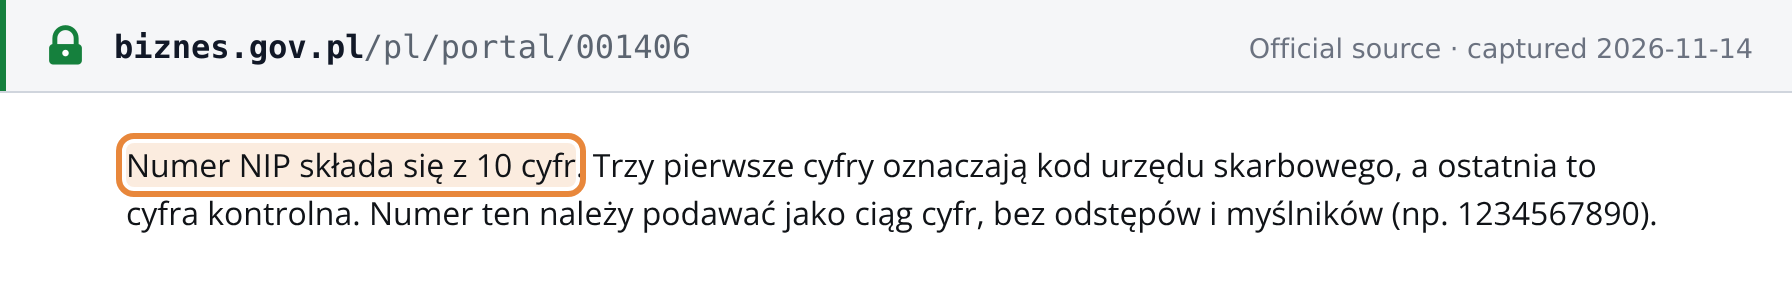
The business portal states: "Numer NIP składa się z 10 cyfr. Trzy pierwsze cyfry oznaczają kod urzędu skarbowego, a ostatnia to cyfra kontrolna. Numer ten należy podawać jako ciąg cyfr, bez odstępów i myślników" — the NIP consists of 10 digits; the first three are the code of the tax office and the last is the check digit; write it as a string of digits without spaces or dashes. [2]
The Ministry of Finance's XML type TNrNIP, used in the KSeF e-invoice schemas, gives the pattern [1-9]((\d[1-9])|([1-9]\d))\d{7}: the first digit is never 0, and the second and third digits are never both 0. [5]
How it is assigned. The NIP is assigned in CRP KEP (Centralny Rejestr Podmiotów – Krajowa Ewidencja Podatników) after an identification application (zgłoszenie identyfikacyjne); for entities entered in the KRS it is assigned automatically from the data the court register sends. The head of the tax office confirms the assignment no later than 3 days after a correct application arrives. For entities in the KRS or in the business register CEIDG, the confirmation is the disclosure of the NIP in that register. [1] Where the holder has a PESEL, the confirmation also states it.
NIP check digit
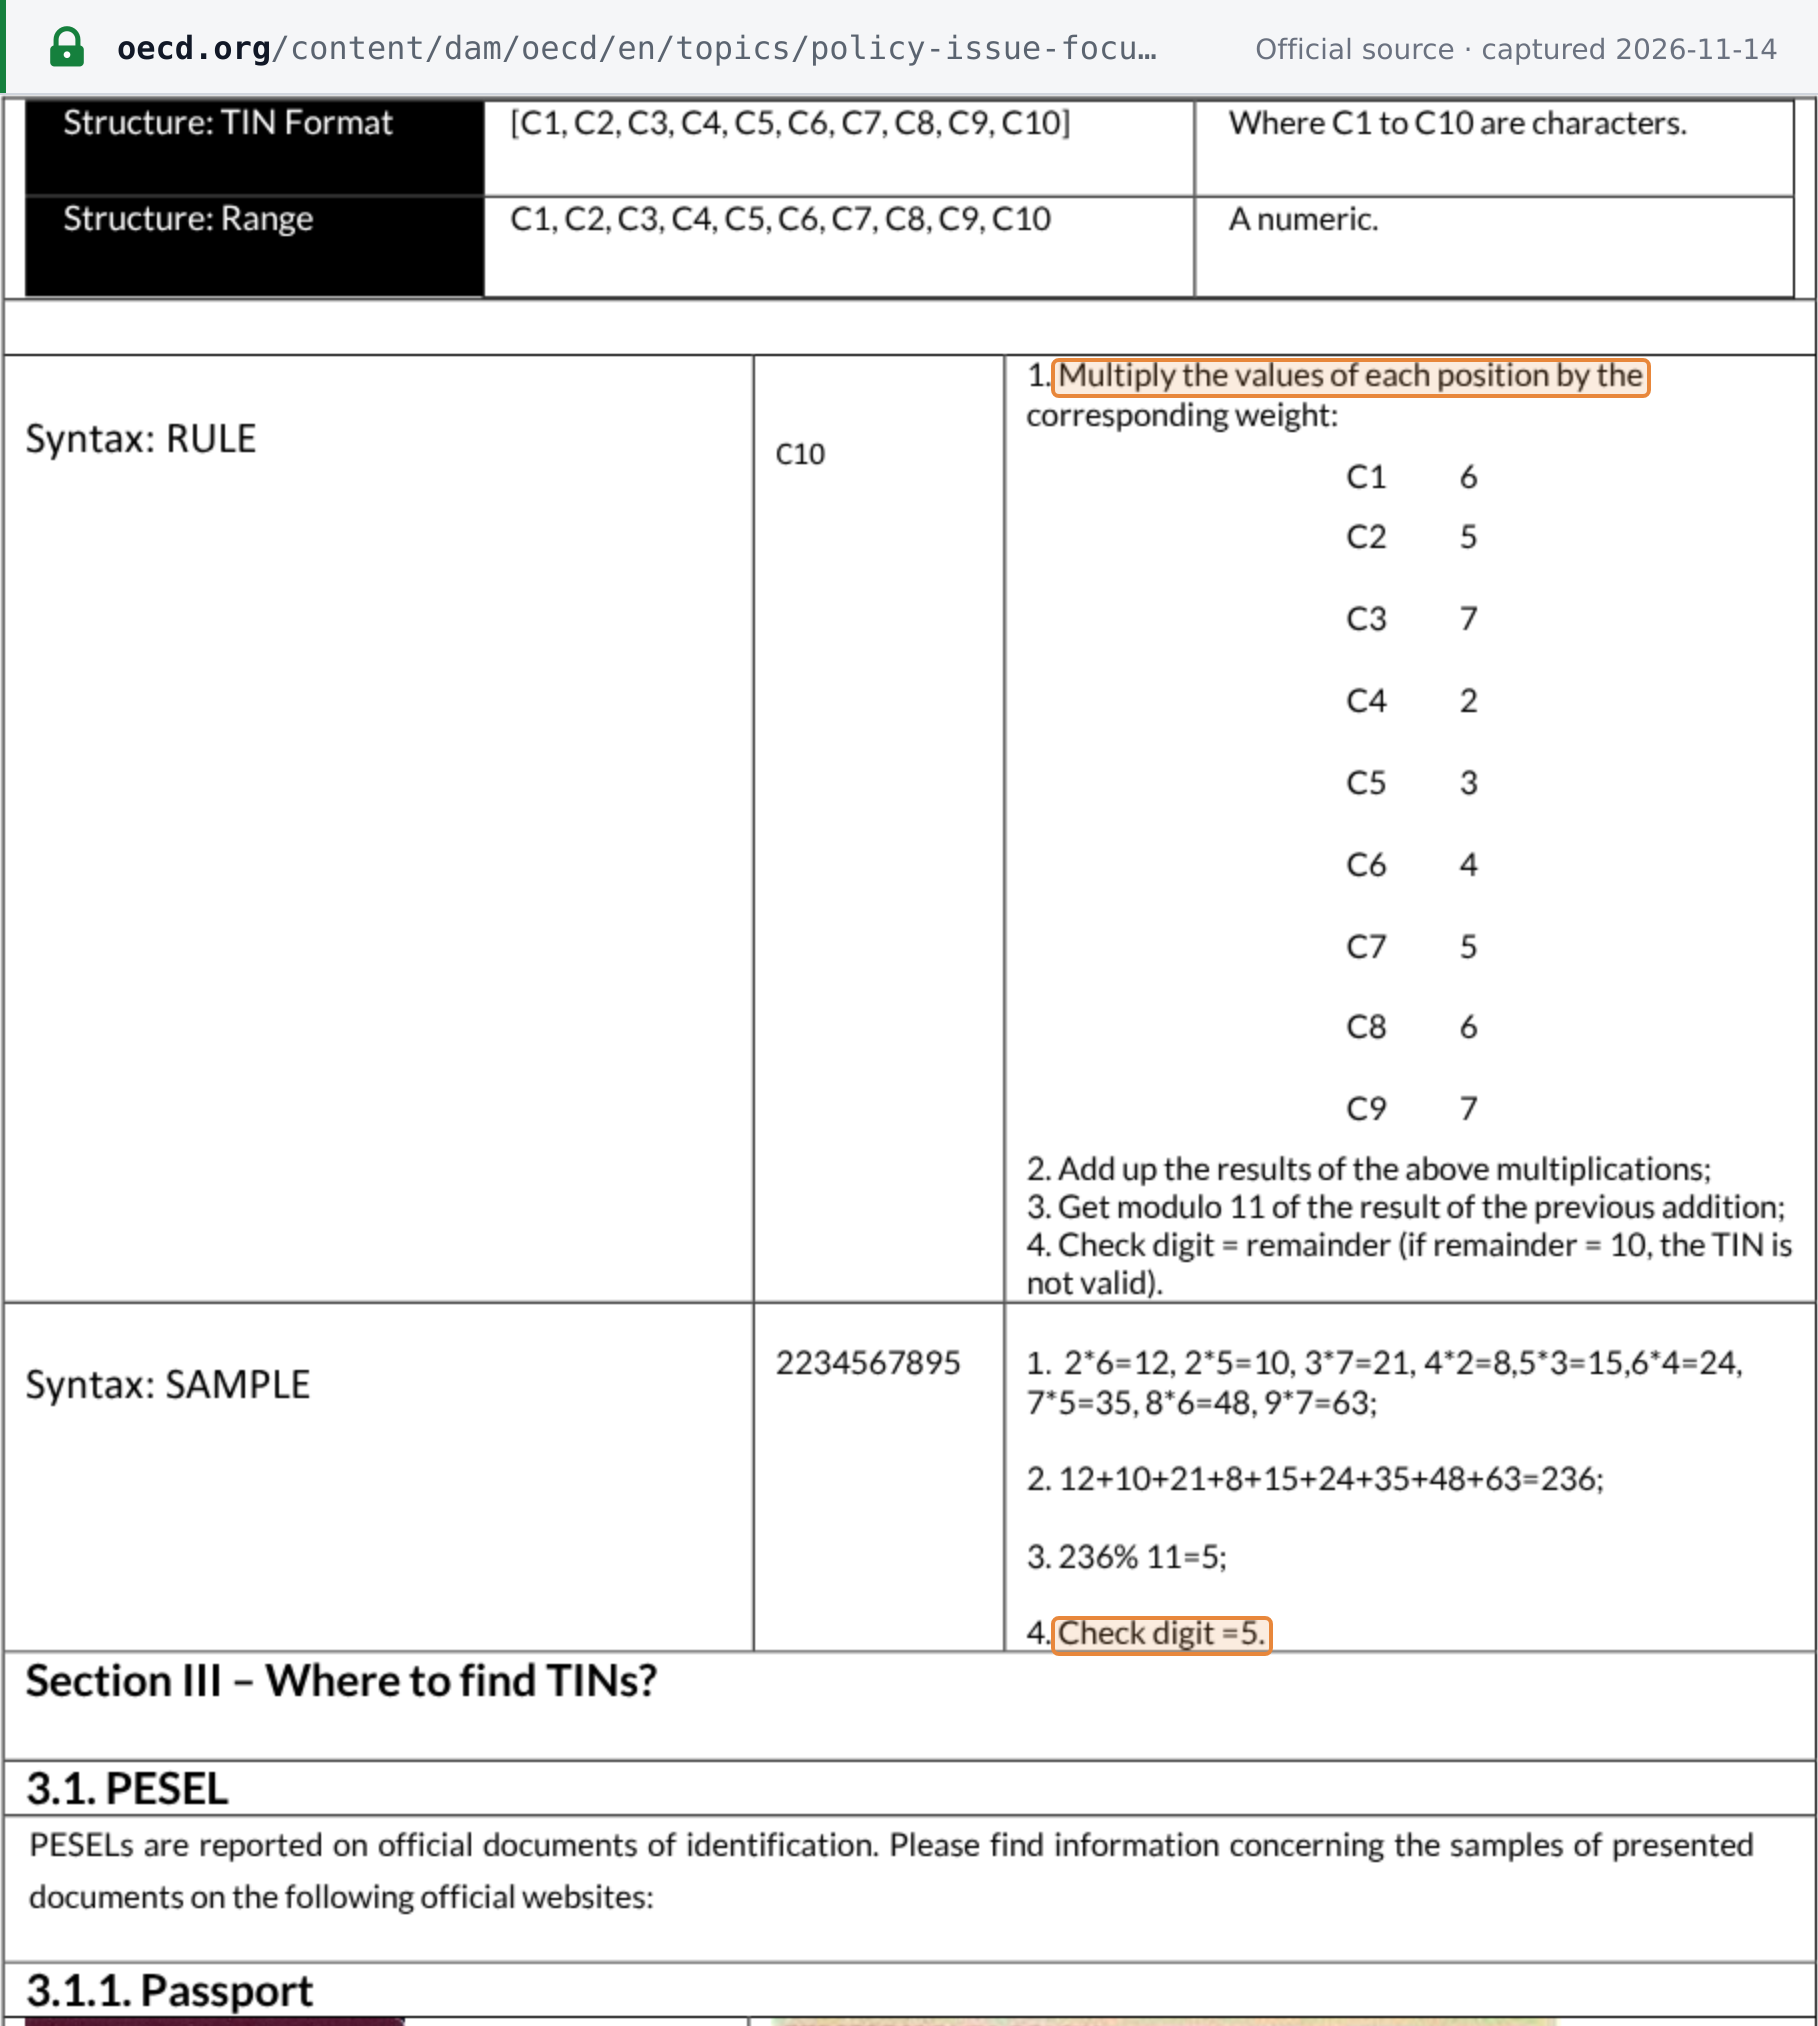
The check-digit rule is published by the Ministry of Finance in its tax identification number information sheet for the EU and OECD TIN portals (Ministry of Finance of Poland, 2023), not in the registration act or a regulation under it: [4]
- Multiply digits 1–9 by the weights 6, 5, 7, 2, 3, 4, 5, 6, 7.
- Add up the products.
- Take the sum modulo 11.
- The remainder is the check digit (digit 10). If the remainder is 10, the NIP is not valid.
Worked example with the Ministry's sample 2234567895: 2×6 + 2×5 + 3×7 + 4×2 + 5×3 + 6×4 + 7×5 + 8×6 + 9×7 = 12 + 10 + 21 + 8 + 15 + 24 + 35 + 48 + 63 = 236; 236 mod 11 = 5, the tenth digit.
A passing check digit only proves the number is well-formed. To confirm that a NIP was actually assigned, look it up in an official register — see How to verify a Polish tax ID.
PESEL
| Field | Detail |
|---|---|
| Official name | Numer Powszechnego Elektronicznego Systemu Ewidencji Ludności (PESEL) |
| Format | 11 digits: date of birth (6), ordinal number with sex digit (4), check digit (1) |
| Regex | ^\d{11}$ (Ministry of Finance schema type TNrPESEL) |
| Example | 02070803628 — Ministry of Finance sample (born 8 July 1902, female) |
| Issued by | Minister responsible for computerisation, ex officio or on application |
Article 15(2) of the Act on population records (ustawa o ewidencji ludności) defines the PESEL as an eleven-digit numeric code that uniquely identifies a person and contains the date of birth, an ordinal number, the sex and a check digit: [3]
- Digits 1–6 — date of birth as YYMMDD, with the century coded into the month: add 80 for 1800–1899, 0 for 1900–1999 and 20 for 2000–2099. (The Ministry of Finance's TIN sheet also lists +40 for 2100–2199 and +60 for 2200–2299; those two codes are not in the statute.) [4]
- Digits 7–10 — the ordinal number. Its last digit (digit 10) gives the sex: even, including 0, for women; odd for men.
- Digit 11 — the check digit.
Article 16 provides that the PESEL is assigned ex officio, or on application for a person who must hold one under other laws, and that "Numer PESEL nadaje minister właściwy do spraw informatyzacji" — the PESEL is assigned by the minister responsible for computerisation. [3]
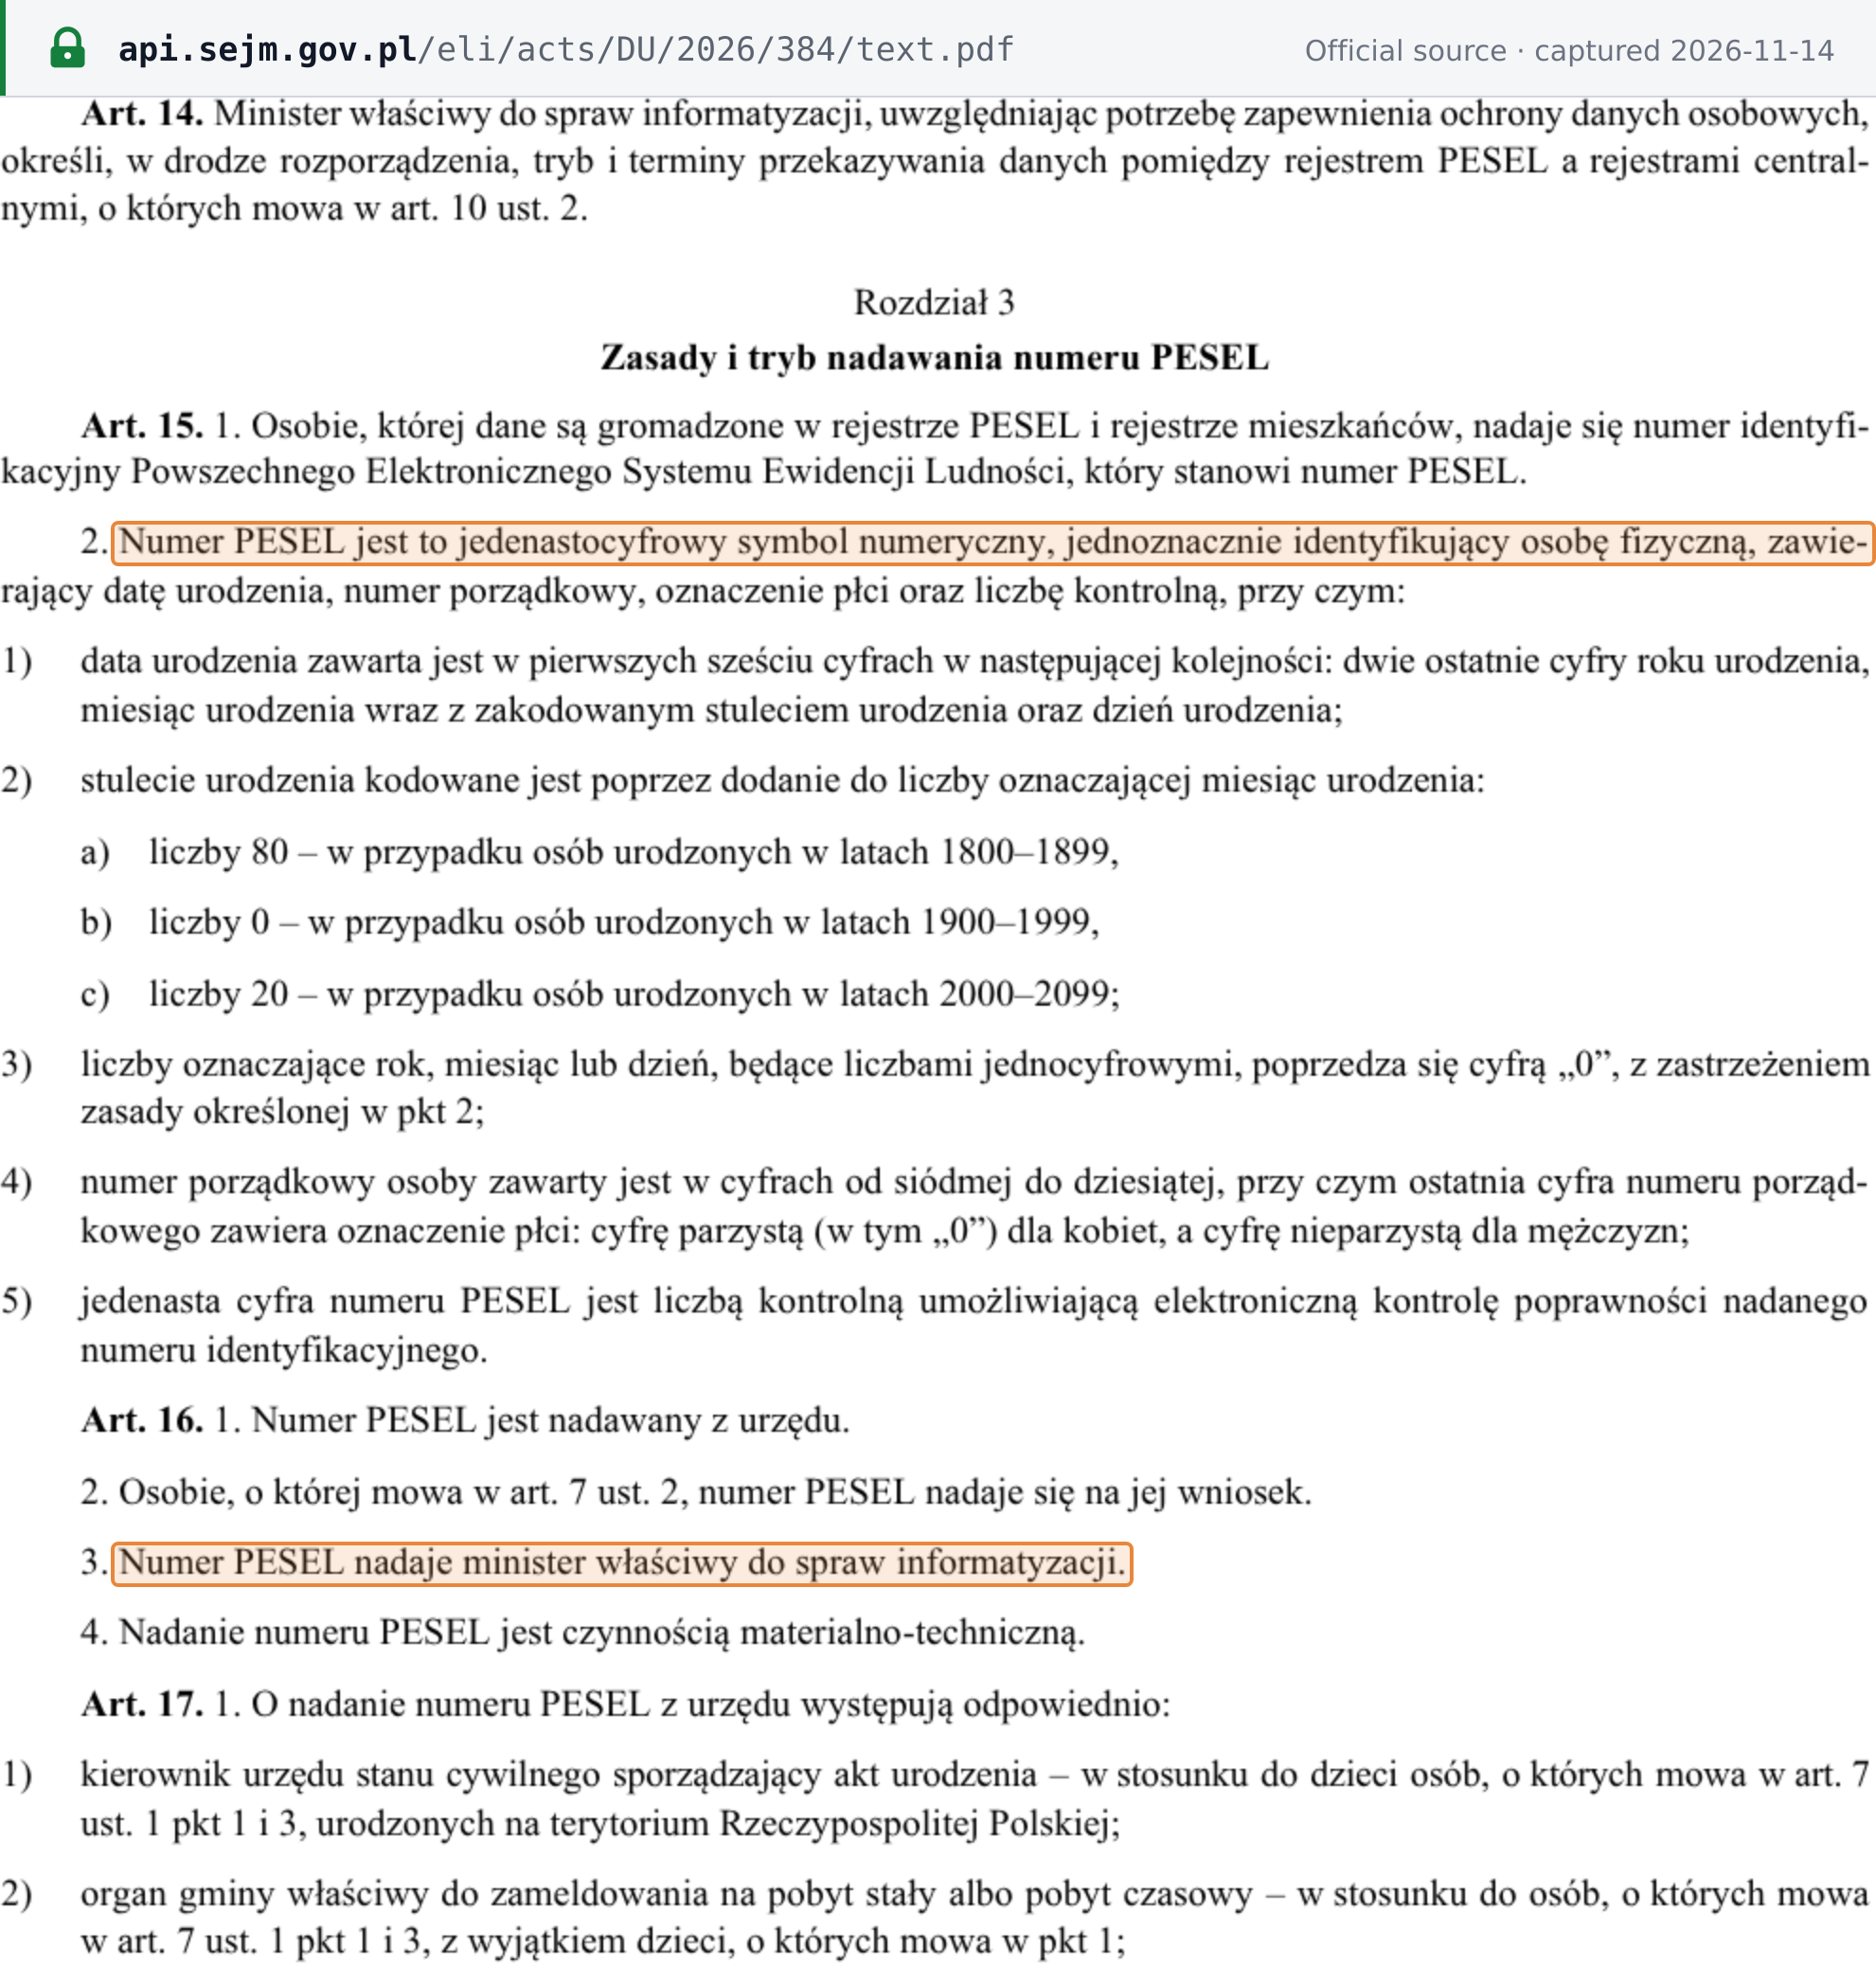
Who receives one. The PESEL register holds Polish citizens living in Poland, Polish citizens abroad who apply for a Polish identity document, and foreigners living in Poland (article 7(1)). The municipality requests the PESEL ex officio when it registers a person's permanent or temporary residence (article 17(1)(2)). A citizen of another EU or EFTA member state or of Switzerland staying in Poland must register their place of permanent or temporary residence no later than the 30th day after arriving there (article 41(1)). Others who must hold a PESEL under other laws apply for one (article 16(2)). [3]
PESEL check digit
The Ministry of Finance's TIN sheet publishes this rule: [4]
- Multiply digits 1–10 by the weights 1, 3, 7, 9, 1, 3, 7, 9, 1, 3.
- Add up the last digit of each product.
- Subtract the last digit of that sum from 10.
- The result is the check digit (digit 11).
The sheet does not say what happens when the last digit of the sum is 0. Subtracting 0 from 10 gives 10, which cannot be a single digit, so implementations use (10 − (sum mod 10)) mod 10, which gives 0 in that case. That last step is derived, not published.
Worked example with the Ministry's sample 02070803628: the products are 0, 6, 0, 63, 0, 24, 0, 27, 6, 6; their last digits add up to 0 + 6 + 0 + 3 + 0 + 4 + 0 + 7 + 6 + 6 = 32; 10 − 2 = 8, the eleventh digit.
VAT-UE Number (PL + NIP)
Poland has no separate VAT number. A business registered as an EU VAT taxpayer (podatnik VAT UE) uses its NIP preceded by the code PL. Under article 97(10) of the VAT Act, it must do so when it makes intra-Community acquisitions or supplies of goods, supplies services to which article 100(1)(4) applies (the services reported in the EU sales list), buys services as the taxpayer under article 28b (import of services), and moves goods under the call-off stock procedure. [6]
- Format:
PLfollowed by the 10-digit NIP —^PL\d{10}$, for examplePL2234567895(illustrative, built on the Ministry sample). - How you get it: you notify EU VAT registration on the same VAT-R form used for VAT registration, before the first intra-EU transaction (article 97(1)), and the tax office confirms it on form VAT-5UE. [7]
- Exempt businesses too: under articles 97(2) and 10(1)(2) of the VAT Act, a business that is not an active VAT payer must register for EU VAT once its intra-Community acquisitions exceed PLN 50,000 in the year (as at 14 November 2026). [6] [7]
A taxpayer that is VAT-registered only domestically (podatnik VAT czynny) has no VAT-UE registration, so its PL number does not validate in VIES even though the NIP is real.
REGON
| Field | Detail |
|---|---|
| Official name | Numer identyfikacyjny REGON (register of the national economy) |
| Format | 9 digits for an entity (8-digit ordinal + check digit); 14 digits for a local unit (the parent's 9 digits + 4-digit unit ordinal + check digit) |
| Regex | ^(\d{9}|\d{14})$ (Ministry of Finance schema type TNrREGON) |
| Issued by | President of Statistics Poland (GUS) |
The Council of Ministers regulation of 30 November 2015 on the REGON register (§ 12(3), (4) and (8)) sets the structure: the 9-digit number may carry no hidden or open meaning about the entity, the first eight digits are an ordinal number and the ninth a check digit; the number stays the same for the entity's lifetime and does not pass to a legal successor; a local unit's 14-digit number repeats the parent's nine digits, adds a four-digit ordinal and ends in a check digit. [8] Since the amendment published in December 2025 (Dz.U. 2025 poz. 1792), the statistics act calls it the "rejestr REGON", kept by the President of GUS. [9] An individual doing only unregistered activity is not entered in the register. [10]
Checksum — not published. The regulation says a check digit exists but does not state how it is calculated, and neither the GUS REGON (BIR) technical documentation nor the GUS REGON pages publish an algorithm (as at 14 November 2026). Weights circulate in software libraries, but no official source publishes them. Validate a REGON by looking it up in the GUS REGON database (see below). REGON is a statistical number, not a tax ID.
KRS Number
The KRS number (numer Krajowego Rejestru Sądowego) identifies an entry in the National Court Register — companies, partnerships, foundations and associations. Under article 2(1) of the KRS Act, the register is kept in an IT system by the district (commercial) courts, called registry courts. [12] The number has 10 digits and is written with leading zeros (Ministry of Finance schema type TNrKRS, pattern \d{10}). [5] An entity entered in the KRS receives its NIP automatically, and the current KRS extract shows the KRS number, the REGON and the NIP together. KRS is a court-register number, not a tax ID.
Who Must Register
For a NIP
You need a NIP if you are not a PESEL user under article 3 (see Which number you use): every entity, sole trader, VAT-registered individual, tax payer and contribution payer. When to apply, under the registration act: [1]
- VAT and excise taxpayers — before their first taxable activity; individuals only when they file a VAT registration (VAT-R) or an excise registration (article 6(1)).
- Other taxpayers and payers — no later than their first return or first tax payment (article 6(1a)).
- KRS entities — the NIP is assigned automatically; they then file only the supplementary data (form NIP-8) within 21 days of the KRS entry (article 5(2c)).
- Changes — identification data must be updated within 7 days of the change (article 9(1)).
A business that uses the EU SME scheme under article 113a of the VAT Act is outside the registration duty, but only for that exemption (article 2(5)).
For VAT
Every taxable person must file a VAT registration (form VAT-R) with the head of the tax office before the day of its first taxable activity (article 96(1) VAT Act). [6] The business portal states it in English: "As an entrepreneur, you are, as a rule, obliged to register for VAT"; you do not need to register if your sales do not exceed PLN 240,000 per year, or if you sell only VAT-exempt goods and services; the form "must be submitted no later than the day before the date on which the sale of goods or supply of services subject to VAT commences". [7]
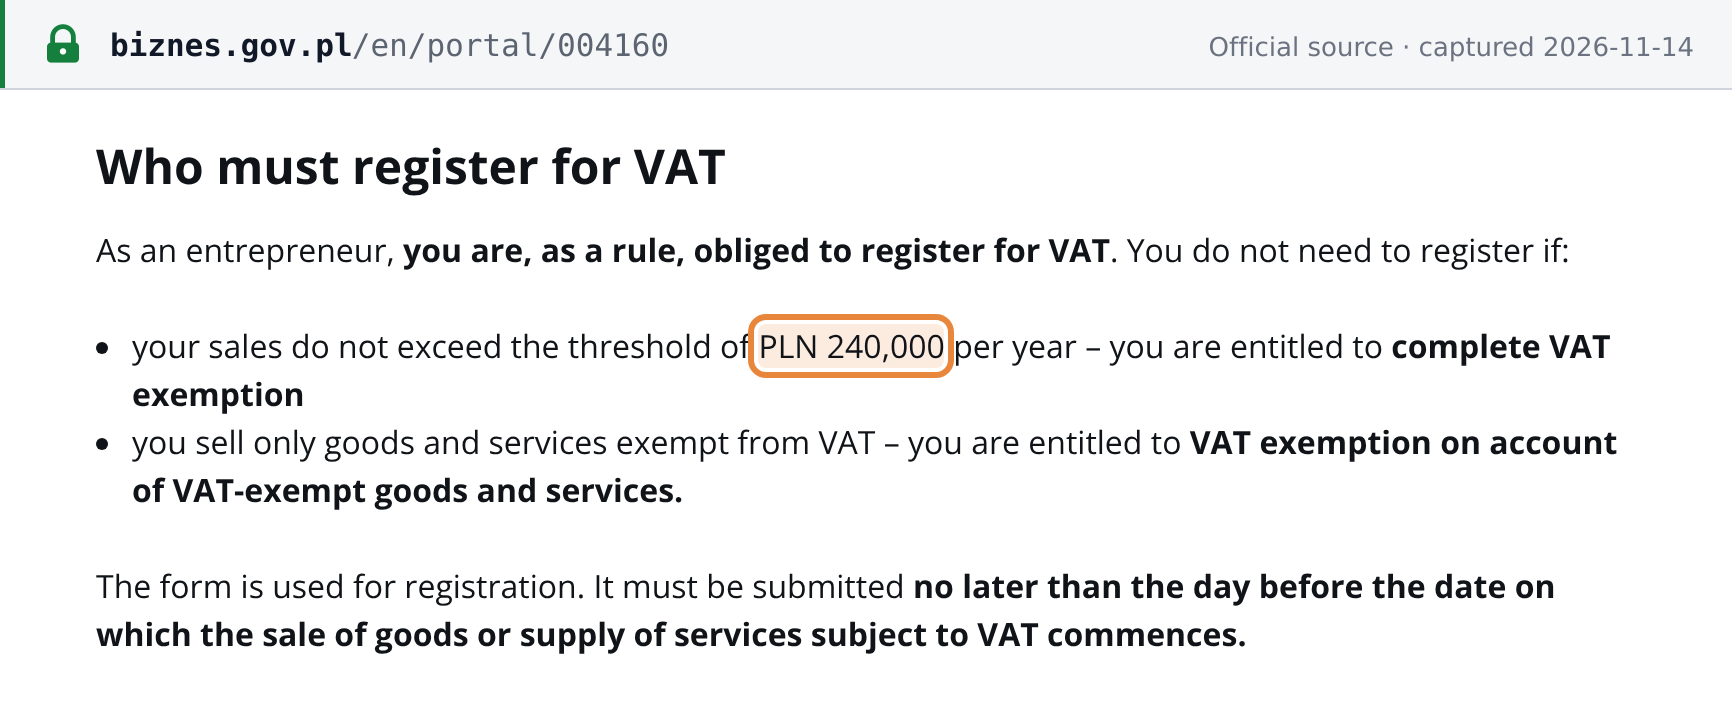
Threshold — PLN 240,000, residents only (from 1 January 2026). The small-business exemption in article 113(1) covers a taxpayer with its seat of business in Poland whose sales, excluding VAT, did not exceed PLN 240,000 in the previous or the current tax year. [6] The Act of 24 June 2025 (Dz.U. 2025 poz. 896) raised the figure from PLN 200,000 with effect from 1 January 2026. [13] A business that starts during the year applies the limit in proportion to the period of activity (article 113(9)).
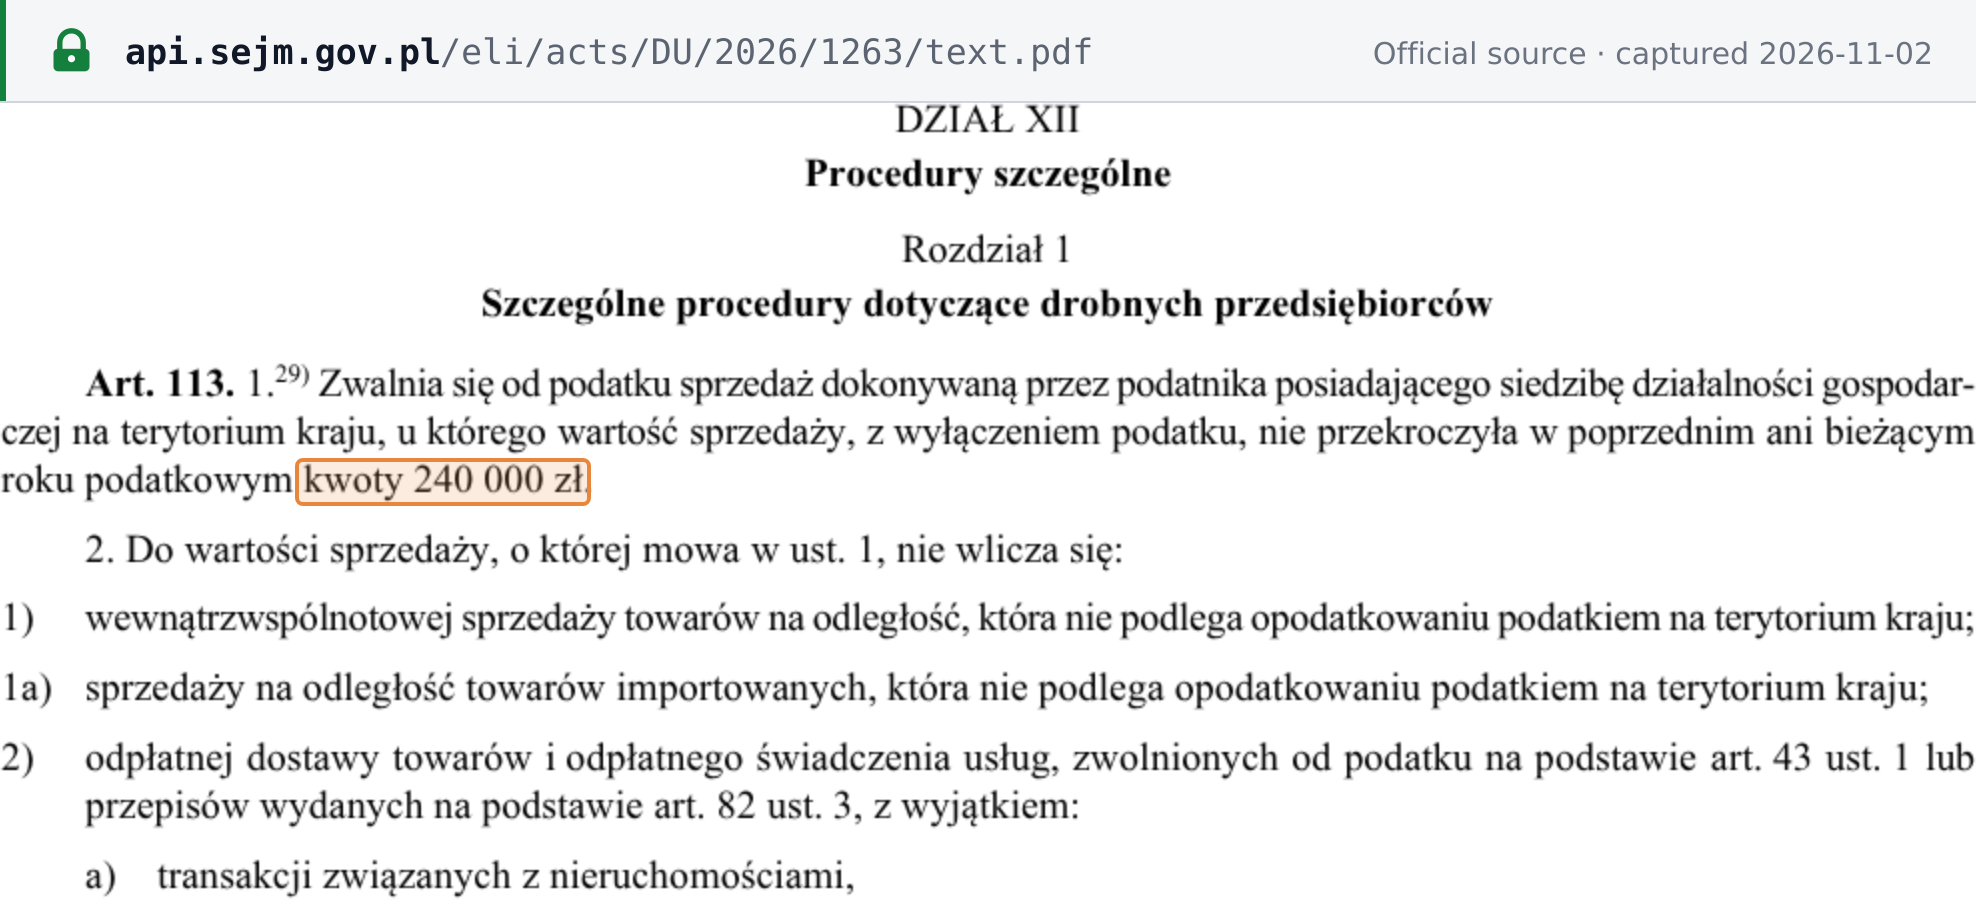
Non-established businesses — no threshold. Because the article 113(1) exemption is limited to businesses seated in Poland, a business established elsewhere registers before its first taxable transaction in Poland, whatever its value. [6] Points to know (VAT Act, as at 14 November 2026):
- Where: a business with no seat or fixed establishment in Poland files its VAT registration with the Head of the Second Tax Office Warszawa-Śródmieście (Drugi Urząd Skarbowy Warszawa-Śródmieście). [7]
- Fiscal representative: a taxpayer with no seat or fixed establishment in any EU member state that must register as an active VAT payer must appoint a fiscal representative (article 18a(1)).
- EU SME scheme: since 1 January 2025 a business seated in another member state can be exempt in Poland without registering there (article 96(3d)) if its EU-wide turnover did not exceed EUR 100,000 in the previous and current year, its Polish sales stay within the article 113(1) limit, and it holds an identification number with the suffix EX from its home state (article 113a). See the EU VAT SME scheme explainer.
- Distance sellers: a non-established seller making intra-EU distance sales of goods located in Poland registers before the supply (article 96(1a)).
How to Register
There is no separate Lookuptax how-to-register page for Poland yet; the Poland VAT guide's registration section covers VAT registration. In brief, the NIP is applied for on these Ministry of Finance forms (regulation of 19 July 2021, consolidated text Dz.U. 2024 poz. 1367; NIP-7 and ZAP-3 replaced from 1 January 2026 by Dz.U. 2025 poz. 1681): [15] [14]
| Form | Who files it |
|---|---|
| CEIDG application | A sole trader registering a business in CEIDG: the identification application is part of the CEIDG entry application and is forwarded to the tax office automatically. [2] |
| NIP-2 | Legal persons and organisational units without legal personality that are taxpayers or payers. |
| NIP-7 | Individuals who are not entrepreneurs or are not entered in CEIDG — for example VAT-registered individuals, tax or contribution payers, persons without a PESEL, and unregistered-activity persons with VAT registration or a cash register. |
| NIP-8 | Supplementary data, for example for entities entered in the KRS. |
| ZAP-3 | Updates (address, contact details, bank account) by individuals who use the PESEL as their tax identifier. |
| VAT-R | VAT registration, a separate form filed with the tax office (see above). |
The business portal sums it up: an individual starting a business registered in CEIDG files the NIP identification application in the CEIDG application; an individual doing unregistered activity, or a VAT taxpayer not entered in CEIDG, files form NIP-7 with the head of the tax office for their place of residence. [2]
The NIP in Payments: Split Payment
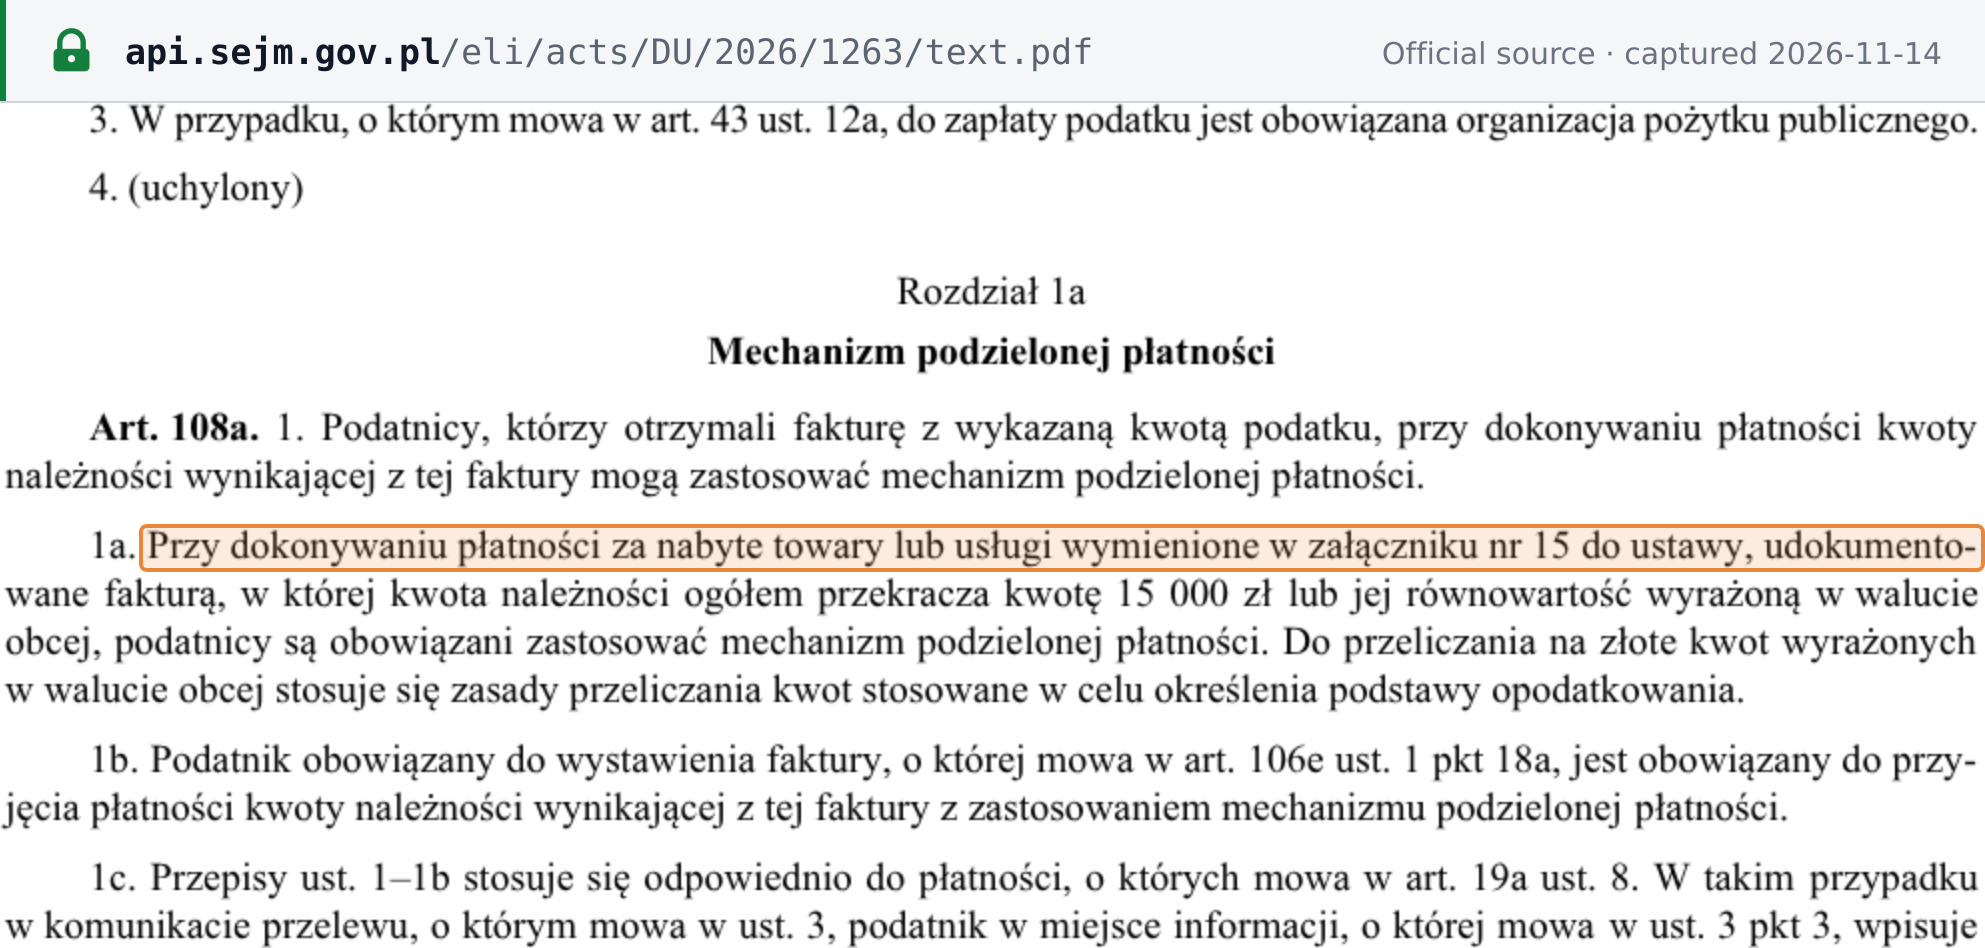
Split payment (mechanizm podzielonej płatności) carries the supplier's tax ID. Under article 108a of the VAT Act, a buyer must pay by split payment when the invoice total exceeds PLN 15,000 and the invoice covers goods or services listed in Annex 15; the transfer message must state the invoice number (for a KSeF invoice, its KSeF number) and "numer, za pomocą którego dostawca towaru lub usługodawca jest zidentyfikowany na potrzeby podatku" — the number under which the supplier is identified for tax purposes. [6] The seller must mark such an invoice "mechanizm podzielonej płatności" (article 106e(1)(18a)). The tax office can set an additional liability of 30% of the VAT on the Annex 15 goods or services on the seller for a missing annotation (article 106e(12)) and on the buyer for paying outside split payment (article 108a(7)), with exceptions where the payment was in fact made by split payment or the supplier settled the VAT (articles 106e(13) and 108a(8)) (as at 14 November 2026). From 1 January 2027, the Act of 4 September 2026 (Dz.U. 2026 poz. 1270) replaces the list in Annex 15 and adds Annexes 16 and 17 to the VAT Act. [23]
The NIP in E-invoicing (KSeF)
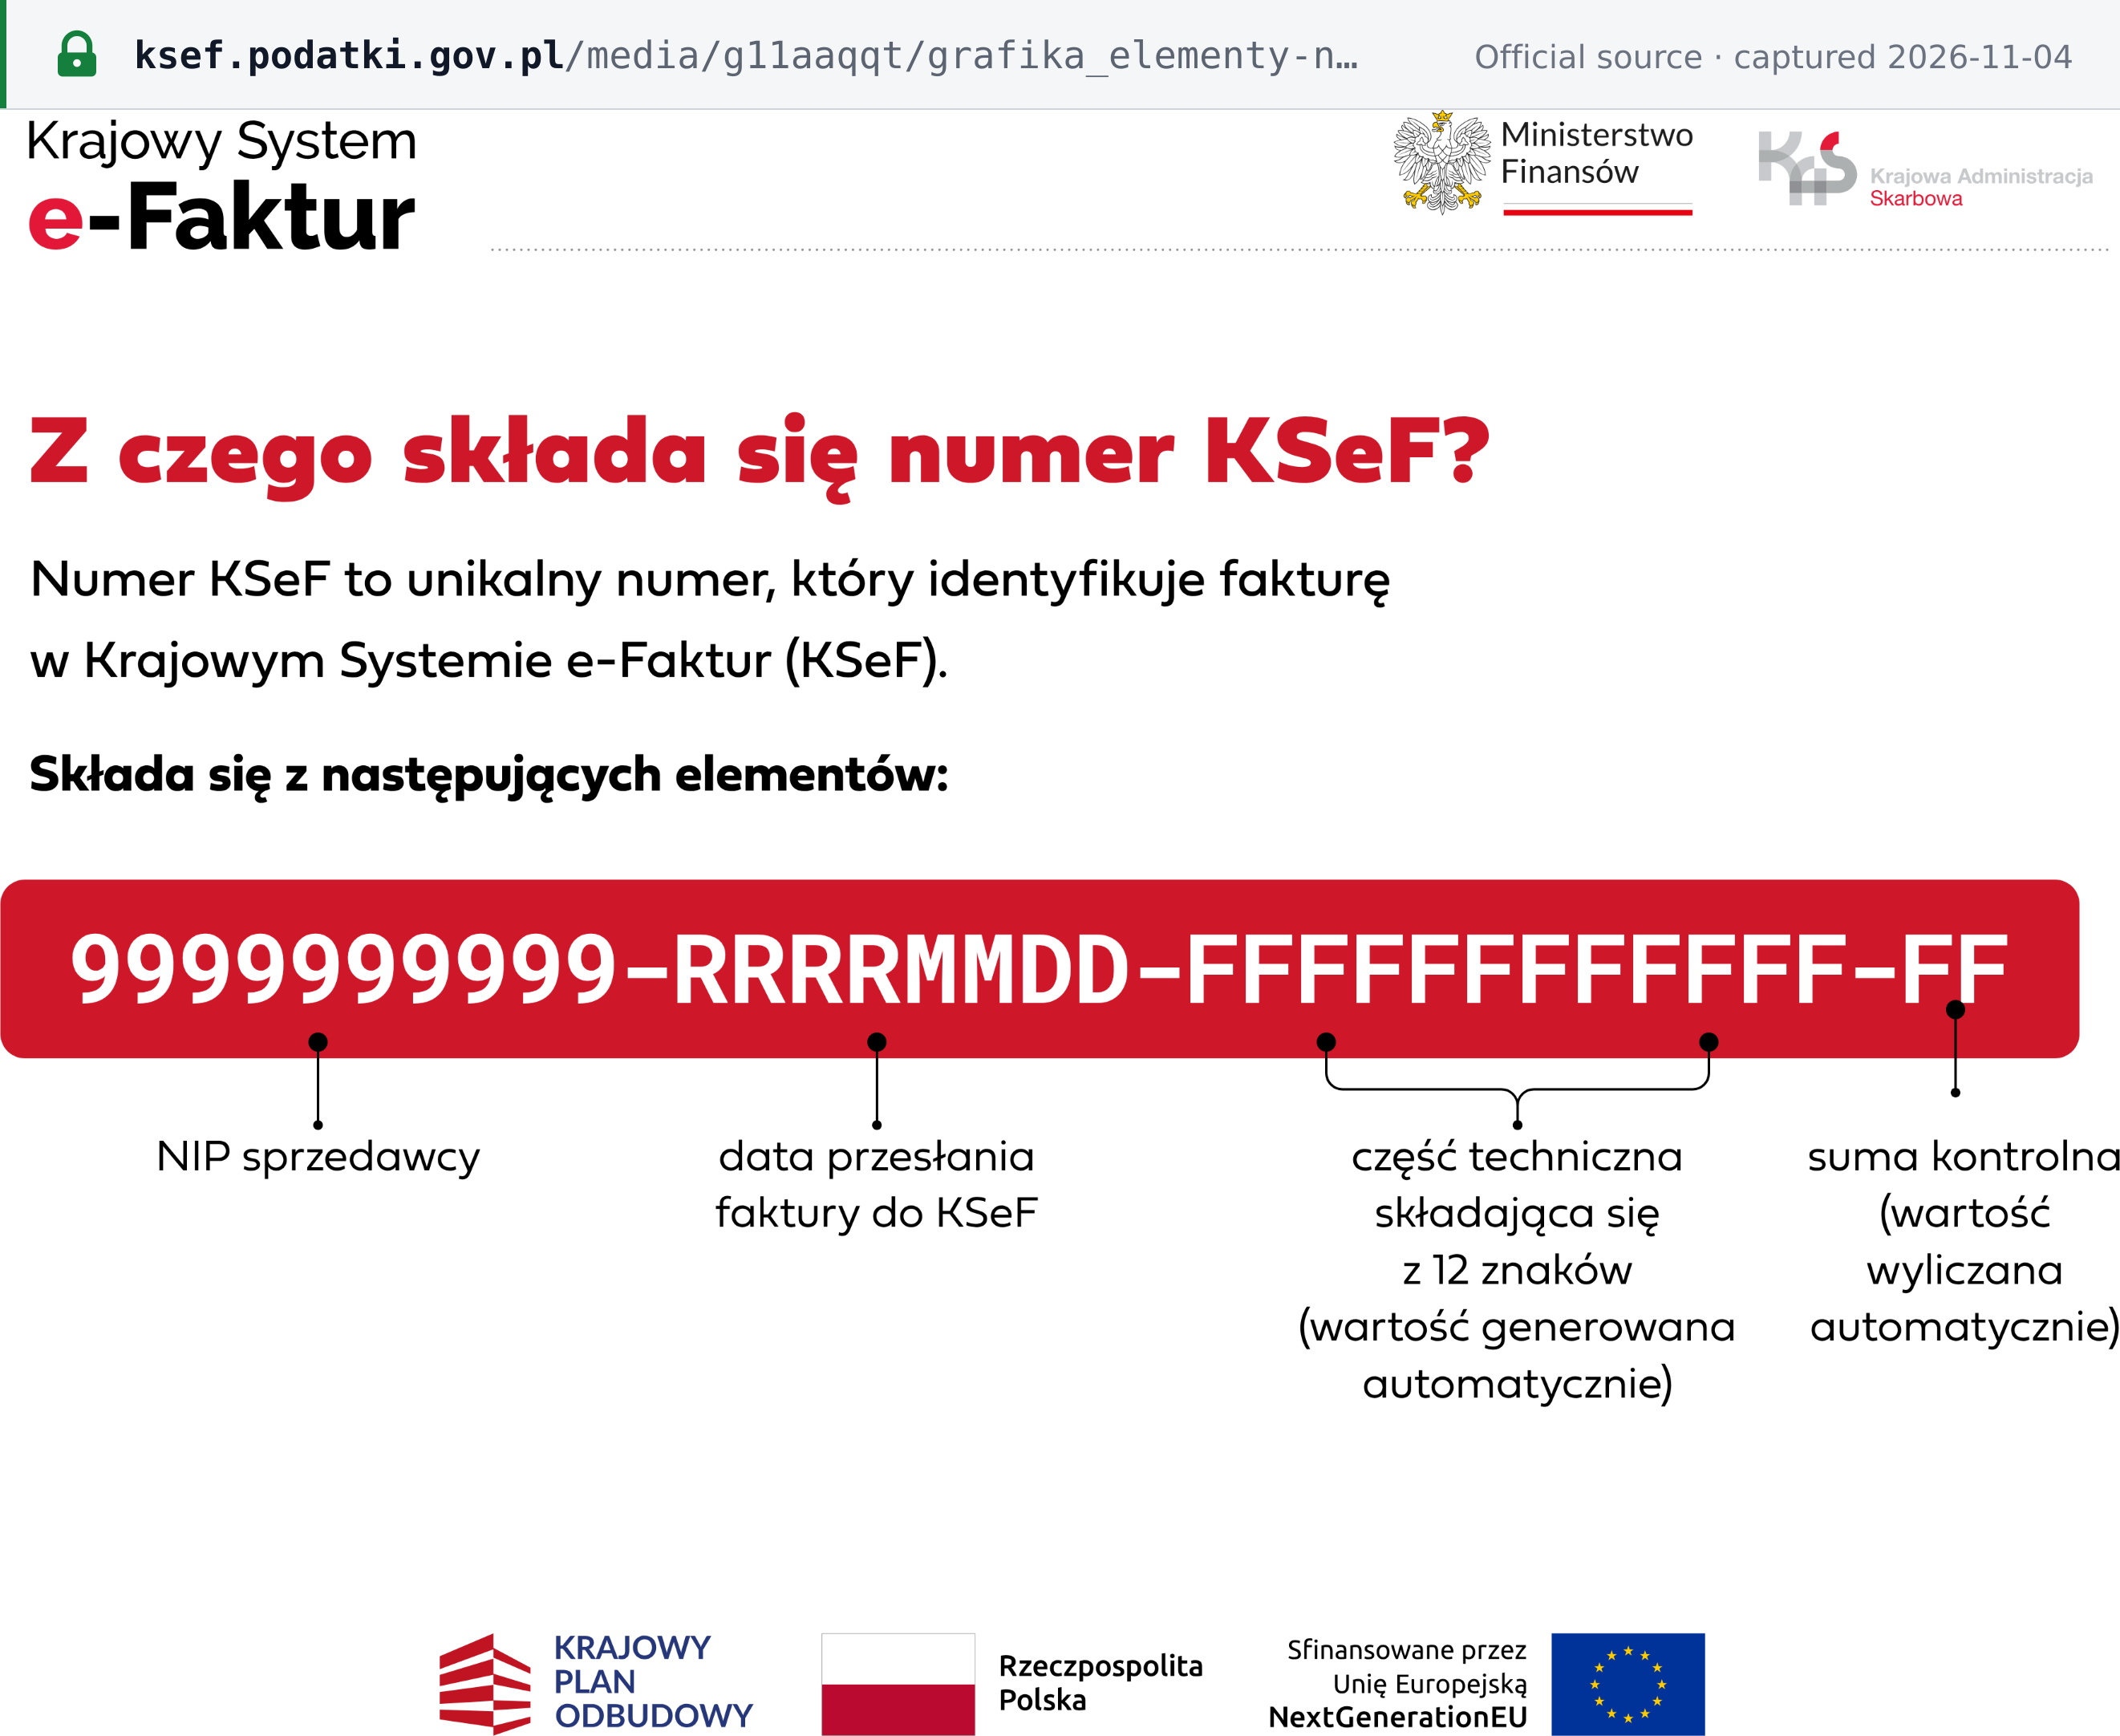
Poland's National e-Invoice System (Krajowy System e-Faktur, KSeF) identifies every invoice by a KSeF number that begins with the seller's NIP, followed by the date the invoice was sent to KSeF, a technical part and a checksum. [22]
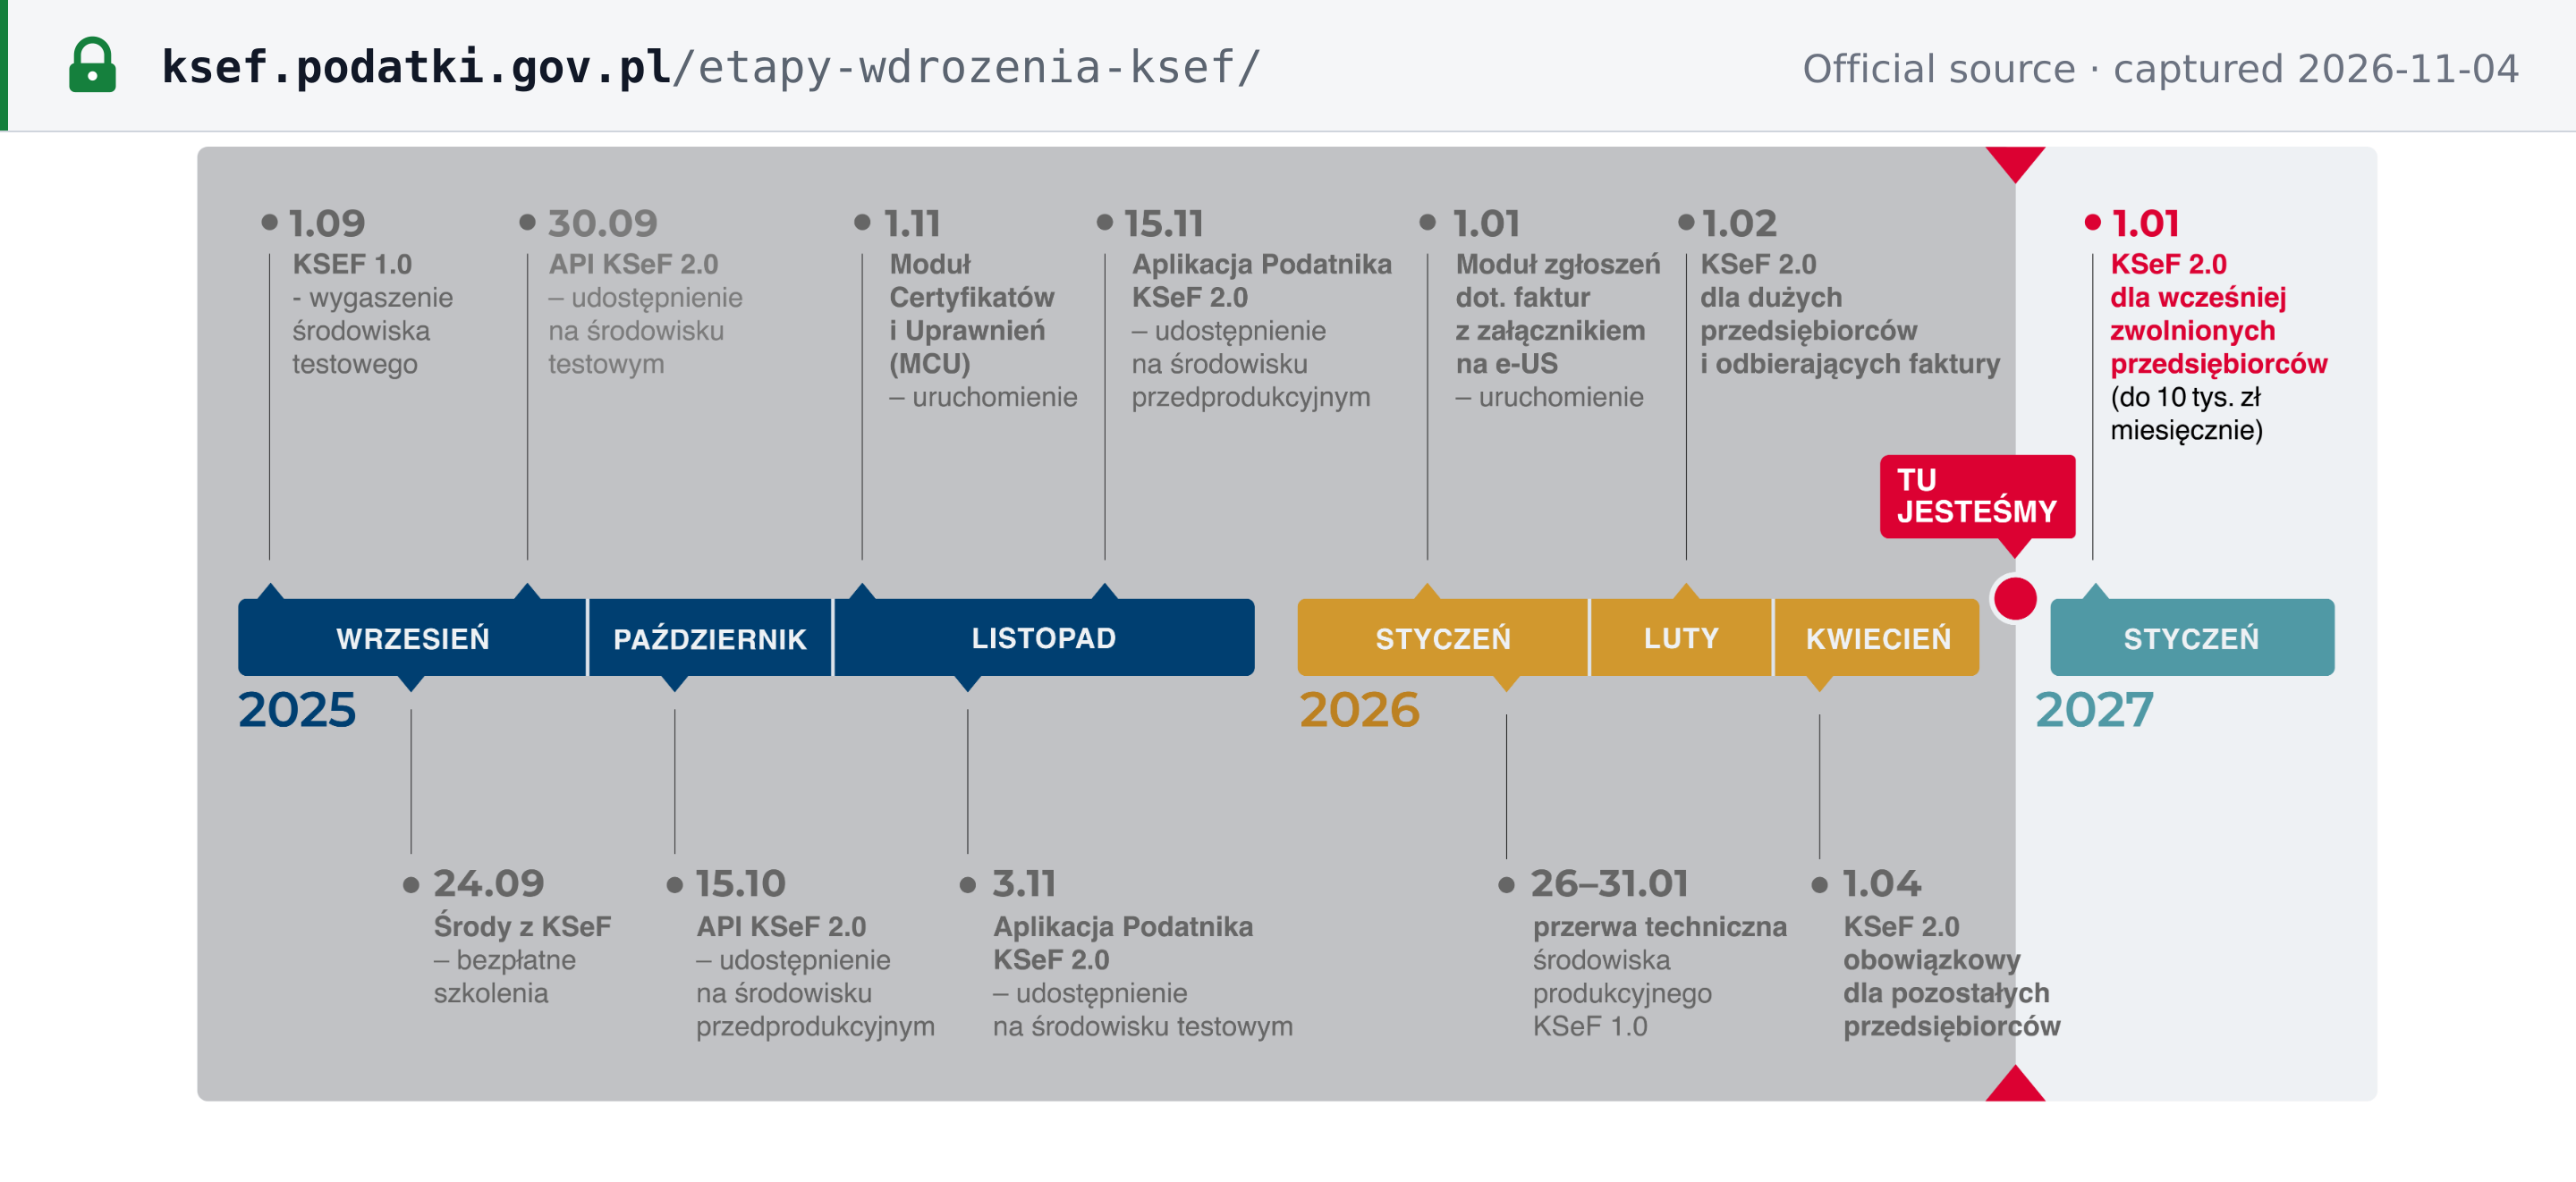
Status as at 14 November 2026, per the Ministry of Finance: [17] [16]
- 1 February 2026 — issuing structured invoices in KSeF became mandatory for taxpayers whose 2024 sales, including VAT, exceeded PLN 200 million; receiving invoices through KSeF became mandatory for everyone.
- 1 April 2026 — issuing became mandatory for all other taxpayers.
- Until 31 December 2026 — a taxpayer whose sales documented by invoices do not exceed PLN 10,000 gross in a month need not issue in KSeF; invoices issued from cash registers, and receipts showing the buyer's NIP that count as simplified invoices (up to PLN 450 or EUR 100), may also stay outside KSeF.
- Out of scope — sellers with no seat or fixed establishment in Poland.
- 1 January 2027 — KSeF becomes mandatory for the businesses previously exempted.
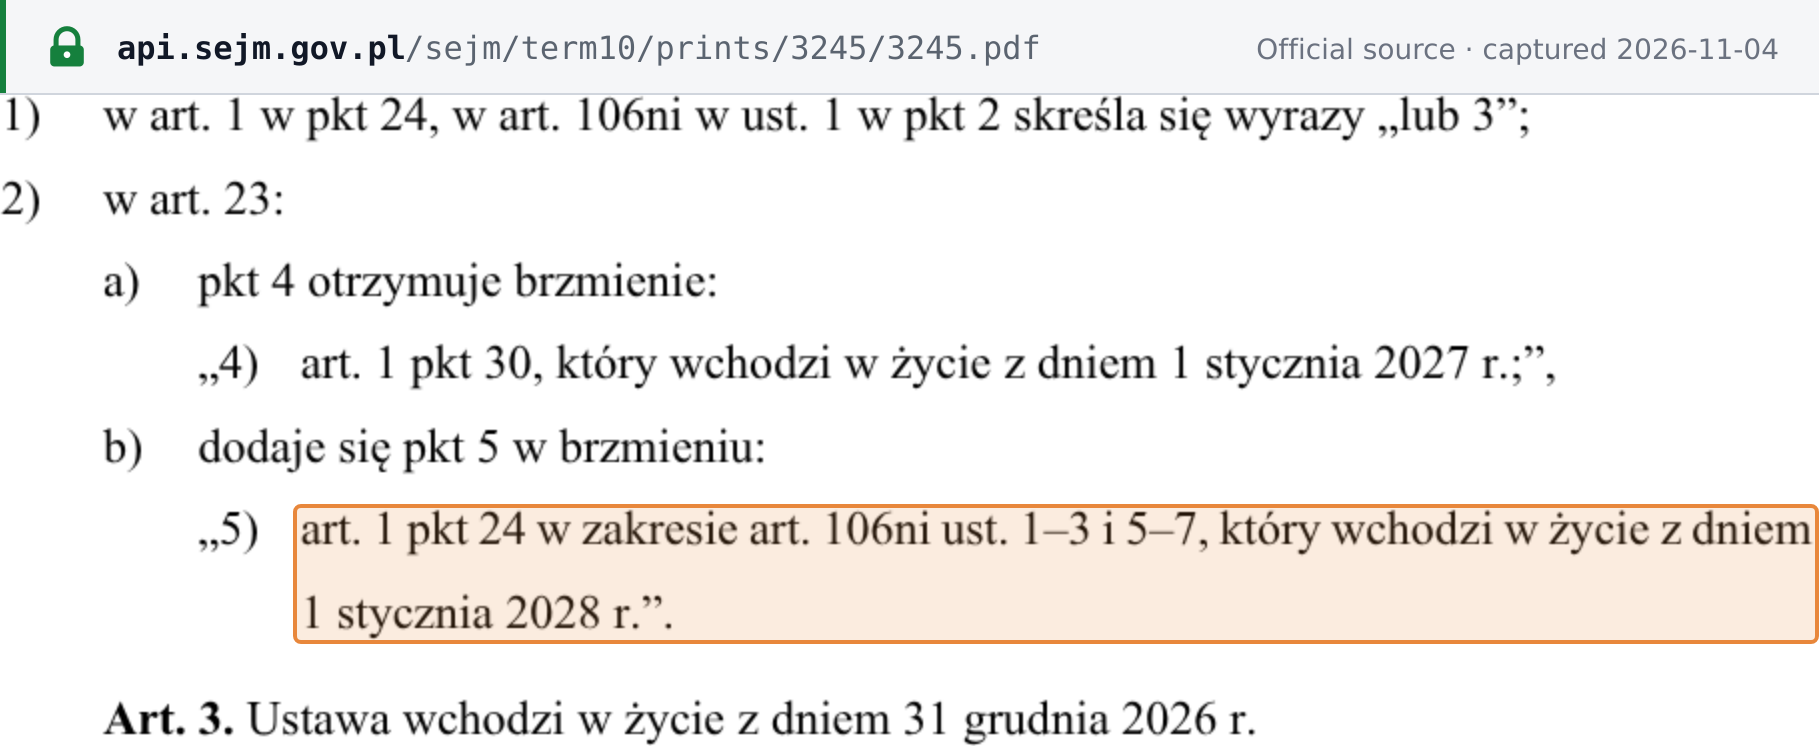
Penalties. Under the law in force on 14 November 2026, the article 106ni penalties for invoices issued outside KSeF apply from 1 January 2027. Government bill druk 3245, which would move them to 1 January 2028, passed its third reading in the Sejm on 6 November 2026 (437 for, 1 against, 1 abstention). It still needs the Senate and the President's signature, so it is a bill, not law. [18] [19] For the full mandate, see the Poland KSeF e-invoicing guide.
How to Verify a Polish Tax ID
| Lookup | What it confirms |
|---|---|
White List (Wykaz podatników VAT, the "Biała lista"), Head of KAS — search at wykazpodatnikowvat.mf.gov.pl | Whether a NIP is registered for VAT (active or exempt), was refused registration or was deregistered; status, KRS number, address and the settlement bank accounts as they stood on any chosen day from 1 January of the fifth year before the year of the check up to the day of the check (for a check in 2026, back to 1 January 2021) (name, NIP and REGON are shown as they stand on the day of the check) |
| VIES (European Commission) | Whether a PL VAT-UE number is active for intra-EU transactions; for Polish numbers the reply includes the name and address (as at 14 November 2026). It does not show domestic-only VAT status |
| GUS REGON database (BIR) | That an entity exists in the REGON register, searched by REGON, NIP or KRS; free BIR1 API with a key from GUS |
| CEIDG company search (biznes.gov.pl) | A sole trader's CEIDG entry, including NIP and REGON |
KRS — Ministry of Justice search at wyszukiwarka-krs.ms.gov.pl, or the Ministry of Justice open KRS API, which returns the current extract for a KRS number at https://api-krs.ms.gov.pl/api/krs/OdpisAktualny/<KRS>?rejestr=P&format=json | A company's KRS entry and the NIP disclosed in it, which is the official confirmation that the NIP was assigned (registration act article 8b(3)) |
The White List. Article 96b of the VAT Act requires the Head of KAS to keep the list electronically and publish it so that anyone can check, including automatically, whether an entity was on it on any chosen day from 1 January of the fifth year before the year of the check onwards; it is updated once a day on working days. Since 27 November 2025 it can also be reached through the CEIDG and business-portal systems (article 96b(9)). [6]
Why it matters for payments above PLN 15,000. For a B2B transaction worth more than PLN 15,000 (article 19 of the Entrepreneurs' Law), paying an active VAT payer's invoice by transfer to a bank account that is not on the White List on the day you order the transfer has two consequences: [11] [20] [21]
- the payment is not a tax-deductible cost to that extent (article 15d(1)(2) of the CIT Act; for individuals running a business, the same rule is in article 22p(1)(2) of the PIT Act, with the same 7-day-notice and split-payment exceptions in article 22p(4) points 1 and 3 [24]); and
- the payer becomes jointly and severally liable for the supplier's VAT arrears on that supply (article 117ba § 1 of the Tax Ordinance).
Neither consequence applies if the payer notifies its own tax office within 7 days of ordering the first transfer to that account, or pays by split payment (article 117ba § 3 points 2 and 4 of the Tax Ordinance; article 15d(4) points 1 and 3 of the CIT Act). [20] [21]
Validate the format first. The Lookuptax Poland NIP validator checks the format and check digit of a NIP before you run a registry lookup.
Frequently Asked Questions
I am a foreigner employed in Poland — do I put my PESEL or a NIP on my tax return?
Your PESEL, if you only earn employment or contract income. The registration act makes the PESEL the tax identifier of individuals who are not VAT-registered and do not run a business, and the business portal names income from an employment contract, a contract of mandate or a contract for specific work as examples. You need a NIP instead if you run a registered business, are VAT-registered, or are a tax or contribution payer, for example because you employ staff. The PESEL is requested by the municipality when you register your permanent or temporary residence; EU, EFTA and Swiss citizens must register no later than the 30th day after arriving at that address. Others who must hold a PESEL apply for one.
I am opening a sole proprietorship (JDG). Do I file form NIP-7?
No. A sole trader registering a business in CEIDG files the NIP identification application inside the CEIDG entry application, which is forwarded to the tax office automatically, and the NIP shown in CEIDG is the official confirmation that it was assigned. Form NIP-7 is for individuals who are not entrepreneurs or are not entered in CEIDG — for example VAT-registered individuals, tax or contribution payers, persons without a PESEL, and unregistered-activity persons who are VAT-registered or use a cash register. VAT registration is a separate form, VAT-R.
I do small-scale unregistered activity (działalność nierejestrowa). Which number do I use?
Your PESEL, unless you are a registered VAT taxpayer or keep sales records on a cash register — then you must use a NIP (article 3(1a) of the registration act, in force since 13 July 2025). Unregistered activity is activity whose revenue due does not exceed 225% of the minimum wage in any quarter, by a person who has not run a business in the last 60 months. It is not entered in CEIDG or in the REGON register.
Does a foreign company with no Polish establishment need a Polish NIP and VAT registration before its first sale in Poland?
Yes, if it makes taxable supplies in Poland. The PLN 240,000 exemption (from 1 January 2026, previously PLN 200,000) applies only to businesses with their seat in Poland, so a non-established business must register before its first taxable activity, whatever the value. It files the VAT-R registration with the Head of the Second Tax Office Warszawa-Śródmieście, and a business established outside the EU that must register as an active VAT payer must appoint a fiscal representative. A business seated in another EU member state with EU-wide turnover up to EUR 100,000 can instead use the EU SME scheme with an EX number from its home state, without registering in Poland.
Which number do I give an EU customer: my NIP or PL plus the NIP?
For intra-EU supplies and acquisitions of goods, cross-border B2B services, import of services and call-off stock movements, a business registered as an EU VAT taxpayer must use its NIP preceded by PL, for example PL2234567895. You get the VAT-UE registration by notifying it on form VAT-R before the first intra-EU transaction, and the tax office confirms it on VAT-5UE. A business registered only for domestic VAT has no VAT-UE registration, so its PL number will fail a VIES check.
My supplier's bank account is not on the White List. What happens if I pay an invoice above PLN 15,000?
For a B2B transaction worth more than PLN 15,000, paying an active VAT payer's invoice to an account that is not on the White List on the day you order the transfer means the payment is not a tax-deductible cost to that extent, and you become jointly and severally liable for the supplier's VAT arrears on that supply. Notifying your own tax office within 7 days of ordering the first transfer to that account, or paying through split payment, avoids both consequences. Check the account on the White List on the day you order the transfer.
My invoice exceeds PLN 15,000 and includes Annex 15 goods. What must I do?
Split payment is mandatory: the buyer must pay using the split-payment mechanism when the invoice total exceeds PLN 15,000 and covers goods or services listed in Annex 15 of the VAT Act, and the transfer message must state the supplier's tax identification number and, for a KSeF invoice, its KSeF number. The seller must mark the invoice „mechanizm podzielonej płatności”. If the annotation is missing, the tax office can set an additional liability of 30% of the VAT on those goods or services for the seller; if the buyer pays outside split payment, the same 30% applies to the buyer. Each sanction has exceptions, for example where the payment was in fact made by split payment.
When must I issue invoices in KSeF, and when do the penalties start?
Issuing in KSeF has been mandatory since 1 February 2026 for taxpayers whose 2024 sales including VAT exceeded PLN 200 million, and since 1 April 2026 for everyone else; receiving through KSeF has been mandatory for all since 1 February 2026. Until 31 December 2026, taxpayers whose invoiced sales do not exceed PLN 10,000 gross in a month, and invoices issued from cash registers, may stay outside KSeF. Under current law the penalties for invoices issued outside KSeF apply from 1 January 2027. Bill druk 3245, passed by the Sejm on 6 November 2026, would move them to 1 January 2028, but it still needs the Senate and the President's signature, so it is not law as at 14 November 2026. Every KSeF number begins with the seller's NIP.
Related Resources
- Poland VAT guide — rates, registration, invoicing and filing
- Poland KSeF e-invoicing guide
- How to verify an EU VAT number in VIES
- Poland tax changes — chronology
- Lookuptax Poland NIP validator
- EU VAT SME scheme explainer
- Worldwide VAT, GST and sales tax registration thresholds
- E-invoicing status and networks by country
- Worldwide directory of VAT and tax ID names
- Germany tax ID numbers · Czechia tax ID numbers · Slovakia tax ID numbers