New Zealand TIN number guide
IRD Number
The IRD number in New Zealand is a unique identifier issued by Inland Revenue to individuals and non-individual entities like Companies, Partnerships, Trusts, and Charities. Typically utilized throughout a customer's lifetime, except in cases of bankruptcy, this number is crucial for both residents and non-residents engaging with New Zealand's tax system. It serves as a necessity for various taxes, encompassing Income Tax, Goods and Services Tax, as well as Employer taxes like Pay as You Earn and Fringe Benefit Tax. Additionally, the IRD number is essential for social policy entitlements managed by Inland Revenue, covering areas such as Working for Families Tax Credits, Child Support, Student Loans, Paid Parental Leave, and KiwiSaver.
IRD Number Format
The format of the IRD number in New Zealand varies based on its age, appearing as either an eight or nine-digit number, structured as 99-999-999 or 999-999-999. This identifier comprises a base number of seven or eight digits, accompanied by a trailing check digit. An emerging trend involves appending a 0 to eight-digit numbers to extend their length to nine digits, exemplified as 099-999-999.
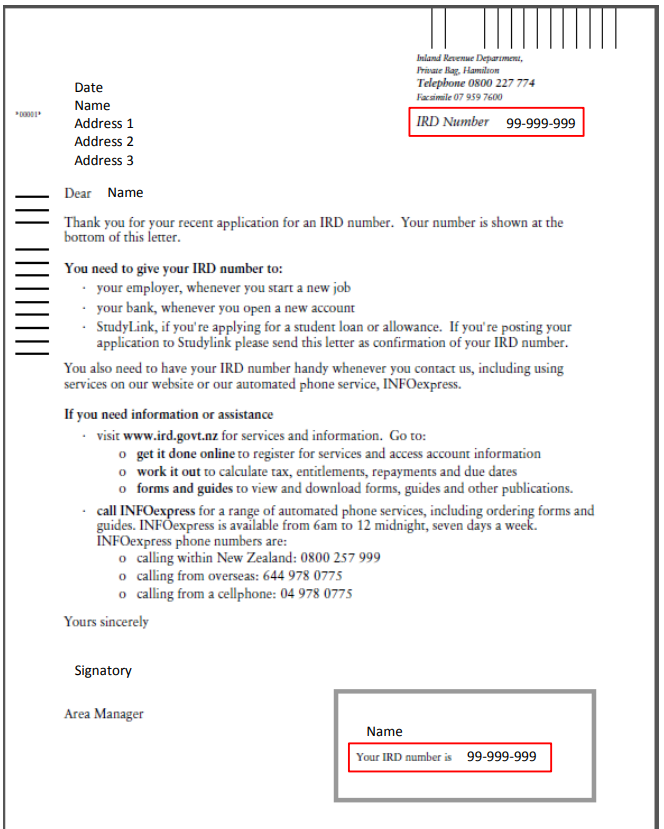 |
| IRD number on initial notification |
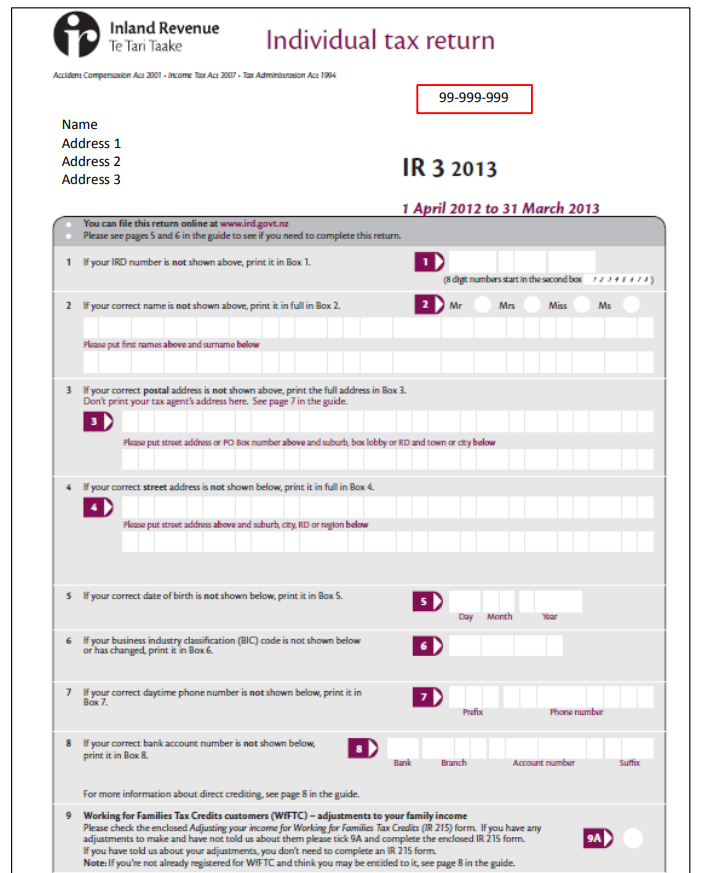 |
| IRD number on Tax return |
How Lookuptax can help you in VAT validation?
Lookuptax VAT validation revolutionizes VAT number validation with its robust platform, empowering businesses to seamlessly verify VAT numbers across over 100 countries. Our cutting-edge technology ensures accurate and efficient validation, reducing errors and enhancing compliance.
Recent changes
- 2026-09-10 (proposed) — The Taxation (Annual Rates for 2026-27, FBT Simplification, Foreign Investment Funds, and Remedial Measures) Bill, introduced on 10 September 2026, proposes new rules allowing GST deductions for goods and services acquired before GST registration once they start being used to make taxable supplies (from 1 April 2027), an option for non-residents making zero-rated services supplies to non-residents not to register for GST, and clarification that the Commissioner may move a registered person who no longer qualifies for six-monthly filing, and has not applied to change, to a two-month taxable period. The Bill is not yet law. (Inland Revenue, Tax Policy) — see event
Frequently Asked Questions
I just arrived in New Zealand on a Working Holiday visa — the online IRD number application asks for a NZ bank account, but my bank wants an IRD number first. How do I break this deadlock?
New arrivals who used a visa granted by Immigration New Zealand (INZ) can apply online and authorise Inland Revenue to verify their identity directly with INZ — no bank account or physical ID documents are needed for that pathway. [1] The catch is timing: you must apply before the "final arrival date" printed on your visa. If that window has passed, use the non-new-arrival form (IR595), take certified identification to an AA Driver Licensing Agent within 20 working days, and you can still start work immediately using your application reference number. Without an IRD number at all, your employer is legally required to deduct tax at the 45% no-notification rate. [2]
As an offshore non-resident selling a New Zealand residential property, will tax automatically be withheld at settlement — even if I make no profit?
Yes. Residential land withholding tax (RLWT) is deducted at settlement by the conveyancer if you are an "offshore RLWT person" and the property was purchased on or after 1 October 2015. [3] The withheld amount is the lesser of 10% of the purchase price or 33% of the estimated gain — so even a break-even sale triggers a cash hold. You are an offshore RLWT person if you are not a NZ citizen or permanent resident, or if you are a NZ citizen who has been outside NZ continuously for three or more years. To avoid the withholding, you must obtain a certificate of exemption from Inland Revenue before settlement. Any over-withheld tax is refunded after you file a return. [4]
What is the difference between RWT and NRWT, and what happens if a New Zealand payer deducts the wrong one from payments to a foreign investor?
Resident withholding tax (RWT) applies to interest and dividends paid to New Zealand tax residents, while non-resident withholding tax (NRWT) applies to the same income types — plus royalties — when paid to non-residents. [5] Applying RWT to a non-resident is an error: the payer must instead deduct NRWT at the domestic rate (15% on interest and royalties; 30% on unfranked dividends, reducible to 15% for fully imputed dividends) or a lower treaty rate if a double tax agreement applies. [6] Payers of NRWT on interest can alternatively register as an approved issuer and pay a 2% approved issuer levy (AIL) instead, which reduces the NRWT obligation to nil for arm's-length lending. Mis-classifying the regime exposes the payer to back-tax, interest, and penalties.
My SaaS company is based overseas and earns revenue from New Zealand customers. Do I need a New Zealand IRD number and GST registration, and can I reclaim GST on local costs?
Offshore businesses supplying "remote services" (including SaaS, software, streaming, and digital downloads) to New Zealand-resident consumers must register for GST once their taxable New Zealand supplies exceed NZD 60,000 in any 12-month period. [7] Registration requires an IRD number, which you apply for using form IR742. Inland Revenue provides a simplified "pay-only" non-resident registration through myIR — you register, file quarterly returns at 15% GST, and remit the tax. Under this registration you generally account only for GST on your sales; Inland Revenue asks businesses that expect to have New Zealand expenses — which they may want to claim GST on — to contact it before registering. No fiscal representative is required. You do not need to register if you only supply GST-registered New Zealand businesses for their business use; the business customer self-assesses GST under the reverse charge only if its taxable use of the services will be less than 95% of total use. [7] [8]
Proposed, not yet law: the Taxation (Annual Rates for 2026-27, FBT Simplification, Foreign Investment Funds, and Remedial Measures) Bill, introduced on 10 September 2026, proposes that non-residents making zero-rated services supplies to non-residents may choose not to register for GST (clause 170, from the day after Royal assent), and would clarify that the Commissioner may move a registered person who no longer qualifies for six-monthly filing, and has not applied to change, to a two-month taxable period (clause 153). The current rules described above continue to apply unless and until the Bill is enacted. [11]
I left New Zealand two years ago and rented out my house. My accountant says I may still be a NZ tax resident. How can that be?
New Zealand's tax residency rules have two independent tests — either one is sufficient. The 183-day test is widely known, but the "permanent place of abode" (PPOA) test can keep you resident indefinitely even after you leave. [9] If you retain a property in New Zealand that you have a continuous and substantial association with — which includes renting it out short-term or leaving it available for family — Inland Revenue can find that you have a PPOA regardless of how long you have been abroad. As a NZ tax resident you are taxable on worldwide income, including foreign employment income and offshore investment fund (FIF) regime income from foreign shares. Inland Revenue historically applied an unwritten three-year rule, but this is not legally binding. You should apply for a formal residency determination (form IR886) if your status is in doubt. [10]