Croatia OIB (Tax ID) Guide — Format, Validation & Compliance
Osobni identifikacijski broj (OIB) — Croatia's Personal Identification Number
The Republic of Croatia introduced the Osobni identifikacijski broj (OIB) as the single universal identifier across the entire Croatian public administration system. The Ministry of Finance — Tax Administration (Porezna uprava) issues and manages all OIBs, and every interaction with Croatian state bodies requires one: tax filing, property registration, employment, company formation, and banking.
OIBs are assigned to:
- Croatian citizens — automatically at birth or upon naturalisation
- Legal entities — upon incorporation or registration of a branch in Croatia
- Foreign individuals and companies — when a legal basis for monitoring arises in Croatia (property acquisition, VAT registration, employment, or other regulated activity)
OIB Format
The OIB consists of 11 digits. The first 10 digits are randomly assigned; the 11th is a control digit computed using the ISO 7064 Mod 11,10 algorithm (also called "Modul 11.10"). The calculation iterates through each digit: initialize r = 10; for each digit d, compute r = ((r % 10 || 10) × 2) mod 11; then r = (11 − r) mod 10 gives the check digit. A result of 10 is invalid, so the sequence is reassigned.
Example: HR99999999999 (the HR prefix is used exclusively for the PDV-ID / VAT number; the raw OIB carries no prefix).
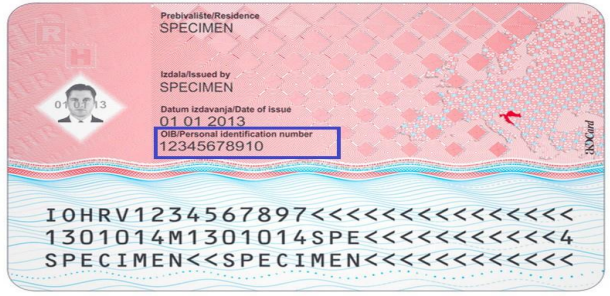 |
| OIB — 11-digit format |
OIB vs PDV-ID (VAT number)
The OIB and the Croatian VAT number (PDV-ID) are derived from the same underlying number but are not interchangeable:
| Identifier | Format | Used For |
|---|---|---|
| OIB | 11 digits (e.g., 12345678901) | All domestic tax, legal, and administrative purposes |
| PDV-ID | HR + 11 digits (e.g., HR12345678901) | EU intra-community VAT transactions; verifiable on EU VIES |
Only VAT-registered entities hold a PDV-ID. Every entity with a PDV-ID also has an OIB, but not every OIB holder is VAT-registered.
Matični broj subjekta (MBS)
The Matični broj subjekta (MBS) is Croatia's court company registration number, not a tax identifier. It is issued by the Commercial Court Register and used in legal and corporate filings. For invoicing and tax reporting purposes, always use the OIB (or PDV-ID for EU VAT transactions) — not the MBS.
Croatia VAT (PDV) — Key Thresholds
- Standard VAT rate: 25% (reduced rates: 13% and 5%)
- Domestic registration threshold: EUR 60,000 annual turnover (raised from EUR 40,000 in 2025)
- Non-resident / foreign businesses: no minimum threshold — registration is required from the first taxable transaction in Croatia
- EU distance selling threshold: EUR 10,000 EU-wide (applies to B2C sales across all EU member states)
Foreign non-EU companies must appoint a fiscal representative who assumes joint and several liability for all Croatian VAT obligations. EU businesses may instead register directly or use the VAT One Stop Shop (OSS) scheme to avoid a Croatian VAT establishment.
Fiscalization 2.0 and B2B E-Invoicing
Croatia's Fiscalization Act (Zakon o fiskalizaciji, NN 89/25) entered into force on 1 September 2025, and its e-invoicing (eRačun) provisions apply from 1 January 2026. Key points:
- 1 January 2026: VAT-registered businesses established in Croatia (seat, residence or habitual residence) must issue and receive structured e-invoices (eRačun) in domestic B2B trade and fiscalise them with the Tax Administration (Porezna uprava); every other in-scope business must be able to receive them. The format is EN 16931 with the national CIUS-HR extension in UBL 2.1, exchanged between access points over AS4: a certified information intermediary's, the business's own tested access point, or Porezna uprava's free MIKROeRAČUN app. It is not a single government platform. B2G e-invoicing is older: contracting authorities have had to receive e-invoices since 1 December 2018 and suppliers to issue them since 1 July 2019 (NN 94/2018, Art 16). [14]
- 1 January 2027: non-VAT-registered income-tax (self-employed) and profit-tax payers, and non-VAT public bodies, established in Croatia must also issue eRačun (Art 38(1) points 2–3).
- Certificates, not a qualified signature: fiscalisation messages are signed with a digital certificate whose structure contains the OIB of the person authorised to submit them (Act Art 48(6)). The Act does not require a qualified electronic signature on the invoice.
- Retention: six years from the end of the year of issue, for eRačun that have been fiscalised (Act Art 35(1)).
Fines for a legal person that does not issue, receive or fiscalise an eRačun are EUR 3,980 to EUR 66,360 (Act Art 71); fiscalising late or incorrectly is an Art 72 offence at EUR 2,650 to EUR 66,360, rising to EUR 3,500 to EUR 80,000 for a repeat offence. In the eRačun system the OIB identifies the parties: the fiscalisation certificate carries the OIB of the person submitting (Art 48(6)); rejection reports carry both the issuer's and the recipient's OIB (Art 52(2)); and payment reports carry the issuer's OIB (Art 53(3)). A recipient's address in the AMS directory may be its OIB or another identifier allowed by the EU standard (Art 2(1)(13)). For phases, scope, format and the full penalty table, see our Croatia e-invoicing guide. [13]
How Lookuptax can help you?
Lookuptax VAT validation revolutionizes VAT number validation with its robust platform, empowering businesses to seamlessly verify VAT numbers across over 100 countries. Our cutting-edge technology ensures accurate and efficient validation, reducing errors and enhancing compliance.
Frequently Asked Questions
Can a foreign company obtain an OIB and Croatian PDV-ID without a physical office in Croatia?
Yes, but the application requires documented justification. A non-resident legal entity is assigned an OIB when there is a legal basis for monitoring it in Croatia — typically VAT registration, property acquisition, or branch registration. To register for PDV (VAT), you must simultaneously submit Form P-PDV (VAT registration) and the OIB assignment application to Porezna uprava. Non-EU businesses must appoint a fiscal representative who assumes joint and several liability for all Croatian VAT obligations. EU businesses may register directly or use the One Stop Shop (OSS) scheme to avoid establishing a Croatian presence. The process takes 2–4 weeks when documentation is complete. [1] [2]
I need an OIB to open a Croatian bank account, but banks ask for an account number on OIB application forms — how do I break the loop?
This is a genuine documented catch-22 that expats regularly encounter. The resolution: the OIB does not require a bank account number on the application — that confusion arises from some bank onboarding forms asking for an OIB before the account is opened. In practice, you can apply for an OIB at any Porezna uprava office with only a valid passport and a stated reason (e.g., "opening a bank account" is itself a valid reason). OIB is issued free of charge, typically within one working day at the office. Once you have your OIB, approach the bank — Croatian banks classify OIB-holders without a residence permit as non-resident account holders, which involves additional documentation but is permitted. [3] [4]
My Croatian business partner is withholding 15% from my invoice — can I reduce or eliminate it?
Croatia applies a 15% withholding tax on royalties, interest, and certain services (market research, tax consulting, auditing) paid to non-resident entities. If your country has a Double Taxation Treaty (DTT) with Croatia, you may qualify for a reduced or zero rate — but relief is not automatic. The Croatian payer must obtain a tax residency certificate from your home country's tax authority and submit it to Porezna uprava before the payment is made. If no certificate is filed in time, the full 15% is withheld and you must file a refund claim afterwards. Payments to entities in EU-listed non-cooperative jurisdictions attract a higher 25% rate. Always confirm treaty eligibility before invoicing to avoid post-payment refund delays that typically take 3–6 months. [5] [6]
Does Croatia's Fiscalization 2.0 mandate require an OIB-linked digital certificate, and what are the penalties for non-compliance?
Yes, in the sense that fiscalisation messages must be signed with a digital certificate whose structure contains the OIB of the person authorised to submit them (Fiscalization Act, NN 89/25, Art 48(6)); a qualified electronic signature on the invoice itself is not required. Mandatory B2B e-invoicing has applied since 1 January 2026 to VAT-registered businesses established in Croatia, which issue, receive and fiscalise eRačun (foreign businesses registered only for Croatian VAT are outside it); taxpayers outside the VAT system must issue them from 1 January 2027. Not issuing, receiving or fiscalising an eRačun is fined at EUR 3,980 to EUR 66,360 for a legal person (Art 71); fiscalising late or incorrectly at EUR 2,650 to EUR 66,360, or EUR 3,500 to EUR 80,000 for a repeat offence (Art 72). Fiscalised eRačun must be kept for six years from the end of the year of issue (Art 35(1)). [13]
I hold a Croatian Digital Nomad Visa and exceeded 183 days — am I now a Croatian tax resident?
Not automatically. The Digital Nomad Visa (a temporary residence permit under the Croatian Aliens Act, not a visa in the legal sense) is specifically structured so that holders remain non-tax-residents even beyond the 183-day threshold, provided their primary economic ties remain in their home country. Income from employers or clients not registered in Croatia is fully exempt from Croatian income tax during the permit period. However, if you register habitual residence or establish an economic centre of interest in Croatia — for example, by opening a Croatian-registered sole proprietorship — Porezna uprava can reclassify you as a tax resident and apply income tax rates of 15–23.6% on income up to EUR 50,400 and 25–35.4% above that threshold. Passive income (dividends, rental income from Croatian property) is taxable regardless of nomad visa status. [9] [10]
Why does my OIB pass the ISO 7064 Mod 11,10 checksum but still get rejected by a partner's system?
Passing the checksum confirms only that the number is mathematically well-formed — it does not verify the OIB is assigned to a live, active entity. Common rejection causes: (1) the OIB belongs to a dissolved or struck-off entity; (2) systems confuse the raw 11-digit OIB with the HR-prefixed PDV-ID — the OIB itself never carries the "HR" country prefix; (3) the partner's system expects the PDV-ID for VAT purposes but receives the bare OIB; (4) name or address data in the partner's registry mismatches the Tax Administration record. To confirm an OIB is genuinely active and linked to the correct entity, use the Porezna uprava public registry. For VAT-registered entities, verify the HR-prefixed PDV-ID through the EU VIES system. [11] [12]
Related Resources
- E-invoicing in Croatia (Fiskalizacija 2.0) — eRačun phases, format, intermediaries and penalties
- EU VIES System — Verify Croatian PDV-ID numbers
- VAT One Stop Shop (OSS) — Avoid Croatian VAT registration for EU digital sellers
- Import One Stop Shop (IOSS) — Distance selling into Croatia from outside the EU
- VAT Thresholds by Country — 2025 Overview
- Hungary TIN Guide