Ecuador RUC Tax ID Number — Format, Validation & Compliance Guide
Registro Unico de Contribuyentes (RUC)
Ecuador's tax identification number is the Registro Único de Contribuyentes (RUC), administered by the Servicio de Rentas Internas (SRI). The RUC identifies every taxpayer — individuals, private companies, and public entities — for all tax-related obligations, from IVA filings to income-tax withholding remittances. It is also listed in the worldwide directory of VAT and tax ID names.
Registration is mandatory for any national or foreigner conducting economic activity in Ecuador, whether permanently or occasionally, as well as for holders of assets generating taxable income. Public entities, armed forces units, cooperatives, and foundations must also register regardless of profit intent. Foreign companies holding immovable property in Ecuador must obtain a RUC even if that property generates no taxable income — a requirement enforced at the point of notarial transfer.
One exemption applies: international organisations, embassies, consulates, and commercial offices of countries with diplomatic or consular ties to Ecuador are not obliged to register, but may do so voluntarily.
RUC Format
All RUC numbers are 13 digits: SRI's e-invoicing specification defines the RUC field as 13 numeric digits. [19]
For individuals the RUC is built on the national identity card. Under article 5 of the Ley del RUC, for individuals who do not form a sole-proprietor company, "el número de identificación tributaria estará dado por el número de la cédula de identidad y/o ciudadanía" (the tax identification number is the identity card number). [16]
SRI states that the RUC numbers it issues to private companies, public bodies and foreign individuals without a cédula "no tienen una validación con un algoritmo específico" (have no validation with a specific algorithm), because no regulation or SRI requirement provides for one. A format check therefore cannot confirm that a company or public-entity RUC is genuine. [11]
To check a RUC's format, use the Ecuador RUC validator.
RUC Registration Process
Registration is made with the SRI through SRI en Línea (srienlinea.sri.gob.ec) or at the offices the SRI designates, preferably those for the taxpayer's tax domicile (Ley del RUC art. 4). The number is issued when the application is filed (art. 7), and new taxpayers must register within 30 days of incorporation or the real start of their activities (art. 4). A company registers its branches and agencies when it registers the head office (art. 6). [16]
Automatic suspension. For taxpayers in the general regime, the SRI may suspend a RUC on its own initiative when all of these conditions are met: no economic activity recorded in the 12 months before the suspension, with no reports of transactions in SRI's databases; no update to the registration in those 12 months; no pending tax-refund claims for that period; and no authorisation requested to issue electronic or printed sales documents or, where requested, no valid documents or no electronic sales documents issued. It may also suspend a RUC when the taxpayer has no valid e-mail address or online password on file, or lacks the permits its activity requires (Resolution NAC-DGERCGC21-00000011, art. 1). [17] Since Resolution NAC-DGERCGC25-00000018 (signed 6 August 2025), it may also suspend the RUC of a taxpayer obliged to report to the Financial and Economic Analysis Unit (UAFE) that does not obtain its UAFE registration code within 30 business days of opening or updating its RUC. [18]
Reactivation. The suspension lasts until the taxpayer reports the continuation or restart of its activities, or updates its information, through the service channels the SRI has enabled for the purpose (Resolution NAC-DGERCGC21-00000011, art. 2). After a UAFE suspension, the taxpayer must provide the UAFE's certificate of compliance. [17] [18]
Electronic Invoicing (Facturación Electrónica)
Electronic invoicing has been mandatory since 29 November 2022 for every taxpayer obliged to invoice, except negocios populares. [20] No authorisation needs to be requested: "el SRI autoriza de oficio a todos los contribuyentes que tengan esta obligación" (the SRI authorises every taxpayer with this obligation automatically). [11] Each document is an XML file signed with an electronic signature and sent to the SRI, which authorises it or not; a document rejected because of inconsistent information is corrected and sent again with the same clave de acceso and sequential number. [19] Since 1 January 2026 every electronic document must be transmitted to the SRI at the moment it is generated.
The most frequent rejection causes are: inactive or suspended RUC, establishment listed as closed, missing electronic agreement acceptance, invalid digital signature, or a sequential invoice number already registered in the SRI database. Failure to deliver a valid comprobante de venta carries penalties of up to 30 basic salaries under the LRTI.
New RUC category for e-invoicing software providers (from August 2026)
SRI Resolution NAC-DGERCGC26-00000027, signed by the Director General on 27 July 2026, creates a dedicated RUC registration category for providers of e-invoicing software or services domiciled or permanently established in Ecuador: developers/owners of e-invoicing source code register economic-activity code J62021002, and resellers of third-party-built e-invoicing systems register code J62021003. Affected providers had to register or update this activity in their RUC by 27 August 2026 (30 days from the resolution's publication). Separately, from 26 September 2026 (60 calendar days from publication) every issuer of electronic vouchers must add the 13-digit RUC of its e-invoicing system or service provider to the additional-information field of every electronic voucher. The resolution also provided for the SRI to publish the list of registered providers on its website from October 2026. [10]
RIMPE — Simplified Regime
The Régimen Simplificado para Emprendedores y Negocios Populares (RIMPE) divides small taxpayers into two sub-categories with distinct obligations.
| Category | Annual gross income | IVA rate charged | IVA returns | Invoice type |
|---|---|---|---|---|
| Negocio Popular | Individuals only, up to USD 20,000 | 0% | None | Pre-printed nota de venta or electronic |
| Emprendedor | Every other RIMPE taxpayer, individual or company (regime limit USD 300,000) | The applicable IVA rate | Every six months, filed and paid together | Factura (electronic) |
Negocios populares file no IVA returns, and RIMPE Emprendedores file and pay IVA every six months rather than monthly. [1] [3] RIMPE taxpayers declare and pay income tax once a year, by the dates the SRI sets by resolution (RLRTI art. 230). [14]
IVA Rate
IVA has been 15% since 1 April 2024; it was 12% until 31 March 2024. For the rates, the 13–15% legal band and the decrees behind them, see the Ecuador IVA guide. [13]
ID Card
For individuals, the RUC is built on the identity card (cédula) number (Ley del RUC art. 5; see RUC Format). [16]
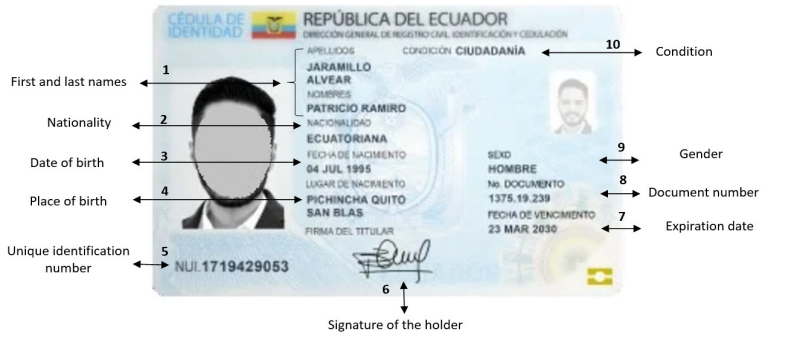 |
| ID card Front side |
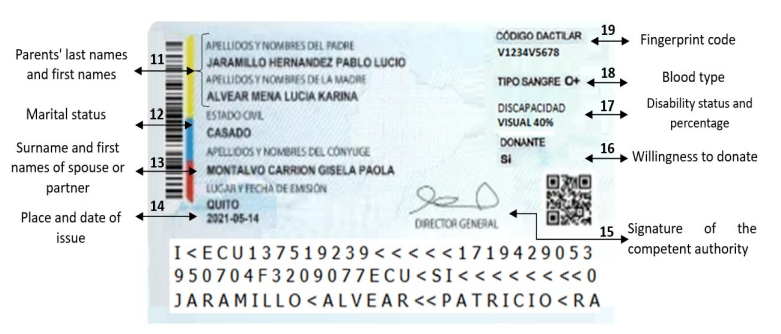 |
| ID card back side |
Frequently Asked Questions
Does my RIMPE category (Negocio Popular vs Emprendedor) change my IVA and invoicing obligations?
Yes, and the difference is significant. Negocio Popular applies only to natural persons with gross annual income up to USD 20,000: their sales are taxed at 0% IVA, they file no IVA returns, and they may issue pre-printed notas de venta instead of electronic invoices. Every other RIMPE taxpayer, individual or company, is an Emprendedor: they charge the applicable IVA rate and issue facturas, but they file and pay IVA every six months rather than monthly. If you file a return late, the fine is 3% of the tax due per month or part-month, capped at 100% of that tax; late-payment interest is charged separately. [1] [3] [13] [14]
Ecuador's IVA rose from 12% to 15% — is the 15% rate now permanent, and what triggered the change?
Ecuador's IVA was 12% until 31 March 2024 and has been 15% since 1 April 2024. The Ley Orgánica para Enfrentar el Conflicto Armado Interno (March 2024) set the base rate at 13% and lets the President set the general rate anywhere between 13% and 15% by executive decree. Executive Decree 198 set 15% from 1 April 2024, and Executive Decree 470, published 10 December 2024, kept 15% for 2025. In 2026 the SRI applies 15% as the rate in force, for example in Circular NAC-DGECCGC26-00000005 of 2 April 2026. The rate is not fixed: any change within the band needs a new decree. For the full rate rules, see the Ecuador IVA guide. [13] [3] [12]
Why does my SRI tax payment deadline vary each month, and how does the 9th digit of my RUC determine it?
Ecuador's SRI staggers filing deadlines by taxpayer. The 9th digit of your RUC determines the monthly due date for IVA declarations, income-tax withholdings (retenciones), and other periodic obligations: digit 1 = 10th of the following month, digit 2 = 12th, digit 3 = 14th, digit 4 = 16th, digit 5 = 18th, digit 6 = 20th, digit 7 = 22nd, digit 8 = 24th, digit 9 = 26th, digit 0 = 28th. Filing late costs a fine of 3% of the tax due per month or part-month, capped at 100% of that tax; for IVA it is calculated on the amount payable after input credit, and you add it to the return yourself. Late-payment interest is a separate charge, at an annual rate equal to the Central Bank of Ecuador's 90-day reference rate. [14] [13]
As a foreign SaaS provider selling to Ecuadorian consumers, must I register for IVA, and does selling only B2B exempt me?
No, registration is voluntary for non-resident suppliers of digital services. If you register in the RUC, you charge 15% IVA, file a monthly return by the 15th of the following month and pay in US dollars; registering does not by itself create a permanent establishment. If you do not register, the IVA is still collected, and the payment route decides how, whether your customer is a business or a consumer: when the customer pays by card or through another payment intermediary, the intermediary withholds 100% of the IVA; when a buyer pays you directly, the buyer issues a liquidación de compra and withholds 100% of the IVA itself. The Ecuador IVA guide explains both routes. [15] [13] [14]
My SRI electronic invoice was rejected as "RECHAZADO" — what are the most common causes and how do I fix it?
The SRI rejects electronic comprobantes in real time for several reasons: the issuer's RUC is inactive or suspended; the issuer's establishment is listed as closed in the RUC; the taxpayer has not accepted the electronic agreement (convenio de facturación electrónica) in SRIenLinea; the digital signature certificate is expired or invalid; or the access key (clave de acceso) on the XML has already been registered. When a document is rejected because of inconsistent information, the issuer corrects the inconsistency and sends it to the SRI again using the same clave de acceso and the same sequential number, as SRI's technical specification requires. Since 1 January 2026 every electronic document must be transmitted at the moment it is generated. The original rejected document carries no fiscal value and must not be delivered to the customer as proof of transaction. Verify your RUC status at srienlinea.sri.gob.ec before assuming the problem is technical. [8] [19]
The SRI suspended my RUC automatically — can I reactivate it online, and what triggers automatic suspension?
The SRI can suspend a RUC on its own initiative (suspensión de oficio). For taxpayers in the general regime this requires all of the following: no economic activity recorded in the 12 months before the suspension and no reports of transactions in SRI's databases; no update to the RUC in those 12 months; no pending tax-refund claims for that period; and no authorisation requested to issue electronic or printed sales documents or, where requested, no valid documents or no electronic sales documents issued. The SRI can also suspend a RUC when the taxpayer has no valid e-mail address or online password on file, lacks the permits its activity requires, or, since Resolution NAC-DGERCGC25-00000018 of August 2025, is obliged to report to the UAFE and has not obtained its UAFE registration code within 30 business days of opening or updating its RUC. To lift the suspension, you report the continuation or restart of your activities, or update your information, through the service channels the SRI has enabled for the purpose; after a UAFE suspension you must also provide the UAFE's certificate of compliance. [17] [18]
I sell an e-invoicing platform in Ecuador — do I now need a special RUC entry, and does my client need to cite it?
Yes, on both counts. Under SRI Resolution NAC-DGERCGC26-00000027 (signed 27 July 2026), any developer/owner of e-invoicing source code domiciled or permanently established in Ecuador must register RUC economic-activity code J62021002, and any reseller of a third-party-built e-invoicing system must register code J62021003 — the deadline to register or update was 27 August 2026. Since 26 September 2026, your client's obligation runs the other way: every taxpayer issuing electronic vouchers must include the 13-digit RUC of its e-invoicing system or service provider in the additional-information field of every voucher. The resolution also provided for the SRI to publish a list of registered providers on its website from October 2026. This is a new RUC data point, separate from the format and category rules covered above; the registration deadline has passed, so check that your RUC shows the correct code. [10]
Recent changes
- 2026-08-27 — SRI Resolution NAC-DGERCGC26-00000027 (signed 27 July 2026, published in the Fifth Supplement of Registro Oficial No. 335, 28 July 2026) required e-invoicing software developers (CIIU J62021002) and resellers (CIIU J62021003) domiciled in Ecuador to register or update this activity in their RUC; from 26 September 2026 the provider's RUC number must also appear on every electronic voucher issued through their system. See New RUC category for e-invoicing software providers. (Registro Oficial) — see event
Related Resources
- Ecuador IVA guide — IVA rates, registration, filing by RUC digit, withholding, e-invoicing and penalties
- Peru Tax ID Guide — Peru's RUC uses the same name and a similar 11-digit structure under SUNAT
- Colombia Tax ID Guide — NIT format, factura electrónica rules, and PES obligations for digital providers
- Chile Tax ID Guide — RUT with mod-11 check digit and SII e-invoicing (DTE) requirements
- How to verify a CUIT in Argentina — Step-by-step verification of Argentina's tax ID
- Countries and VAT Names — Global directory of tax ID names including Ecuador's RUC
How Lookuptax can help you?
Lookuptax VAT validation revolutionizes VAT number validation with its robust platform, empowering businesses to seamlessly verify VAT numbers across over 100 countries. Our cutting-edge technology ensures accurate and efficient validation, reducing errors and enhancing compliance.