Hungary withdraws the 5% VAT rate on new homes from 1 January 2027, with transitional protection to 2030
This page records one dated change. For the rules in Hungary as they stand today, see the Hungary guide →
- Jurisdiction
- Hungary
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Effective
- 1 January 2027
- Authority
- NAV (Nemzeti Adó- és Vámhivatal / National Tax and Customs Administration of Hungary)
- Systems
- ERP, Invoicing, Tax engine
- Verified
- Fetched from official source · high confidence
Developers and buyers of new homes in Hungary: flats up to 150 m2 and houses up to 300 m2.
Flag new-home sales and advances that straddle 1 Jan 2027. Apply 27% unless a qualifying permit/notification condition (or brownfield-area status) keeps 5% through 31 Dec 2030.
ERPInvoicingTax engine
Under Act LV of 2024, Hungary's 5% reduced VAT rate for sales of new homes applies until 31 December 2026 and is withdrawn from 1 January 2027. It covers flats up to 150 m2 in multi-dwelling buildings outside brownfield action areas and single-dwelling houses up to 300 m2. The transitional rule in section 371 of the VAT Act (in force from 1 January 2027) keeps 5% for advances received and supplies made from 1 January 2027 to 31 December 2030 if any one of three conditions is met: the building permit became final by 31 December 2026; a simple notification was filed by 30 September 2024; or a simple notification under the Hungarian architecture act was acknowledged by 31 December 2026. Otherwise 27% applies. New flats in designated brownfield (rozsdaövezeti) action areas stay at 5% after 1 January 2027.
What changed in detail
Under Act LV of 2024, Hungary’s 5% reduced VAT rate for sales of new homes applies until 31 December 2026 and is withdrawn from 1 January 2027. It covers flats of up to 150 m2 in multi-dwelling buildings outside brownfield action areas, and single-dwelling houses of up to 300 m2.
A transitional rule in section 371 of the VAT Act, in force from 1 January 2027, keeps the 5% rate for advances received and supplies made from 1 January 2027 to 31 December 2030 if any one of three conditions is met: the building permit became final by 31 December 2026; a simple notification was filed by 30 September 2024; or a simple notification under the Hungarian architecture act was acknowledged by 31 December 2026. Otherwise 27% applies.
New flats in designated brownfield (rozsdaövezeti) action areas stay at 5% after 1 January 2027.
What it means
The rate depends on the permit or notification history of the project, not only on the date of sale. Developers should establish, project by project, which of the three transitional conditions is met and keep the evidence, because a project that meets none moves to 27% for supplies and advances from 1 January 2027. Brownfield-area flats are outside the withdrawal, so the area designation is a separate check.
Proof
Az 5 százalékos, kedvezményes adómérték 2026. december 31-éig alkalmazandó, vagyis azt 2027. január 1-jével kivezetikThe 5 per cent preferential tax rate is to be applied until 31 December 2026, that is, it is phased out as of 1 January 2027.
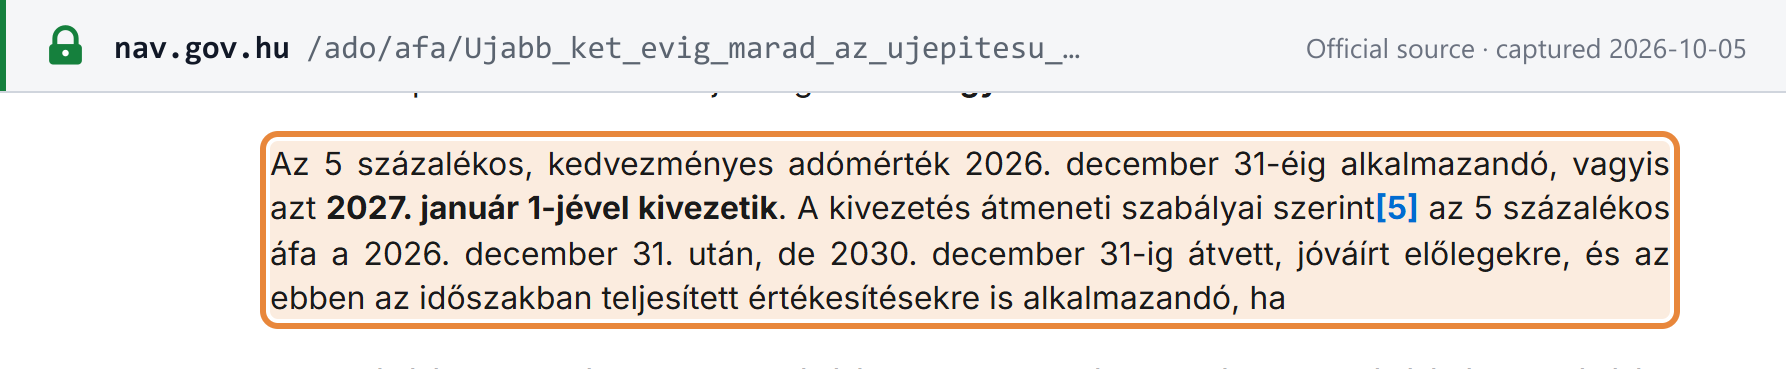 Source snapshot of the official page. Open full size ↗