Latvia VAT guidelines
| FACTSHEET | |
|---|---|
| Country code | LV |
| Tax name | Value Added Tax — Pievienotās vērtības nodoklis (PVN) |
| Tax Authority | State Revenue Service — Valsts ieņēmumu dienests (VID) |
Overview
Latvia levies Value Added Tax — in Latvian pievienotās vērtības nodoklis (PVN) — under the Value Added Tax Law (Pievienotās vērtības nodokļa likums, the PVN likums), adopted on 29 November 2012 and in force since 1 January 2013. It was last amended by the law of 3 December 2025, in force from 1 January 2026. [1]
Authority. The tax is administered by the State Revenue Service (Valsts ieņēmumu dienests, VID), which also collects import VAT through its National Customs Board. VID describes VAT as "a consumption tax, which is included in the price of goods and services and is paid by the final consumer." [2]
Currency. All amounts in this guide are in euros (EUR). An invoice may be issued in any currency, but the VAT payable must be stated in euros (PVN likums s.129(5)). [1]
Tax period. The VAT period is a calendar month or a calendar quarter, depending on turnover and activity (s.115; see Filing and payment). "Kalendāra gada taksācijas periodu summa veido taksācijas gadu" — the sum of the calendar year's tax periods forms the taxable year (s.115(9)). [1]
Layering. VAT is a single national tax. The PVN likums is one national act administered by VID, and it provides for no regional or municipal VAT. [1]
For Latvia's tax identifiers in detail, see Lookuptax's Latvia TIN and PVN number guide. For a neighbouring Baltic system, see the Lithuania VAT guide.
Registration
Who should register
A taxable person — anyone independently carrying on an economic activity (s.3(1)) — registers in VID's VAT register before it: [1]
- makes taxable supplies in Latvia;
- receives services in Latvia whose place of supply is set by the B2B general rule (s.19(1)); or
- supplies B2B services whose place of supply is another member state and for which the customer is liable for the VAT.
"Nodokļa maksātājs reģistrējas Valsts ieņēmumu dienesta pievienotās vērtības nodokļa maksātāju reģistrā, pirms tas: 1) veic ar nodokli apliekamos darījumus; …" (PVN likums s.55(1))
(A taxable person registers in the VID VAT register before it: 1) makes taxable transactions; …)
The registration threshold below is framed as a right not to register, not as the trigger for liability.
Registration threshold
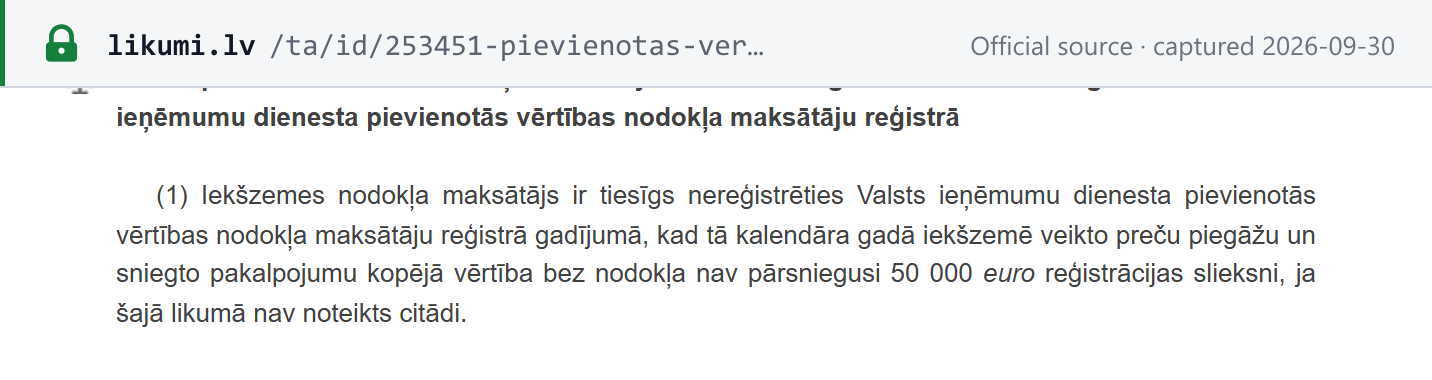
A business established in Latvia may stay off the register while the total value, excluding VAT, of the goods and services it supplies in Latvia in a calendar year does not exceed EUR 50,000 (s.59(1), as worded since 1 January 2025 by the law of 12 December 2024). [1]
"Iekšzemes nodokļa maksātājs ir tiesīgs nereģistrēties … gadījumā, kad tā kalendāra gadā iekšzemē veikto preču piegāžu un sniegto pakalpojumu kopējā vērtība bez nodokļa nav pārsniegusi 50 000 euro reģistrācijas slieksni, ja šajā likumā nav noteikts citādi." (s.59(1))
(A domestic taxable person may refrain from registering where the total value excluding VAT of goods and services it supplied domestically in the calendar year has not exceeded the EUR 50,000 registration threshold, unless this Law provides otherwise.)
- What counts. Taxable supplies plus the exempt transactions in s.52(1) points 20 (insurance), 21 (financial services), 22 (fund management), 24 (sale of real estate), 25 (residential letting) and 26 (statutory land-use fees) (s.59(2)). Sales of fixed and intangible assets, and exempt transactions that are only incidental to the business, are left out (s.59(3)). [1]
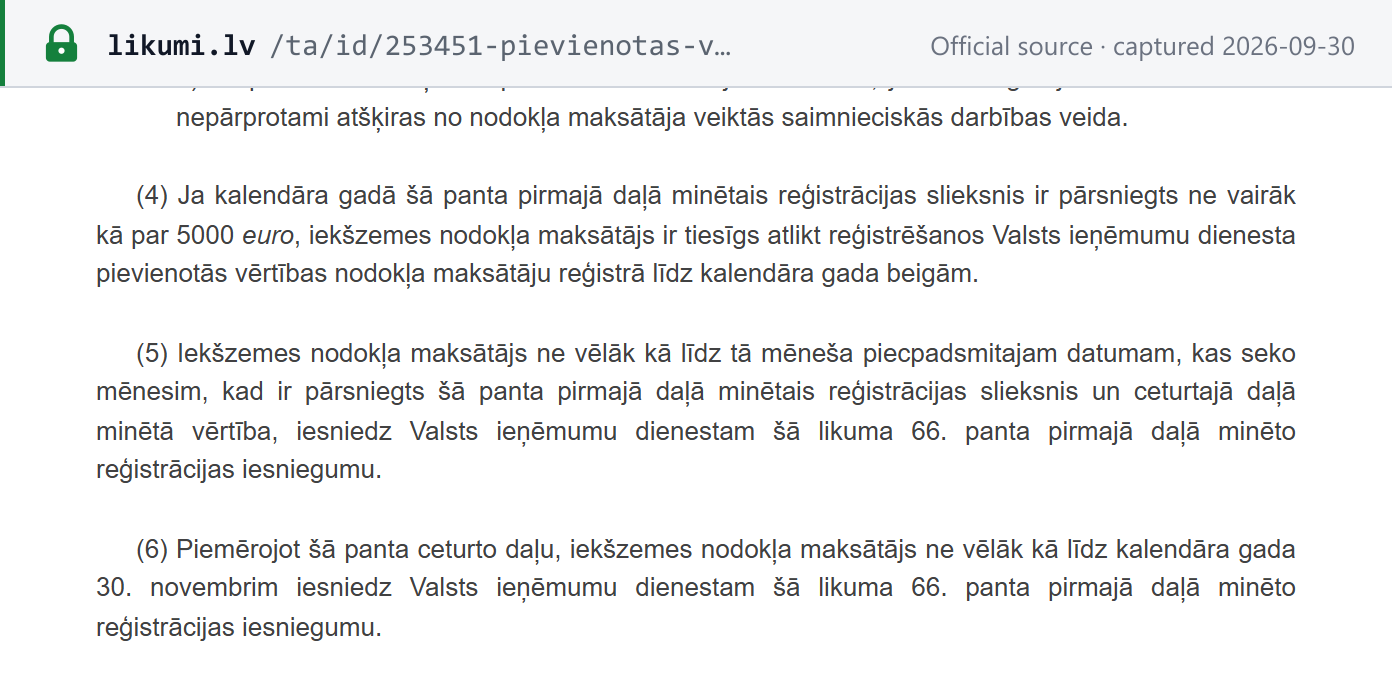
- When to apply. The registration application is due by the 15th of the month after the month in which the threshold (plus any tolerance) is exceeded (s.59(5)). A business that exceeded the threshold in the previous year loses the right not to register for the current year (s.59(10)). [1]
- EUR 5,000 tolerance. If the threshold is exceeded by no more than EUR 5,000 in the calendar year, registration may be deferred to the end of the year (s.59(4)). The application goes in by 30 November (s.59(6)) — or by 31 December where the excess arises after 30 November — and registration takes effect from 1 January of the next year (s.67(2²)). If turnover then passes EUR 55,000 before year-end, the business must tell VID by the next working day and is registered from that day (s.66(7¹)–(7²)). VAT arising in the gap is paid by 23 February (s.119(2¹)). [1]
"Ja kalendāra gadā šā panta pirmajā daļā minētais reģistrācijas slieksnis ir pārsniegts ne vairāk kā par 5000 euro, iekšzemes nodokļa maksātājs ir tiesīgs atlikt reģistrēšanos … līdz kalendāra gada beigām." (s.59(4))
(If the registration threshold is exceeded in the calendar year by no more than EUR 5,000, the domestic taxable person may defer registration until the end of the calendar year.)
Non-resident registration
The EUR 50,000 threshold is not available to every non-resident. Whether a foreign business can use it depends on where it is established: [1]
| Where the business is established | Threshold in Latvia |
|---|---|
| Outside the EU | None. s.63 gives a third-country business no right to use s.59; it registers before its first taxable supply in Latvia, unless the customer pays the VAT under the reverse charge or another s.63 exception applies (customs warehouse or free zone, exports, fiscal representative) |
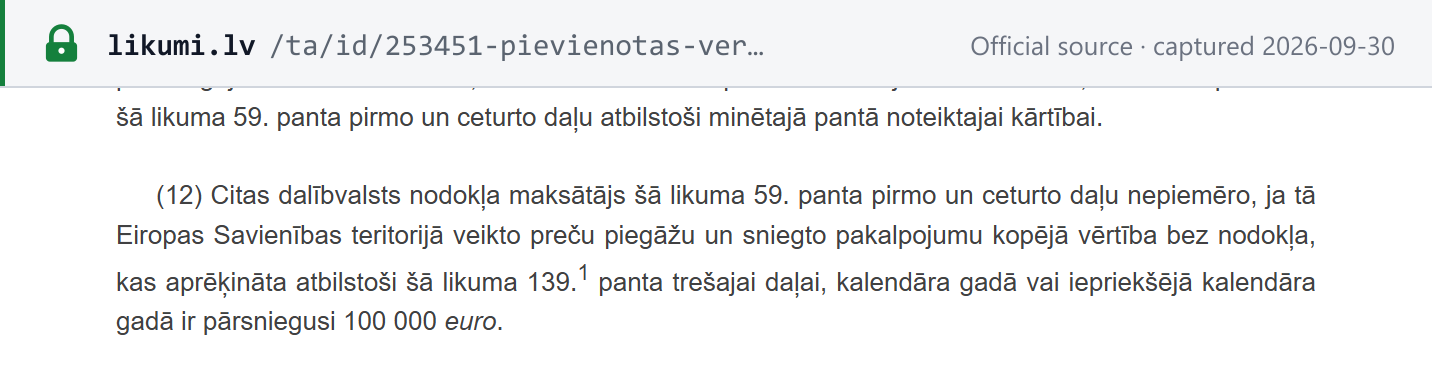
| Another EU member state | EUR 50,000 and the EUR 5,000 tolerance, since 1 January 2025 (s.61(11)) — unless its total supplies across the EU, excluding VAT, exceeded EUR 100,000 in the current or previous calendar year (s.61(12)) |
| Latvia | EUR 50,000 per calendar year (s.59(1)) |
"Citas dalībvalsts nodokļa maksātājs šā likuma 59. panta pirmo un ceturto daļu nepiemēro, ja tā Eiropas Savienības teritorijā veikto preču piegāžu un sniegto pakalpojumu kopējā vērtība bez nodokļa … kalendāra gadā vai iepriekšējā kalendāra gadā ir pārsniegusi 100 000 euro." (s.61(12))
(A taxable person of another member state does not apply section 59(1) and (4) if the total value excluding VAT of its supplies of goods and services in the EU in the calendar year or the previous calendar year has exceeded EUR 100,000.)
- No registration where the customer pays. A third-country business that makes only supplies on which the Latvian customer pays the VAT need not register: "Trešās valsts vai trešās teritorijas nodokļa maksātājs ir tiesīgs nereģistrēties …, ja tas veic tādu preču piegādi vai tādu pakalpojumu sniegšanu, par ko nodokli valsts budžetā maksā preču vai pakalpojumu saņēmējs" (s.63(1)). EU businesses have the equivalent rule in s.61(1). [1]
- Fiscal representative. Either kind of foreign business may appoint a fiscal representative instead of registering itself (s.61(7), s.63(4)). [1]
- Distance sellers and e-service providers from other member states register within 30 days of passing the EUR 10,000 EU-wide threshold, or declare through the OSS (s.60(2), (5), (7)). A seller of goods installed or assembled for a non-taxable customer registers before the supply, whatever its value (s.60(1)). [1]
VID's English VAT page lists the registration application form for non-residents. [2] The EU rules behind the EUR 100,000 test are explained in Lookuptax's EU VAT SME scheme guide.
Tax identification number
The Latvian VAT number is LV followed by 11 digits. On VID's register search the 11 digits are entered without the prefix: "PVN maksātāju var meklēt pēc precīza PVN maksātāja numura: norāda 11 ciparus, burti "LV" numura sākumā nav jānorāda" — search by the exact VAT payer number: enter 11 digits; the letters LV at the start need not be entered. [4]
| Identifier | Format |
|---|---|
| VAT number (PVN maksātāja numurs) | LV + 11 digits |
The structure of the 11 digits for individuals and companies is covered on Lookuptax's Latvia TIN and PVN number guide. To check a number, use Lookuptax's Latvia PVN number validator, VID's register search, or see how to verify an EU VAT number in VIES.
How to register
- Where. Electronically through VID's Electronic Declaration System (EDS), by e-mail with an electronic signature, or in person at a VID client centre. VID: "To register in the SRS VAT register, submit your documents: eletronically through EDS … by e-mail with an electronic signature … in person at any SRS client centre". [2]
- At incorporation. A new company can apply for VAT registration through the Register of Enterprises when it is set up (s.66(2)). [1]
- Processing time. VID decides on registration, or refuses it, within five working days of receiving the application (s.66(3)), or within five working days of receiving information it has asked for (s.66(4)). Registration takes effect when the decision is notified (s.67(2¹)). [1]
Voluntary registration
Available. The threshold is a right not to register ("ir tiesīgs nereģistrēties", s.59(1)), so a business below it may register anyway — usually to recover input VAT on its costs. A business may also register for a fixed period stated in its application (s.55(2)). [1]
Deregistration
- Grounds. VID removes a person from the register on its reasoned application, on liquidation or death, on suspension of the activity, and on its own initiative — for example where no return has been filed within 30 days of the due date, where false information was given, or where the business cannot be reached at its legal address (s.73(1)). [1]
- Final return. A removed person files its return and annexes within 20 days of removal (s.118(9)) and pays within 23 days (s.119(4)). [1]
Group registration
Available (PVN grupa, s.64). Members must be registered persons belonging to one group of companies (koncerns), or a Latvian branch of a foreign member of it, and at least one member must have made taxable supplies of at least EUR 350,000 in the previous 12 calendar months (s.64(1)(4)). There is no cap on the number of members. A VAT group files monthly (s.115(7)), and its members are jointly and severally liable (s.146(5)). [1]
Rates
| Rate | Applies to | Effective |
|---|---|---|
| 21% (standard) | All taxable supplies not given another rate | In the PVN likums since 1 January 2013 (s.41(1)(1)) [1] |
| 12% (reduced) | Medicines and medical devices, specialised infant food, domestic scheduled passenger transport, tourist accommodation, wood fuel and heat supplied to households, fresh fruit, berries and vegetables (Annex 1) | s.42; fresh produce since 1 January 2024 [1] |
| 12% (temporary) | Bread, milk, fresh poultry meat and eggs (Annex 2) | 1 July 2026 – 30 June 2027 only (transitional provision 48) [1] |
| 5% (reduced) | Books, newspapers, magazines and other periodicals, printed or electronic — since 1 January 2026 only in listed languages | s.42(5), (7) [1] |
| 0% | Exports, intra-EU supplies of goods to VAT-registered customers, international passenger transport, services linked to export and transit, supplies for ships and aircraft | ss.43–50 [3] |
"Ar nodokli apliekamiem darījumiem piemēro: 1) nodokļa standartlikmi 21 procenta apmērā …; 2) nodokļa samazināto likmi saskaņā ar šā likuma 42. pantu: a) 12 procentu apmērā, b) piecu procentu apmērā; … 3) nodokļa likmi 0 procentu apmērā …" (PVN likums s.41(1))
(Taxable transactions are subject to: 1) the standard rate of 21%; 2) the reduced rate under section 42: a) 12%, b) 5%; 3) the 0% rate.)
Standard rate — 21%. Set by s.41(1)(1) of the PVN likums, in force since 1 January 2013. A third reduced rate introduced during the pandemic (s.41(1)(2)(c)) lapsed on 1 January 2023. [1]
Reduced rate — 12%. Section 42 applies 12% to: [1]
- medicines, and medical devices for individual use by people with disabilities (s.42(1)–(2));
- specialised food for infants (s.42(3));
- domestic scheduled passenger transport and baggage (s.42(4));
- accommodation in tourist accommodation (s.42(10));
- wood fuel and heat energy sold to households (s.42(11)–(12));
- fresh fruit, berries and vegetables listed in Annex 1 — including washed, peeled, cut and packed produce, but not produce that is heat-treated or otherwise processed (frozen, salted, dried) (s.42(16)(1)). This item was 5% until 31 December 2023 and has been 12% since 1 January 2024 (amending law of 7 December 2023). [5] [6]
The same reduced rates apply to imports and intra-EU acquisitions of these goods (s.42¹).
Temporary 12% on bread, milk, poultry and eggs. The law of 3 December 2025 added s.42(16)(2) and Annex 2, but transitional provision 48 limits them: "Šā likuma 42. panta sešpadsmitās daļas 2. punkts ir piemērojams no 2026. gada 1. jūlija līdz 2027. gada 30. jūnijam" — section 42(16)(2) applies from 1 July 2026 until 30 June 2027. The Saeima: "The reduced VAT rate for food products will apply from 1 July 2026 until 30 June 2027." Annex 2 covers: [1] [8]
- bread (CN 1905) — rye, wheat, mixed-flour and gluten-free bread, including pasteurised or frozen bread and flatbreads such as pita, lavash and tortilla; not confectionery (croissants, buns, pies) or low-moisture flour products (rusks, crackers, toast, breadcrumbs, breadsticks);
- milk (CN 0401) — fresh, sterilised or pasteurised cow's, sheep's or goat's milk, including lactose-free milk; not UHT, condensed or evaporated milk;
- fresh or chilled poultry meat and offal (CN 0207) — chicken, duck, turkey, goose, guinea fowl and quail, including cut and minced meat with added salt of no more than 1%; not frozen meat;
- eggs in shell, not heat-treated (CN 0407).
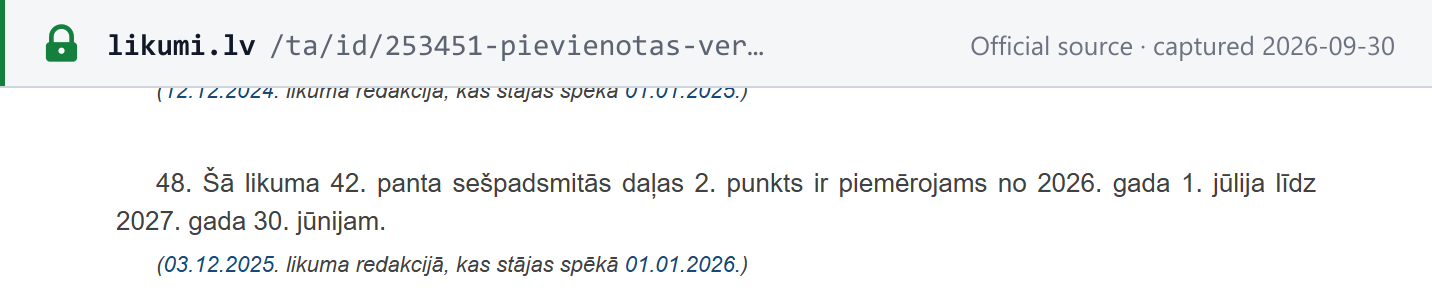
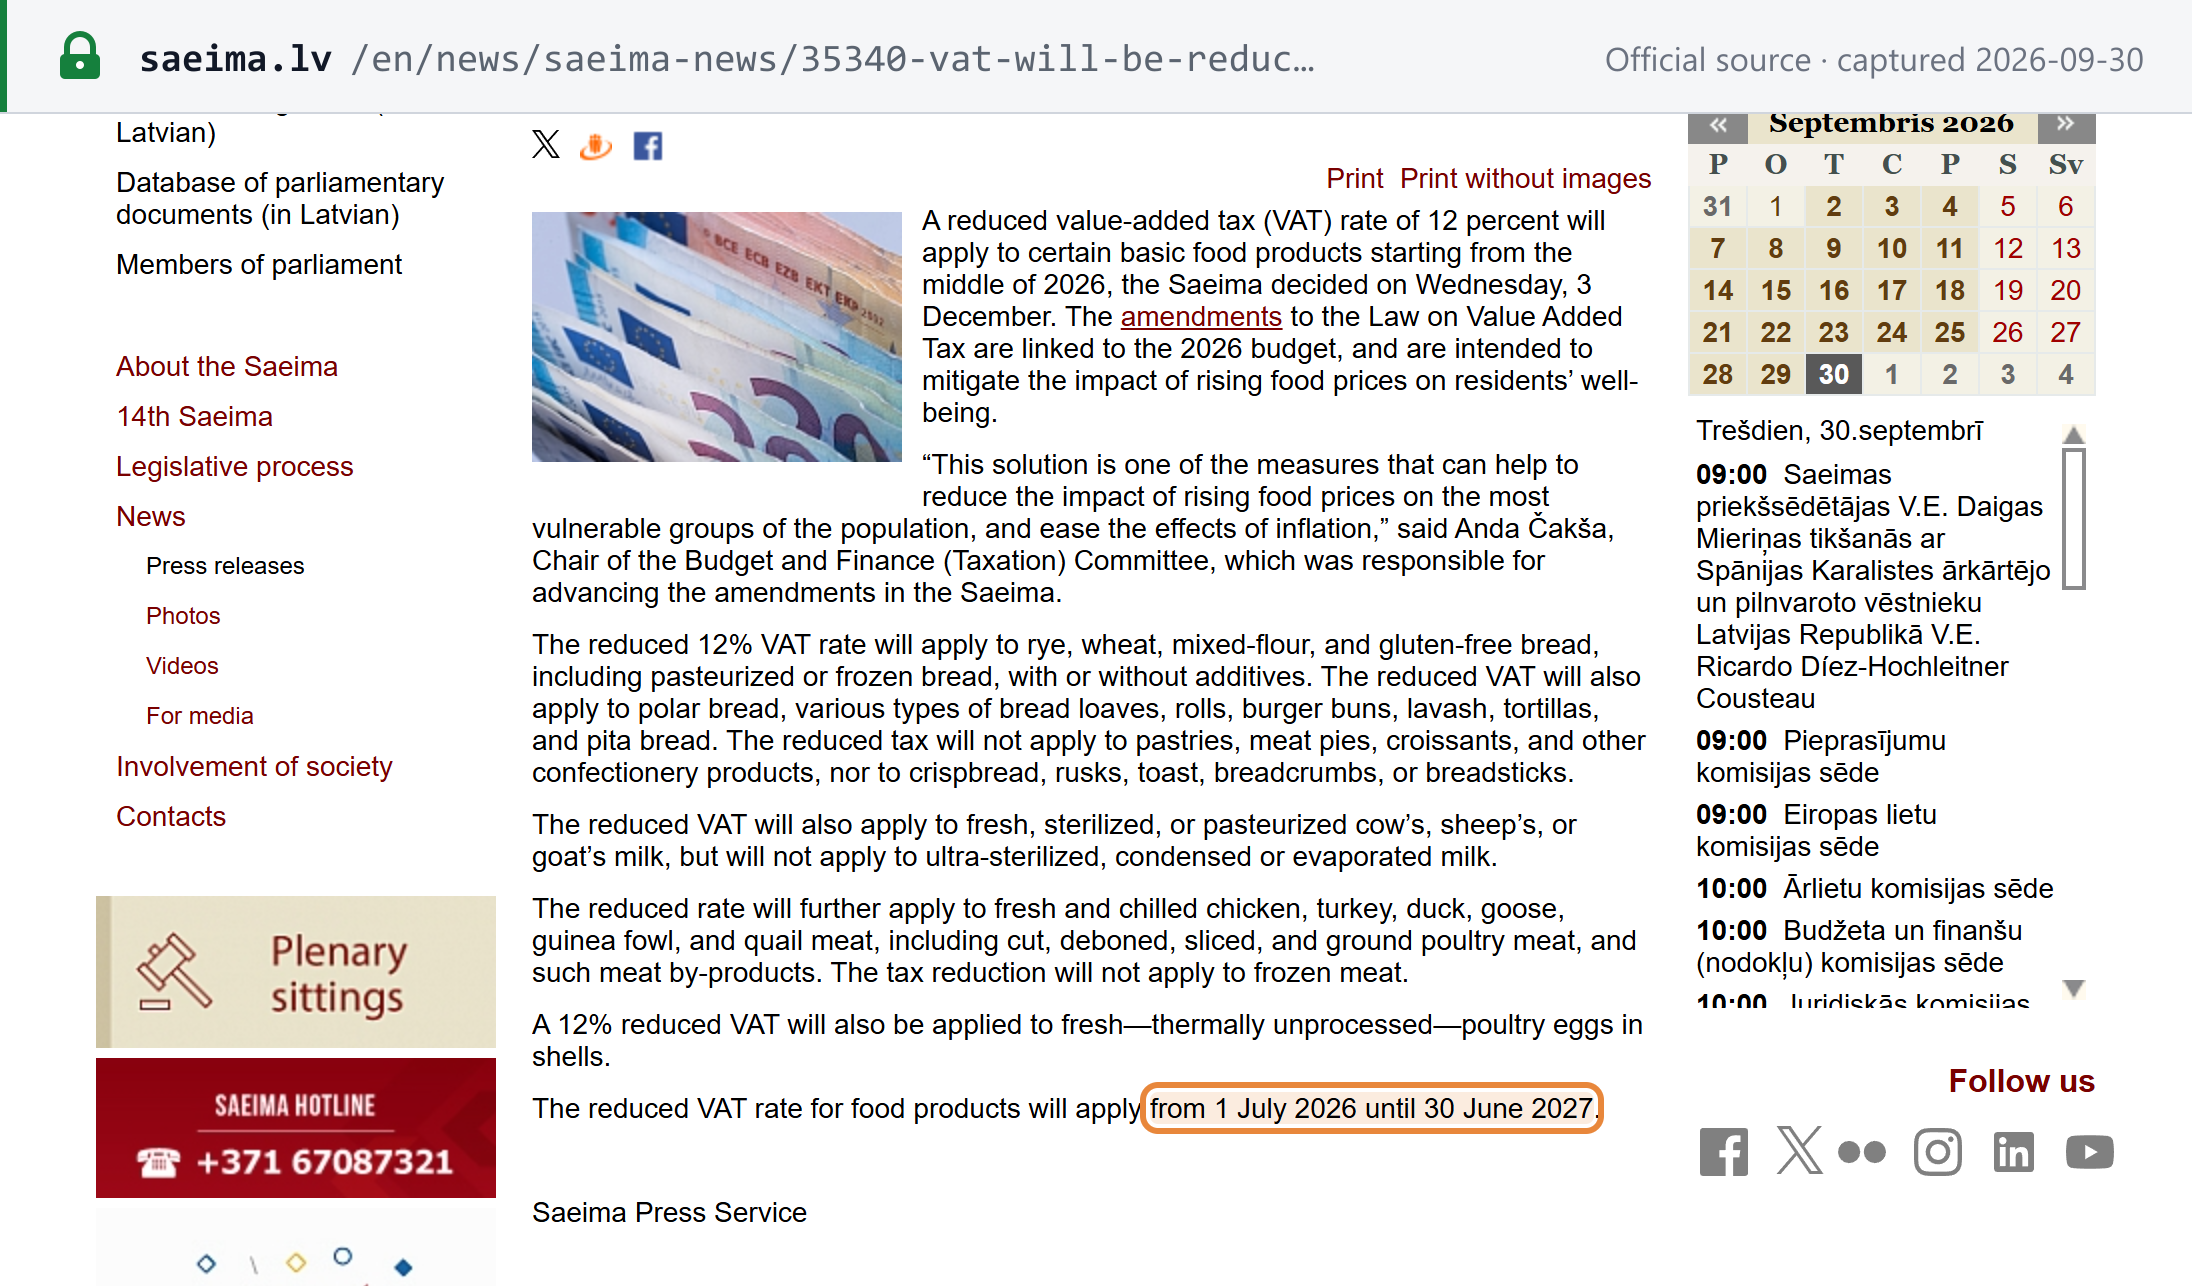
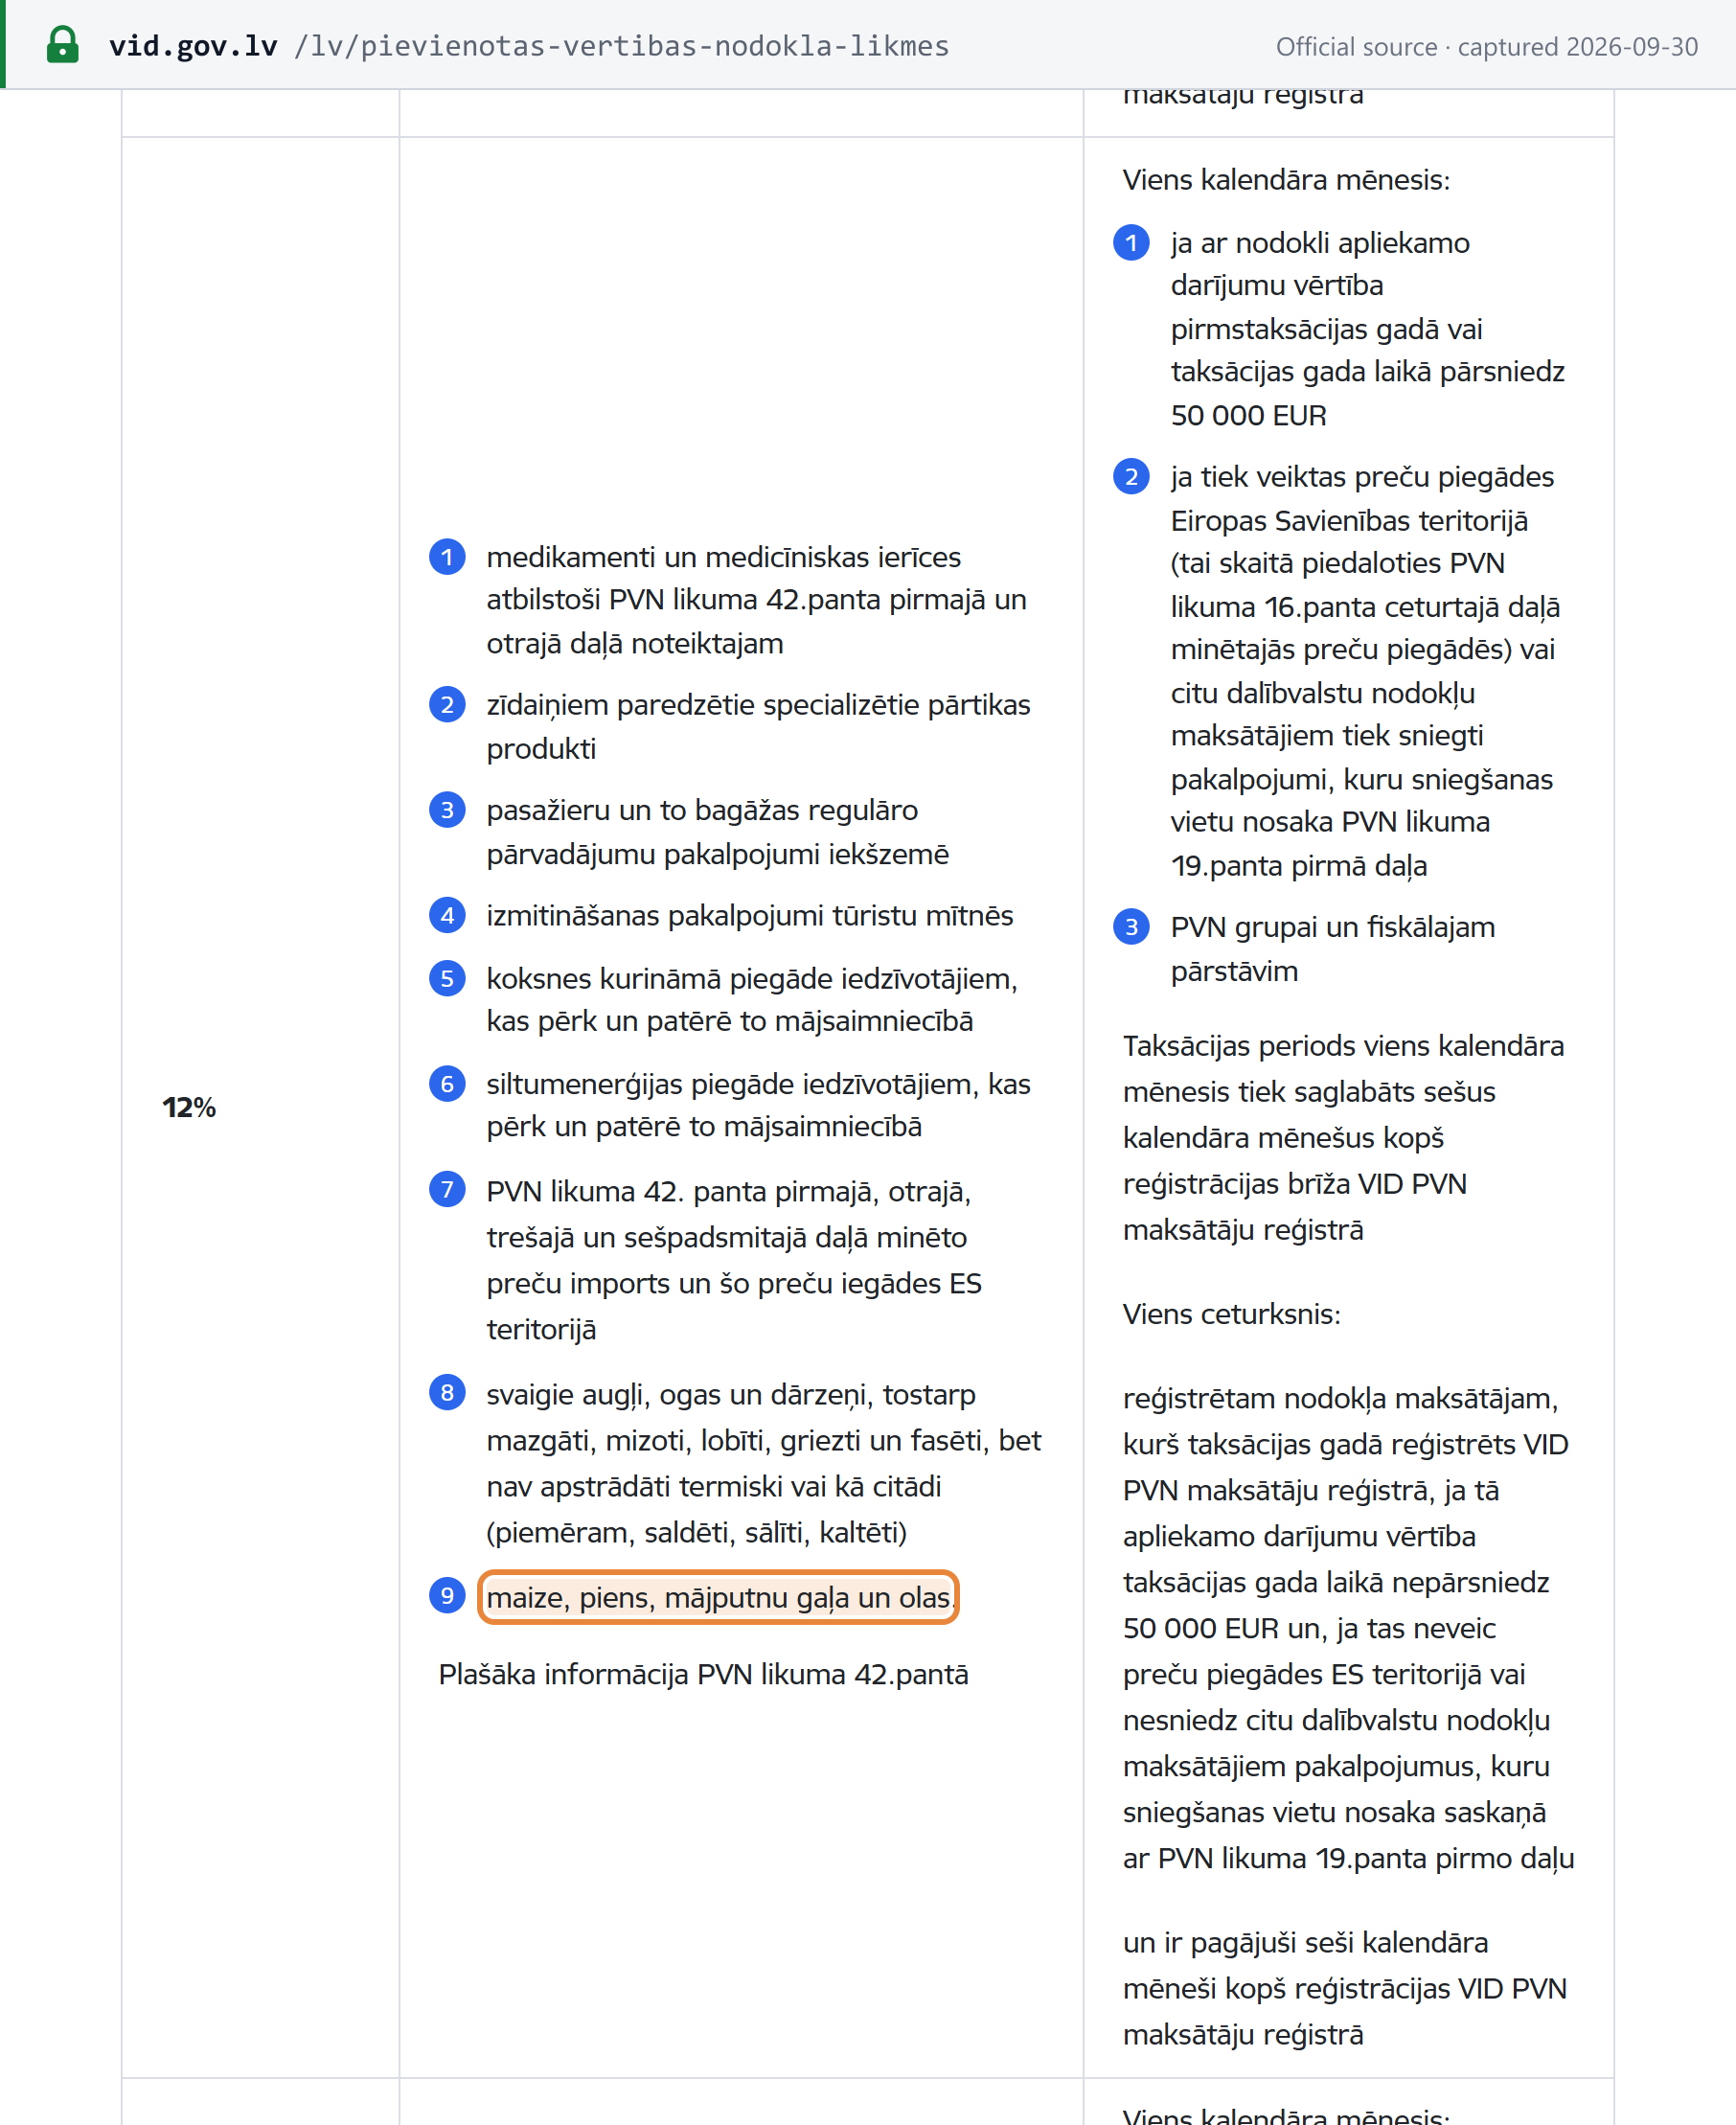
The Ministry of Economics describes the change as lasting one year: "Šīs izmaiņas … būs spēkā vienu gadu – līdz 2027. gada 30. jūnijam" (these changes will be in force for one year, until 30 June 2027). VID's rate table lists both food items under the 12% rate: [9] [3]
Reduced rate — 5%. Applies to books (including educational literature, children's picture and colouring books, printed music and maps), in print or electronic form including downloads (s.42(5)), and to newspapers, magazines, periodicals, news-agency bulletins and online publications, including subscriptions (s.42(7)). Publications that are erotic, mainly advertising, or mainly audiovisual or music content are excluded (s.42(8)). [1]
Language condition since 1 January 2026. The law of 3 December 2025 limited both paragraphs to publications issued "valsts valodā, latgaliešu rakstu valodā … un Latvijas pirmiedzīvotāju — lībiešu — valodā, kā arī citu dalībvalstu, Eiropas Ekonomikas zonas valstu, Šveices Konfederācijas un Eiropas Savienības kandidātvalstu valsts valodās vai Ekonomiskās sadarbības un attīstības organizācijas oficiālajās valodās" — in Latvian, Latgalian or Livonian, or in an official language of another EU or EEA state, Switzerland or an EU candidate state, or an official language of the OECD. Publications in other languages are taxed at 21%. The version of s.42(5) in force on 31 December 2025 had no such condition. [1] [7]
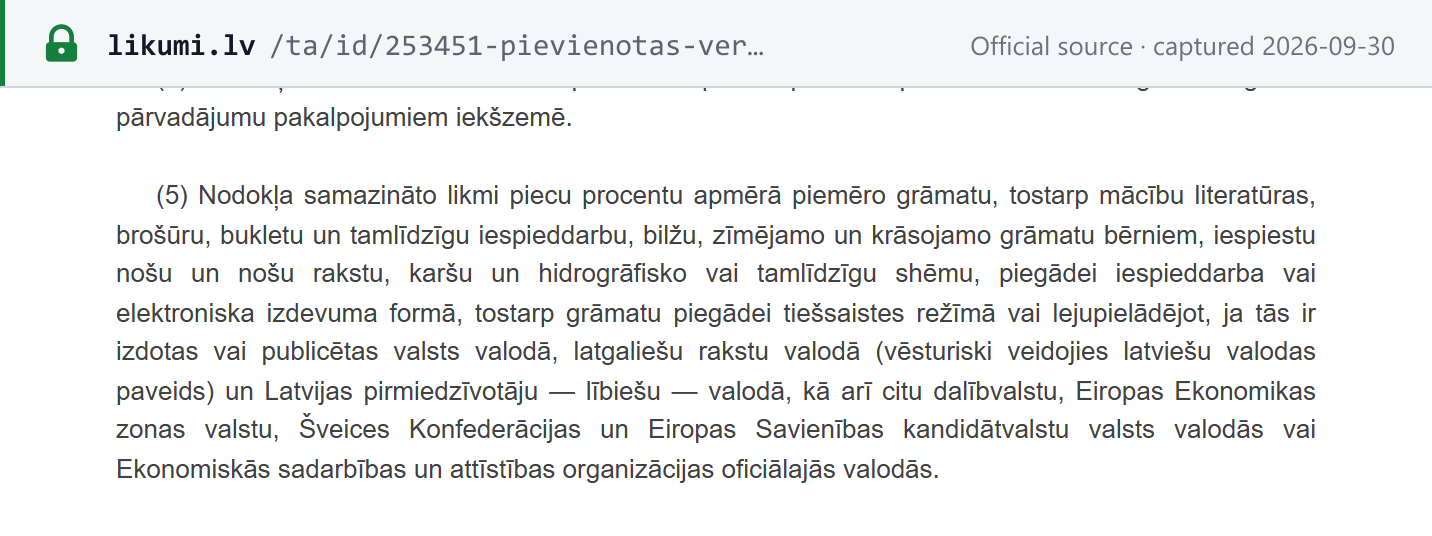
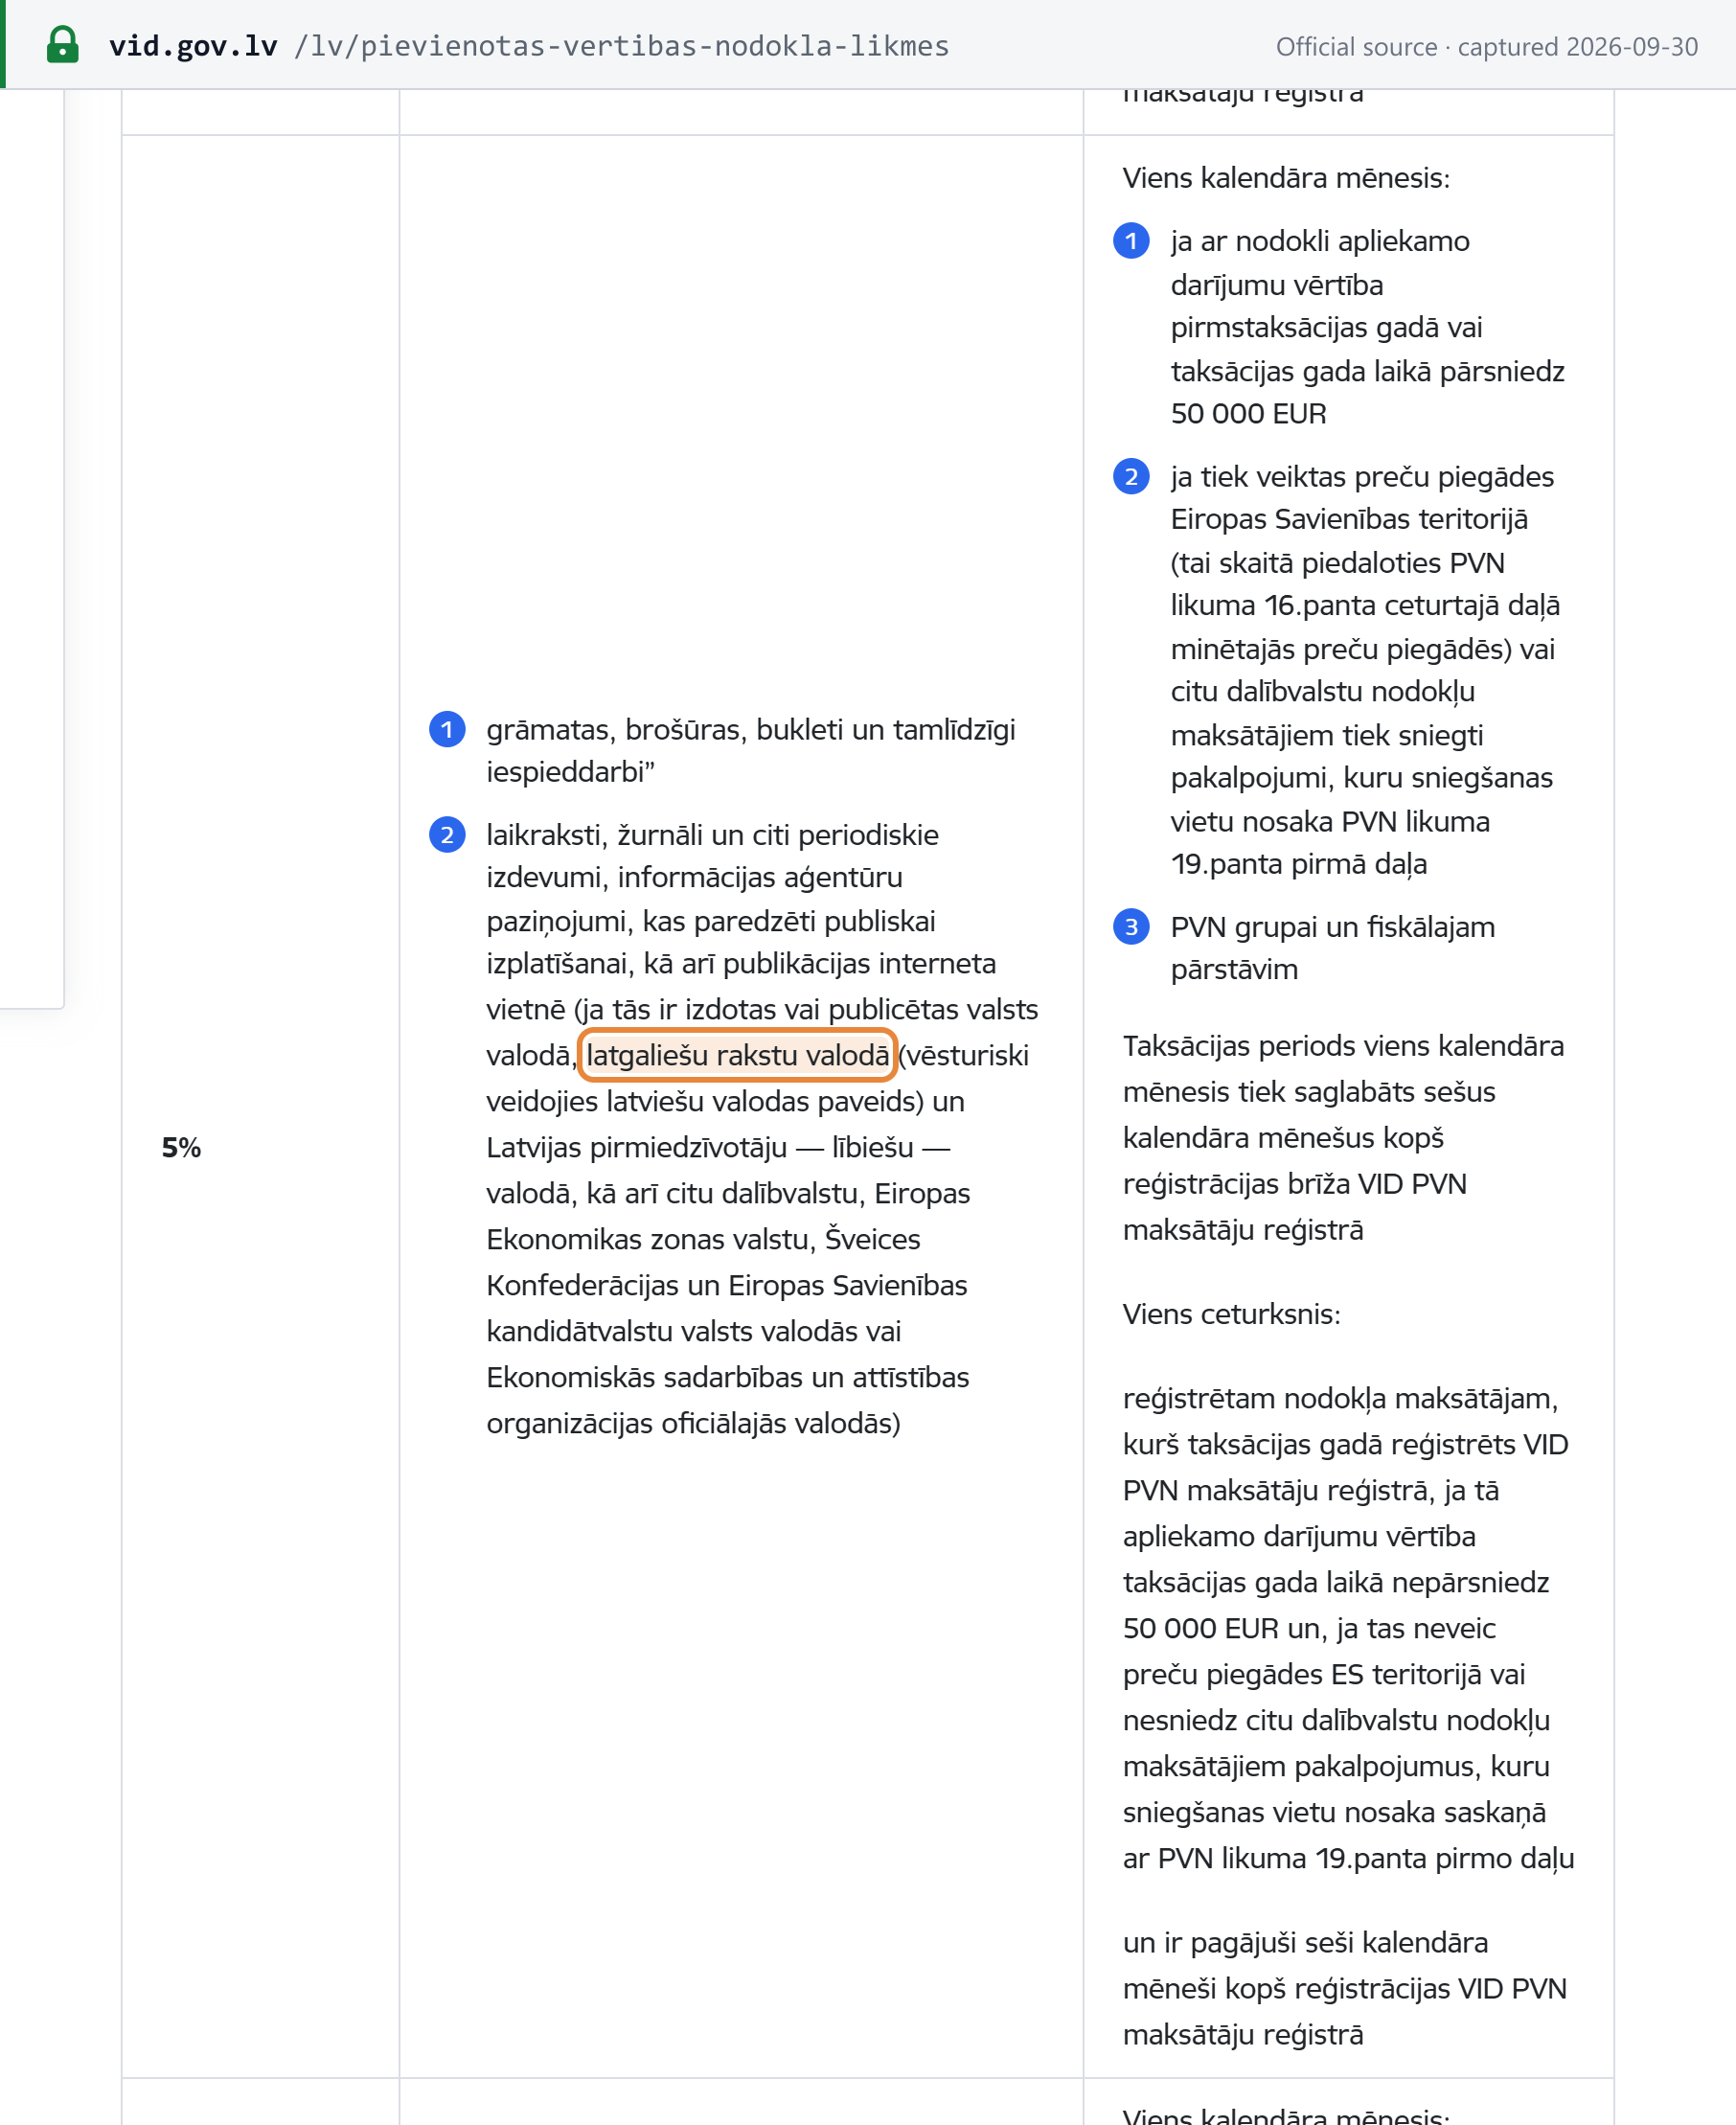
VID's rate table attaches the same language condition to newspapers, magazines and other periodicals:
Zero rate. VID's table lists, among others, "preču eksports" (exports), "preču piegāde ES teritorijā, ja preču saņēmējs ir citas dalībvalsts reģistrēts nodokļa maksātājs un preces tiek piegādātas uz citu dalībvalsti" (intra-EU supplies of goods to a customer registered in another member state, dispatched there) and "starptautiskie pasažieru pārvadājumi" (international passenger transport). The conditions sit in ss.43–51. [3]
| Supply | 2023 | 2024–2025 | 1 Jan – 30 Jun 2026 | 1 Jul 2026 – 30 Jun 2027 |
|---|---|---|---|---|
| Standard-rated goods and services | 21% | 21% | 21% | 21% |
| Fresh fruit, berries, vegetables (Annex 1) | 5% | 12% | 12% | 12% |
| Bread, milk, fresh poultry, eggs (Annex 2) | 21% | 21% | 21% | 12% |
| Books and periodicals, listed languages | 5% | 5% | 5% | 5% |
| Books and periodicals, other languages | 5% | 5% | 21% | 21% |
Announced future rates. None enacted as of 2026-09-30. The only scheduled change is the end of the temporary food rate: unless the law is amended, bread, milk, fresh poultry and eggs return to 21% on 1 July 2027 (transitional provision 48). See the event record for the 12% food rate. [1]
For Latvia alongside other jurisdictions, see Lookuptax's worldwide tax rates table and VAT registration thresholds table.
Cross-border rules
Imports and exports
- Imports of goods. Import VAT is charged at 21%, or at the reduced rate for goods listed in s.42 (s.42¹). A registered business may use the special import regime, deferring the import VAT computed on the customs declaration until it is reported on the VAT return for the period (s.1(8)). Failing to report it there costs a penalty of 10% of the undeclared amount (s.146(3)). [1]
- Low-value consignments. Imported goods sold at a distance to consumers can be declared through the EU import scheme (IOSS) (s.140⁴); VID lists the "Import scheme (IOSS) special scheme for distance sales of goods imported from third territories or third countries". The consignment ceiling is set by EU law — see Lookuptax's IOSS guide. [2]
- Exports and intra-EU supplies. Exports (s.43) and intra-EU supplies of goods to registered customers are zero-rated, with the right to deduct input VAT, and are reported on the monthly EC sales list (see Additional listings). [1]
- Reverse charge on imported services. A Latvian-registered customer self-assesses VAT on services received from foreign suppliers (ss.88–89; VID lists "Receipt of services (Sections 88 and 89 of the VAT Law)"). See Lookuptax's reverse charge explainer. [2]
Domestic reverse charge
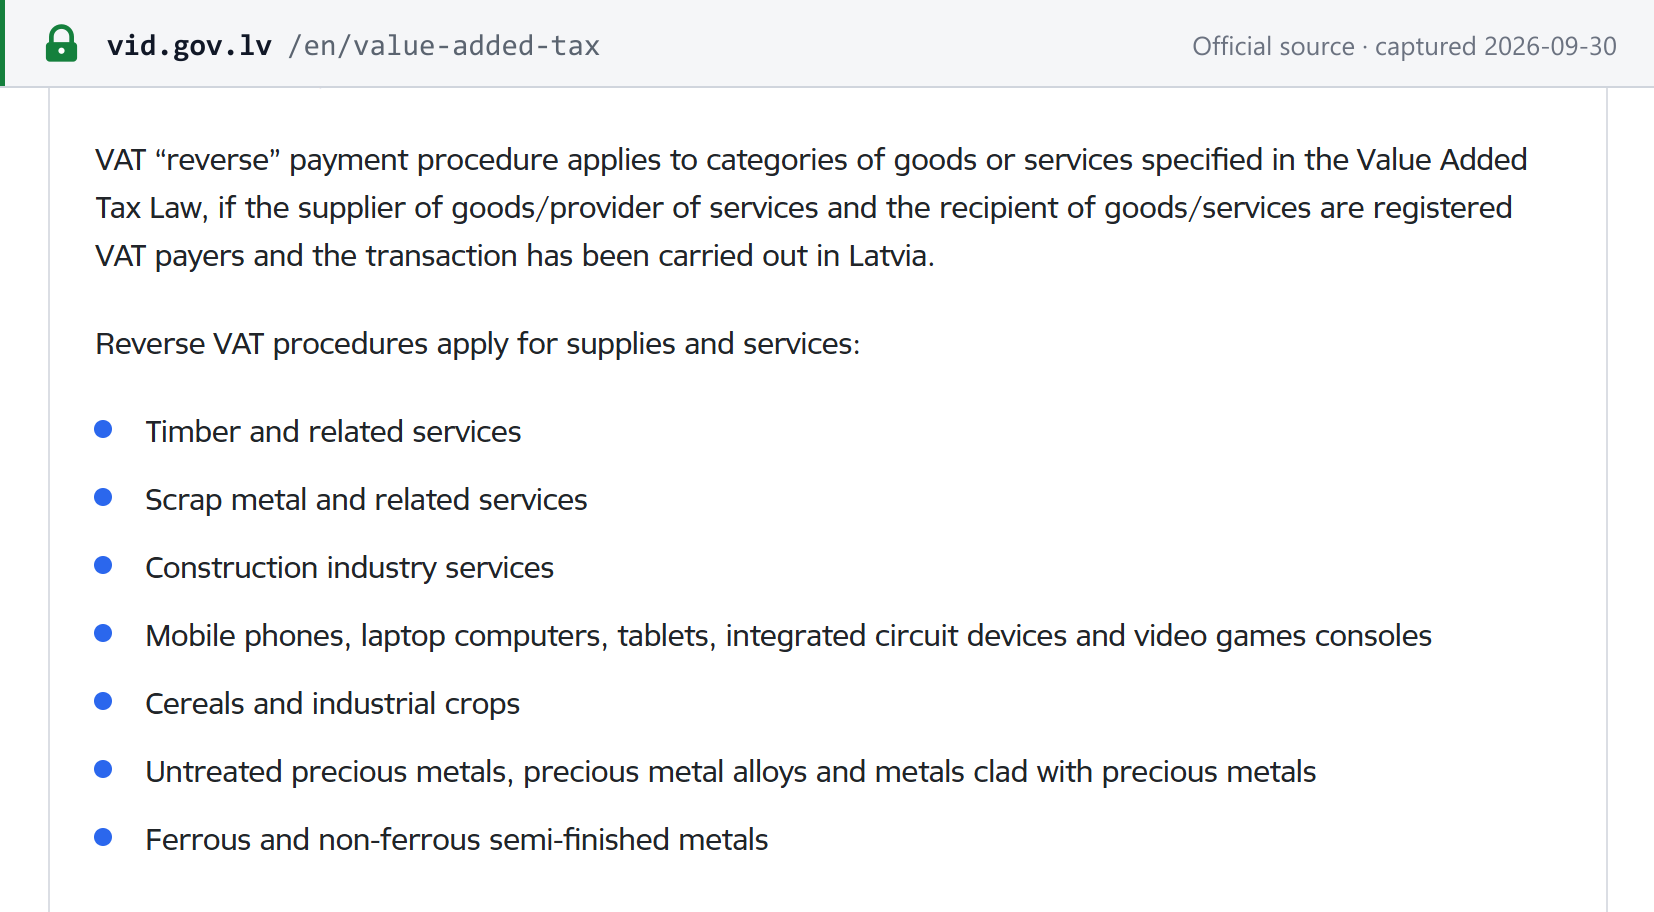
Between two Latvian-registered persons, the customer accounts for the VAT on listed goods and services. VID: "VAT "reverse" payment procedure applies to categories of goods or services specified in the Value Added Tax Law, if the supplier of goods/provider of services and the recipient of goods/services are registered VAT payers and the transaction has been carried out in Latvia." The categories are timber and related services (s.141), construction services (s.142), scrap metal (s.143), mobile phones, laptops, tablets, integrated circuit devices and game consoles (s.143¹), cereals and industrial crops, unprocessed precious metals, and ferrous and non-ferrous semi-finished metals. The invoice is marked "nodokļa apgrieztā maksāšana" and shows no VAT rate or amount (s.129(3)). [2] [1]
Digital products and services
Telecommunications, broadcasting and electronic services to consumers are taxed where the consumer is. EU sellers count them, with intra-EU distance sales of goods, towards the EU-wide EUR 10,000 threshold: s.13¹(2)(3) refers to supplies whose "kopējā vērtība bez nodokļa iepriekšējā vai kārtējā kalendāra gadā nepārsniedz 10 000 euro" (total value excluding VAT in the previous or current calendar year does not exceed EUR 10,000). Above it, Latvian VAT applies, declared either through a Latvian registration within 30 days (s.60(2), (5)) or through the Union OSS (s.140³). Non-EU sellers have no threshold and can declare their B2C services through the non-Union OSS (s.140²). [1] [2]
See Lookuptax's One-Stop Shop guide and VAT on digital services by non-resident suppliers.
Foreign companies selling into Latvia — B2B and B2C
- B2B — usually no Latvian registration. For services under the B2B general rule, the Latvian-registered customer self-assesses the VAT (ss.88–89), and the foreign supplier need not register (s.61(1) for EU businesses, s.63(1) for non-EU businesses). [1]
- B2C — the seller is liable. EU sellers of distance-sold goods or electronic services register in Latvia within 30 days of passing EUR 10,000 EU-wide, or use the Union OSS; non-EU providers of electronic services use the non-Union OSS; imported low-value goods can go through IOSS. A non-EU seller making other taxable supplies in Latvia — for example selling goods held in Latvia — must register before its first supply, because it has no threshold (s.63). An EU seller making such supplies can use the EUR 50,000 threshold unless its EU-wide turnover exceeds EUR 100,000 (s.61(11)–(12)). [1]
Marketplace / platform deemed-supplier liability
Applies. An electronic interface that facilitates distance sales of goods is treated as having received and supplied the goods itself (PVN likums s.6(5)–(6), following the EU rules). It must keep records of those transactions "10 gadus pēc tā gada 31. decembra, kad darījums veikts" — for 10 years after 31 December of the year of the transaction (s.134(6)(3)). See Lookuptax's marketplace deemed-supplier explainer. [1]
Place of supply
- Services, B2B. Where the customer has its place of business: "Ja pakalpojums tiek sniegts nodokļa maksātājam, pakalpojuma sniegšanas vieta … ir: 1) pakalpojuma saņēmēja saimnieciskās darbības mītnes vieta" (s.19(1)). [1]
- Services, B2C. Where the supplier has its place of business (s.19(2)). [1]
- Exceptions. Sections 20–30 set special rules for services connected with real estate, transport, events, restaurant and catering services, hire of means of transport, and telecommunications, broadcasting and electronic services. [1]
- Goods. Intra-EU distance sales of goods are taxed where transport ends once the EUR 10,000 EU-wide threshold is exceeded (s.13¹). [1]
Invoice requirements
The invoicing rules sit in ss.125–134 of the PVN likums. VID publishes no official annotated specimen invoice; the specimen further down is Lookuptax's own illustration. [1]
When an invoice is required. A registered person issues a tax invoice (nodokļa rēķins) for every supply of goods or services and for advance payments, except advances for intra-EU supplies of goods (s.127(1)). Most exempt supplies need none (s.127(2)). For supplies to consumers and to unregistered persons, an invoice is issued only on request: "… izraksta pēc šo personu pieprasījuma" (s.127(3)). [1]
Mandatory content
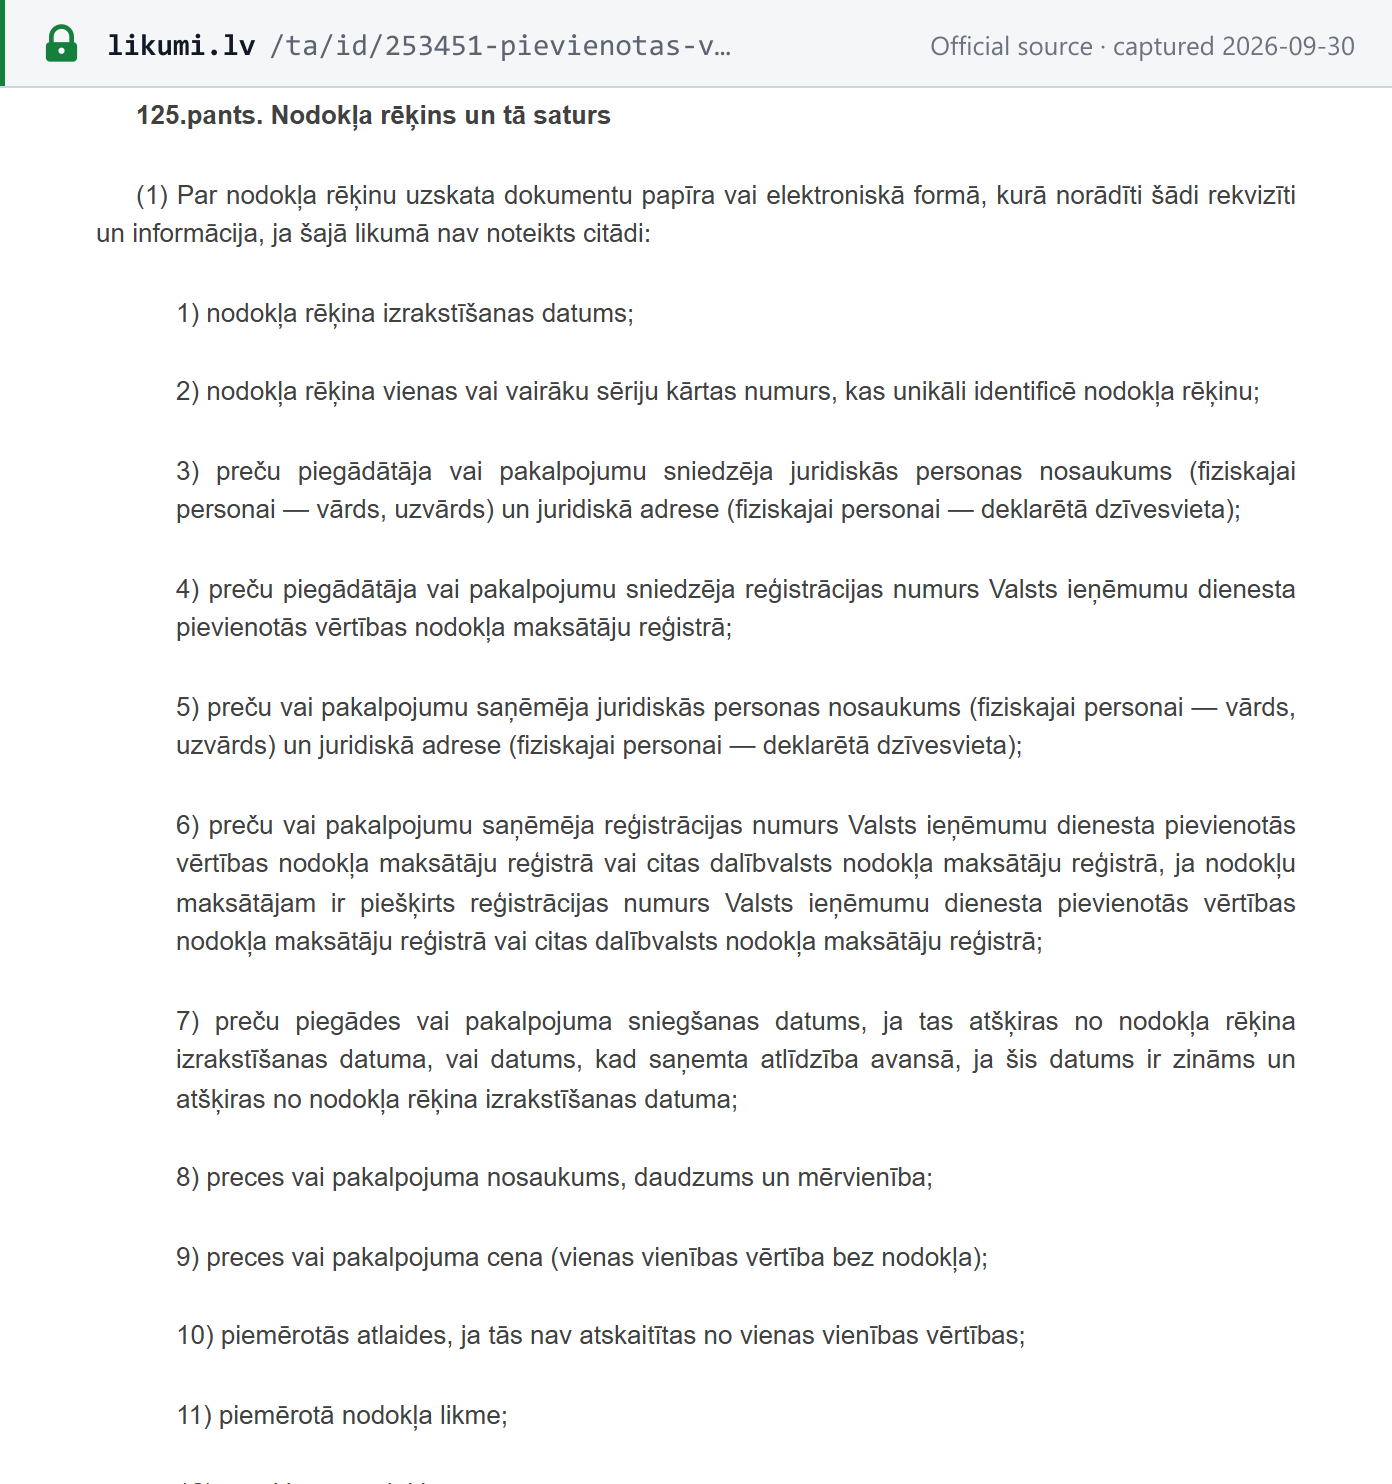
"Par nodokļa rēķinu uzskata dokumentu papīra vai elektroniskā formā, kurā norādīti šādi rekvizīti un informācija" — a tax invoice is a document on paper or in electronic form showing the following particulars (s.125(1)): [1]
| # | Required field | Legal cite |
|---|---|---|
| 1 | Date of issue | s.125(1)(1) |
| 2 | Sequential number, in one or more series, that uniquely identifies the invoice | s.125(1)(2) |
| 3 | Supplier's name and legal address (for an individual, name and declared residence) | s.125(1)(3) |
| 4 | Supplier's Latvian VAT registration number | s.125(1)(4) |
| 5 | Customer's name and legal address | s.125(1)(5) |
| 6 | Customer's Latvian or other-EU VAT number, where it has one | s.125(1)(6) |
| 7 | Date of supply or of the advance payment, where it differs from the issue date | s.125(1)(7) |
| 8 | Description, quantity and unit of measure of the goods or services | s.125(1)(8) |
| 9 | Unit price excluding VAT | s.125(1)(9) |
| 10 | Discounts not already deducted from the unit price | s.125(1)(10) |
| 11 | VAT rate applied | s.125(1)(11) |
| 12 | VAT amount | s.125(1)(12) |
| 13 | Total excluding VAT | s.125(1)(13) |
| 14 | "pašaprēķins" (self-billing), where the customer issues the invoice | s.125(1)(14) |
| 15 | Legal basis for the 0% rate or an exemption — the article of the PVN likums or of Directive 2006/112/EC | s.125(1)(15) |
| 16 | "nodokļa apgrieztā maksāšana" (reverse charge), where the customer is liable | s.125(1)(16) |
| 17 | Details of a new means of transport | s.125(1)(17) |
| 18 | "naudas līdzekļu uzskaite" (cash accounting) | s.125(1)(18) |
| 19 | "peļņas daļas režīms ceļojumu aģentūrām" (margin scheme for travel agents) | s.125(1)(19) |
| 20 | Margin-scheme note for second-hand goods, works of art, collectors' items and antiques | s.125(1)(20) |
| 21 | References to other special regimes | s.125(1)(21) |
| 22 | Details of an authorised person | s.125(1)(22) |
| 23 | Details of a fiscal representative | s.125(1)(23) |
Where supplies at different rates, or exempt supplies, appear on one invoice, their values are shown separately (s.129(4)). [1]
Issuance deadline
- Domestic supplies: "ne vēlāk kā piecpadsmitajā dienā no darījuma brīža vai avansa maksājuma saņemšanas brīža" — no later than the 15th day after the transaction or receipt of an advance payment (s.131(1)). [1]
- Intra-EU supplies of goods and B2B services reverse-charged in another member state: by the 15th of the following month (s.131(2)). [1]
- Transport linked to exports: within 90 days (s.131(4)). [1]
- Summary invoices. A monthly summary invoice is allowed (s.129(1)), and continuous supplies may be invoiced per period of up to one month, six months or one year (s.129(9)). [1]
Numbering and sequencing
Each invoice carries a sequential number in one or more series that uniquely identifies it (s.125(1)(2)). Cancelled invoices are kept, so that gaps in the sequence can be justified (s.129(6)). [1]
Credit and debit notes
Any document that amends the original invoice and refers to it clearly counts as an invoice if it carries the s.125(1) particulars (s.125(5)). A simplified amending document is allowed if it shows the original invoice's date and number and the changed data (s.126(2)(2)). [1]
Currency and language
- Currency and FX. "Nodokļa rēķinā norādītās summas var izteikt jebkurā valūtā ar nosacījumu, ka maksājamā vai koriģējamā nodokļa summa ir izteikta euro saskaņā ar grāmatvedībā izmantojamo ārvalstu valūtas kursu, kas ir spēkā attiecīgi darījuma dienas sākumā vai avansa maksājuma saņemšanas dienas sākumā" — amounts may be in any currency, provided the VAT payable or adjusted is stated in euros at the accounting exchange rate in force at the start of the transaction day or the day the advance is received (s.129(5)). [1]
- Language. The PVN likums (ss.125–134) sets no language requirement for invoices. The Accounting Law does, for bookkeeping: entries in the accounting registers are made in Latvian (s.9(1)). [1] [10]
Document types
| Document | When it is used | Cite |
|---|---|---|
| Full tax invoice (nodokļa rēķins) | Default for all supplies and advances | s.125(1) |
| Simplified invoice (vienkāršotais nodokļa rēķins) | Domestic transactions under EUR 150 excluding VAT; documents amending an original invoice | s.126(2) |
| Till receipt without customer details | Transactions under EUR 30 excluding VAT; above that, a receipt needs a supporting document carrying the missing data | s.126(3)–(4) |
| Self-billed invoice | Issued by the customer under a prior agreement, marked "pašaprēķins" | s.130 |
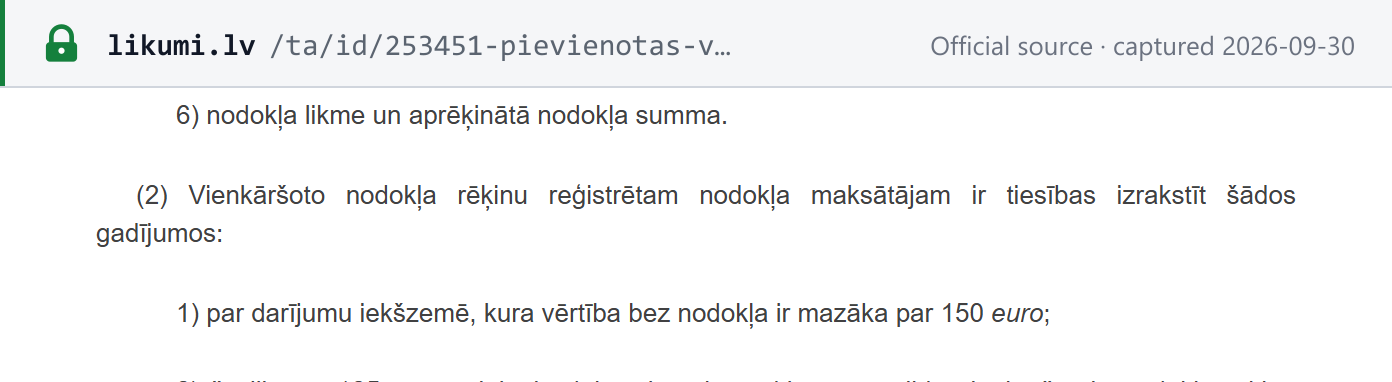
A simplified invoice shows the date; the supplier's name, address and VAT number; the customer's name, address and VAT number; a description and quantity; the price and total (with or without VAT); and the VAT rate and amount (s.126(1)). It may be issued "par darījumu iekšzemē, kura vērtība bez nodokļa ir mazāka par 150 euro" — for a domestic transaction whose value excluding VAT is less than EUR 150 (s.126(2)(1)). [1]
Self-billing
Permitted. "Preču vai pakalpojumu saņēmējs ir tiesīgs izrakstīt pats sev nodokļa rēķinu preču piegādātāja vai pakalpojumu sniedzēja vārdā un interesēs …, ja starp abām pusēm pastāv iepriekšēja vienošanās un ja preču piegādātājs vai pakalpojumu sniedzējs katram rēķinam piemēro savstarpējo rēķinu atzīšanas procedūru" — the customer may issue an invoice to itself in the supplier's name if the parties have a prior agreement and the supplier applies an acceptance procedure to each invoice (s.130). The invoice is marked "pašaprēķins" (s.125(1)(14)). [1]
Retention and audit trail
- Retention. "Nodokļa rēķinu glabāšanas laiks ir pieci gadi no rēķina izrakstīšanas dienas" — invoices are kept five years from the date of issue (s.133(4)), longer where a real-estate input-tax adjustment is still running (s.133(5)). Separate retention rules for accounting records under the Accounting Law are not covered here. [1]
- Where. Issued and received invoices are kept in Latvia, unless they are stored electronically with full online access to the data (s.133(3)). Paper invoices may be converted and kept electronically (s.133(2¹)). [1]
- Audit trail. The taxpayer must ensure the authenticity of origin, integrity of content and legibility of each invoice from issue until the end of the retention period (s.125(3)); it chooses how, but must be able to link each invoice to the transaction (s.125(4)). Electronic invoices need the recipient's acceptance (s.132(1)); a secure electronic signature or EDI is one way to meet the integrity requirement (s.132(2)). Records must be detailed enough for VID to verify them (s.134(2)). [1]
A specimen of a compliant invoice
No official specimen invoice is published; the example below is ours — Lookuptax's illustration of the s.125(1) particulars for a domestic B2B supply at two rates. Every name, number and amount in it is fictional:
Nodokļa rēķins — Tax invoice
| Descriptions.125(1)(8) | Quantity and units.125(1)(8) | Unit price (excl. VAT)s.125(1)(9) | VAT rates.125(1)(11) | Value (excl. VAT) |
|---|---|---|---|---|
| Shelf merchandising services | 10 hours | EUR 60.00 | 21% | EUR 600.00 |
| Rye bread | 20 loaves | EUR 2.50 | 12% | EUR 50.00 |
- Total excluding VATs.125(1)(13)
- EUR 650.00
- VAT at 21%s.125(1)(12)
- EUR 126.00
- VAT at 12%s.125(1)(12)
- EUR 6.00
- Total including VAT
- EUR 782.00
- Values at different rates are shown separately — s.129(4). The 12% rate on bread applies only from 1 July 2026 to 30 June 2027 (transitional provision 48).
- The VAT amounts must be stated in euros, even if the invoice is in another currency — s.129(5).
- Where the customer is liable for the VAT, the invoice shows no VAT rate or amount and carries the note "nodokļa apgrieztā maksāšana" — s.125(1)(16), s.129(3). A 0% or exempt line cites its legal basis — s.125(1)(15).
- From 1 January 2028 an invoice to another Latvian-registered business must be a structured e-invoice (EN 16931) — see E-invoicing status.
E-invoicing status
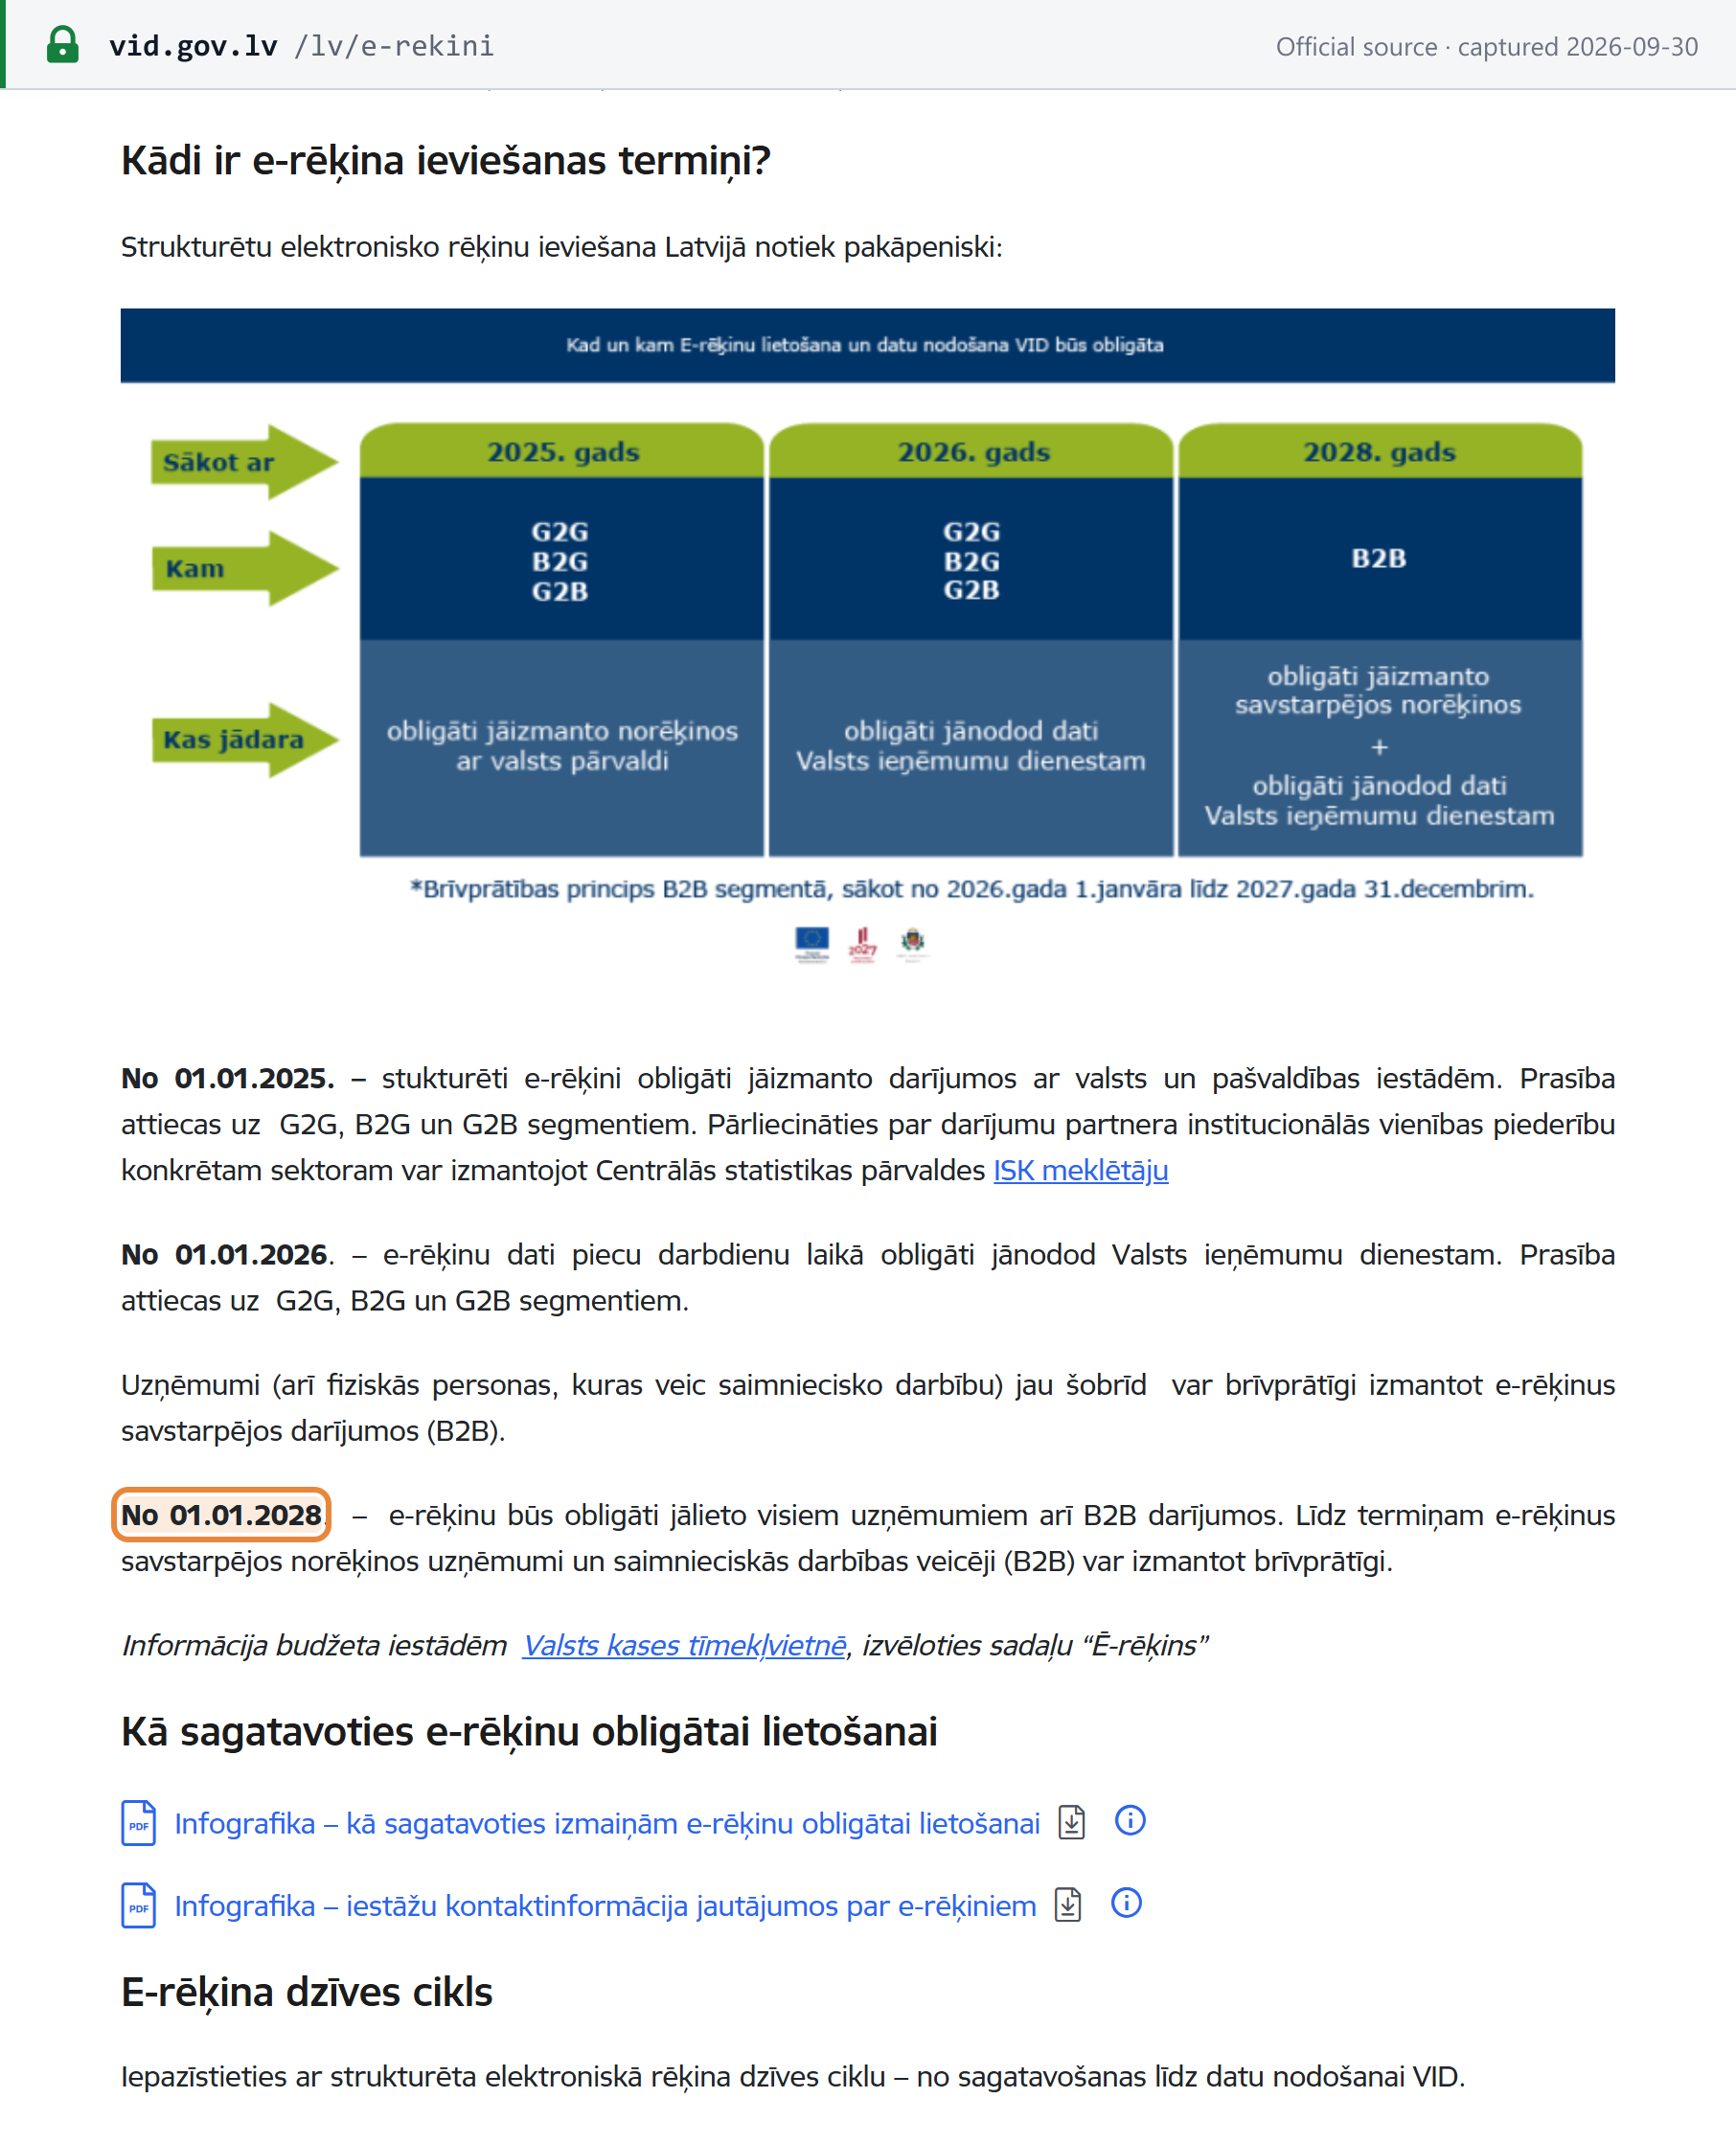
Status (as of 2026-09-30): B2G, G2G and G2B structured e-invoices mandatory since 1 January 2025, with e-invoice data reported to VID since 1 January 2026. B2B: voluntary until 31 December 2027, mandatory from 1 January 2028. B2C: out of scope. For Latvia alongside other jurisdictions, see Lookuptax's e-invoicing status and networks table.
Legal basis. The mandate sits in the Accounting Law (Grāmatvedības likums), not the VAT Law. Section 11(14): "Attaisnojuma dokumentu, kuru uzņēmums izsniedz citam Latvijas Republikā reģistrētam uzņēmumam — preces vai pakalpojuma saņēmējam — samaksāšanai (rēķinu), noformē kā strukturētu elektronisko rēķinu" — a source document (invoice) that an undertaking issues for payment to another undertaking registered in Latvia is prepared as a structured electronic invoice. Section 1(9) defines a structured e-invoice as one in a structured format allowing automatic processing, compliant with LVS EN 16931-1:2017 and issued in line with LVS CEN/TS 16931-2:2017. [10]
| From | Scope | Obligation |
|---|---|---|
| 1 January 2025 | G2G, B2G, G2B | Structured e-invoices mandatory in dealings with state and municipal bodies. For B2G contracts concluded by 31 December 2024 the obligation applied no later than 1 January 2026 (Accounting Law transitional provision 9) |
| 1 January 2026 | G2G, B2G, G2B | E-invoice data sent to VID within five working days of sending the invoice (Accounting Law transitional provision 10 for invoices to budget institutions; Cabinet Regulation 749, point 14, and VID for all three segments) |
| 1 January 2026 – 31 December 2027 | B2B | Voluntary; voluntary submission of data to VID possible from 1 January 2026 (Cabinet Regulation 749, point 18) |
| 1 January 2028 | B2B — all Latvian-registered undertakings, including self-employed persons | Structured e-invoices mandatory and data sent to VID (transitional provisions 8 and 10) |
VID (page updated 30 September 2026): "No 01.01.2028. – e-rēķinu būs obligāti jālieto visiem uzņēmumiem arī B2B darījumos. Līdz termiņam e-rēķinus savstarpējos norēķinos uzņēmumi un saimnieciskās darbības veicēji (B2B) var izmantot brīvprātīgi" — from 1 January 2028 all undertakings must use e-invoices in B2B transactions too; until then businesses may use them voluntarily. [12]
The B2B date was moved once. Transitional provision 8 as amended by the law of 5 June 2025 (in force 12 June 2025) reads: "… noformēt kā strukturētu elektronisko rēķinu piemērojams, sākot no 2028. gada 1. janvāra" — the obligation applies from 1 January 2028. The date had earlier been 1 January 2026. [10]
- Format. VID's solution accepts XML that "atbilst UBL 2.1 un Pan-European Public Procurement On-Line (PEPPOL) BIS Billing 3.0 specifikācijai" — conforms to UBL 2.1 and the Peppol BIS Billing 3.0 specification (Cabinet Regulation 749, point 7). VID stores e-invoices without attachments. See Lookuptax's Peppol guide. [11]
- Channels. The parties agree between themselves which channel to use (points 4–5): the state official electronic address (e-adrese) on Latvija.gov.lv, which forwards e-invoices to VID automatically; a service provider or operator channel, such as a Peppol access point integrated with the VID API; or another channel (system integration, e-mail), in which case the sender uploads the invoice to VID through the EDS API or by file upload. VID publishes a list of e-invoice service providers. [11] [12]
- Reporting to VID. "E-rēķinu Valsts ieņēmumu dienestam iesniedz vienu reizi ne vēlāk kā piecu darbdienu laikā pēc tā nosūtīšanas dienas" — the e-invoice is submitted to VID once, no later than five working days after the day it is sent (point 14). During a system outage, the sender notifies VID via EDS by the next working day and submits within three working days of the fix (point 15); if late for other reasons, it notifies via EDS and submits within 30 calendar days (point 17). [11]
- B2C. Out of scope: s.11(14) of the Accounting Law covers only invoices to another Latvian-registered undertaking, and s.11(16) excludes cash-register receipts. [10]
- Foreign businesses. The obligation applies to the "subjects" of the Accounting Law (Cabinet Regulation 749, point 3). Whether a foreign business registered for Latvian VAT without an establishment in Latvia falls under the 2028 B2B obligation is not settled by the texts cited here; check with VID before relying on either answer. [11]
- Penalties. Neither the Accounting Law nor Cabinet Regulation 749 sets a specific fine for e-invoicing non-compliance. [10] [11]
The Ministry of Finance publishes background on the reform on its structured e-invoice page. For the EU's cross-border e-invoicing plans, see Lookuptax's ViDA guide.
Filing and payment
Filing frequency
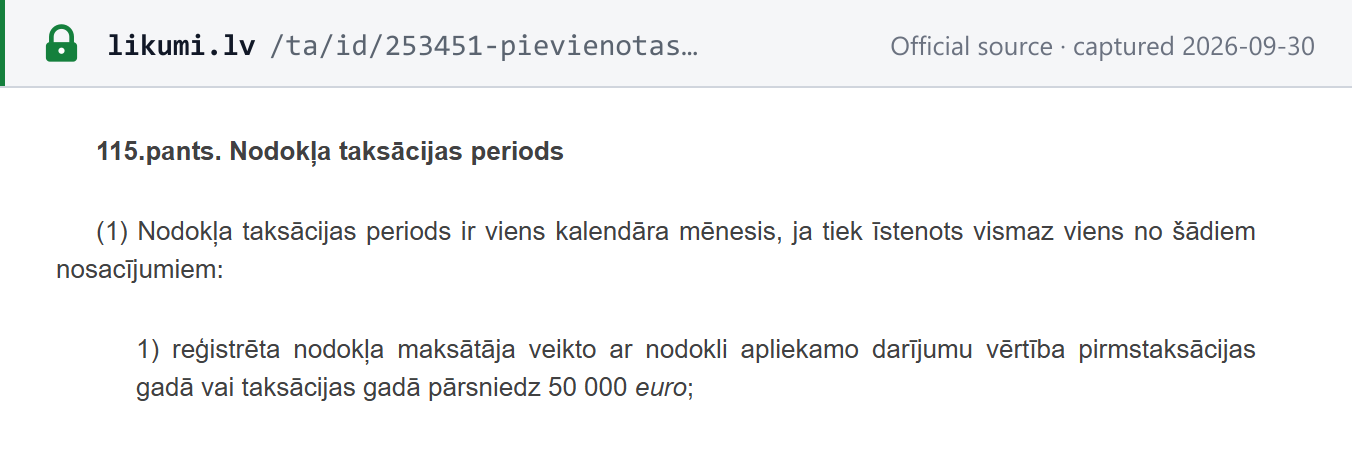
The VAT period is one calendar month if at least one of these applies (s.115(1)–(2), (7)): [1]
- taxable transactions in the previous or current taxable year exceed EUR 50,000;
- the business makes zero-rated intra-EU supplies of goods, takes part in triangulation, supplies B2B services to other member states under the general rule, or moves goods to a call-off stock in another member state;
- it registered less than six months ago; or
- it is a VAT group or a fiscal representative.
Otherwise the period is one calendar quarter (s.115(3)). A business switching from quarterly to monthly does so in its January return, or mid-year once a trigger is met (then monthly to the end of the year); a switch from monthly to quarterly is notified by 31 January (s.115(4)–(6)). [1]
"Nodokļa taksācijas periods ir viens kalendāra mēnesis, ja tiek īstenots vismaz viens no šādiem nosacījumiem: 1) reģistrēta nodokļa maksātāja veikto ar nodokli apliekamo darījumu vērtība pirmstaksācijas gadā vai taksācijas gadā pārsniedz 50 000 euro; …" (s.115(1))
(The tax period is one calendar month where at least one of the following conditions is met: 1) the registered taxable person's taxable transactions in the previous or current taxable year exceed EUR 50,000; …)
Return due date
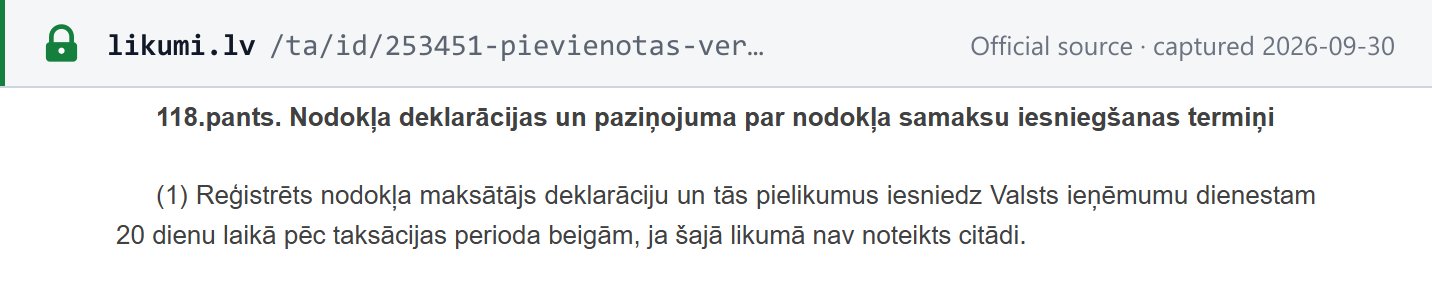
The return and its annexes are filed through EDS "20 dienu laikā pēc taksācijas perioda beigām" — within 20 days after the end of the tax period (s.118(1)). A deadline falling on a weekend or public holiday moves to the next working day (s.118(7)). A return is due even for a period with no taxable transactions (s.117(2)). [1]
Annual return. A return for the taxable year (deklarācija par taksācijas gadu) is due by 1 May of the following year only in specific cases — a change in the taxable/exempt proportion, other adjustments, certain financial transactions, or deposit packaging (s.117(5), s.118(5)). Any balance is paid by the same date (s.119(6)). [1]
Payment due date and method
VAT for the period is paid within 23 days after its end (s.119(1)) — three days after the return. Payment goes to the single tax account (vienotais nodokļu konts) referred to in s.29(2¹) of the law On Taxes and Fees. [1] [13]
Additional listings
- Input/output tax report (the domestic transaction listing annexed to the return) — part of the return annexes listed in s.116(2). [1]
- EC sales list (pārskats par preču piegādēm un sniegtajiem pakalpojumiem Eiropas Savienības teritorijā): monthly, by the same 20-day deadline, whenever the business supplies goods within the EU, supplies B2B services under the general rule, or moves goods to a call-off stock in another member state (s.118(6)). [1]
- Other annexes: the correction report for the EC sales list, the real-estate use report and the fiscal representative's report (s.116(2)). [1]
- Intrastat is a statistical obligation, not part of the VAT return.
See Lookuptax's VAT listings explainer and VIES and Intrastat guide.
Input-tax recovery and blocked items
VAT on purchases, imports, reverse-charged services and intra-EU acquisitions used for taxable transactions — or for transactions abroad that would be taxable in Latvia — is deductible (s.92(1)); a business with exempt supplies apportions (s.98). [1]
- Timing. Input VAT is deducted in the period in which the goods or services and the invoice are received (or payment was made in advance), "bet ne vēlāk kā nākamajā taksācijas periodā" — but no later than the following tax period (s.97(1)). [1]
- Supplier check. The buyer must verify that the invoice was issued by a registered taxable person (s.92(6)). [1]
Section 100 restricts the deduction: [1]
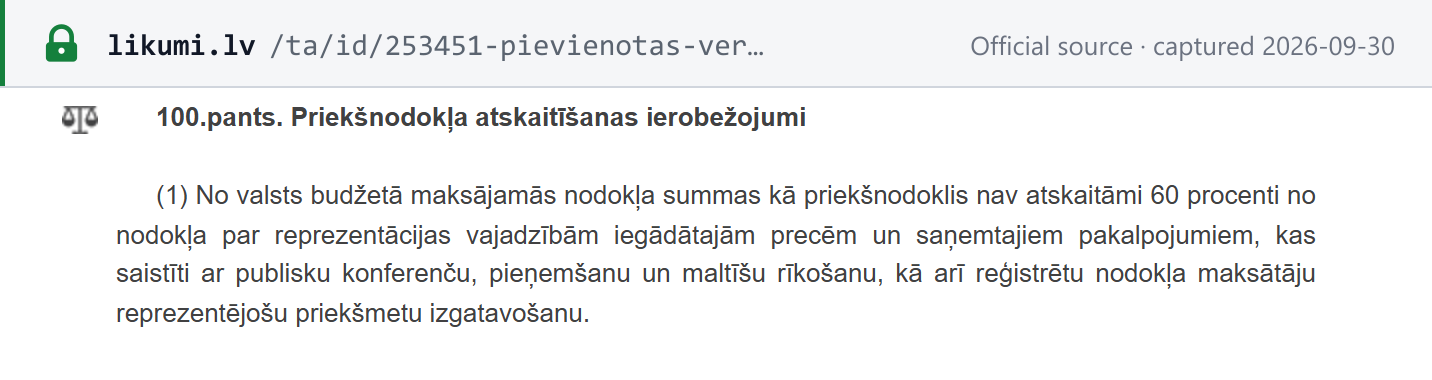
- 60% non-deductible on goods and services bought for representation — public conferences, receptions, meals and representational items (s.100(1));
- 100% blocked on buying, leasing or importing a car (up to 8 passenger seats, or an N1 van up to 3,000 kg with more than 3 seats) that counts as a representative car under corporate income tax rules, and on its running costs, for 60 months (s.100(1¹));
- 50% non-deductible on other passenger cars and their running costs (s.100(2)), except taxis, rental cars, cars held for trade, freight, driving schools, security, emergency vehicles, dealer demonstration cars, and cars used for taxable transactions with GPS trip logs (s.100(3)–(4)); fuel for these excepted cars is capped at the manufacturer's urban consumption plus 20% (s.100(5)).
Refunds
- Resident businesses. VID refunds a confirmed overpayment within 30 days of the return due date (or of a late or corrected filing), after offsetting other tax debts (s.109(1)). [1]
- Bad-debt relief. A supplier may reduce the VAT it paid on a bad debt of under EUR 1,000 excluding VAT per customer, arising in the last three years, where the VAT was declared, the debt was written off, the parties are unrelated, supplies stopped at least three months earlier and the claim was not assigned. The customer is notified and reverses its deduction (s.105(2)–(5)). [1]
- Non-established businesses. EU businesses reclaim Latvian VAT under the electronic procedure of Directive 2008/9/EC (s.113); non-EU businesses under s.112, which implements the 13th Directive (86/560/EEC). The conditions for non-EU claimants are not covered here. [1]
Exemptions
Exempt supplies
Section 52(1) exempts, among others: universal-service postal items; listed medical and dental-technician services; human organs, blood and breast milk; social care; pre-school and state-recognised education and private tuition; certain sports fees and children's camps; theatre, concerts, recognised museums and libraries; authors' and performers' royalties; insurance (point 20) and financial services such as credit, guarantees, accounts, payments and securities (point 21); fund management (point 22); gambling and lotteries (point 23); sale of used real estate — new buildings and building land stay taxable (point 24); and residential letting to individuals, excluding hotel-type accommodation (point 25). The seller of used real estate may opt to tax (s.144). [1] [3]
Exempt is not zero-rated. Input VAT is deductible only on goods and services used for taxable transactions (s.92(1)). A business making exempt supplies charges no VAT on them and cannot recover the VAT on related costs; a business with both kinds apportions (s.98). Zero-rated supplies — exports and intra-EU supplies of goods — are also free of VAT, but the input VAT is recoverable. One exception: insurance and financial services supplied to customers outside the EU, or directly linked to exports, keep the right to deduct (s.92(2)). Some exempt supplies still count towards the EUR 50,000 threshold — see Registration. [1]
Special regimes
- Cash accounting (s.137) — optional for registered persons whose previous-year transactions did not exceed EUR 100,000 (or who plan to stay within EUR 100,000 on registration); up to EUR 500,000 for fishery and agricultural producers on listed products. The invoice says "naudas līdzekļu uzskaite", and the buyer deducts only once it pays (s.97(3)). [1]
- Farmers' flat-rate compensation (s.135). [1]
- Margin schemes — travel agents (s.136) and second-hand goods, works of art and antiques (s.138). [1]
- Investment gold (s.139). [1]
- Domestic reverse charge sectors (ss.141–143⁴) — see Cross-border rules. [1]
- EU cross-border SME scheme for Latvian businesses exempt in other member states (s.139¹). [1]
- Free zones and customs warehouses — services and supplies of goods not in free circulation are zero-rated (ss.43–46). [1] [3]
Offences and penalties
Latvia separates criminal offences under the Criminal Law (Krimināllikums) from the administrative fines, penalties and interest set by the law On Taxes and Fees (Par nodokļiem un nodevām) and the VAT Law.
Offences
| Offence | Conduct | Sanction |
|---|---|---|
| Tax evasion (Criminal Law s.218(2)–(3)) | Evading tax, or hiding or reducing taxable income or other objects, causing loss to the state or a municipality in a large amount | Up to 4 years' imprisonment; up to 10 years for an organised group |
| Fictitious VAT transaction (s.218¹(1)) | Reporting in a VAT return a transaction that did not take place, where its value reaches a large amount | Up to 2 years' imprisonment |
| — causing substantial loss (s.218¹(2)) | Up to 5 years | |
| — causing large loss, or by an organised group (s.218¹(3)) | Up to 10 years |
"Large amount" means at least the total of 50 minimum monthly wages at the time of the offence (Law on the Entry into Force and Application of the Criminal Law, s.20). Both sections were last amended by the law of 19 March 2026, in force 16 April 2026. [15] [16]
Administrative offences. Failure to register in a taxpayer register on time is fined with a warning or 10–70 fine units (EUR 50–350) for a legal person, 10–42 units for an individual (On Taxes and Fees s.136); administrative tax evasion with 28–400 units, plus a possible ban on board members holding office for up to three years (s.135); cash-register violations, such as not installing or using a certified device, with up to 28–280 units for a legal person (s.140). Unlawful invoicing: where a person unlawfully issues a tax invoice or collects VAT it is not entitled to, VID recovers the VAT and levies a penalty of 100% of it (PVN likums s.146(2)). No separate fine for a lawful but defective invoice appears in ss.135–144 of the law On Taxes and Fees. [13] [1]
Penalties
Administrative fines are set in fine units: "Viena naudas soda vienība ir pieci euro" — one fine unit is five euro (Administrative Liability Law s.16(2)). [14]
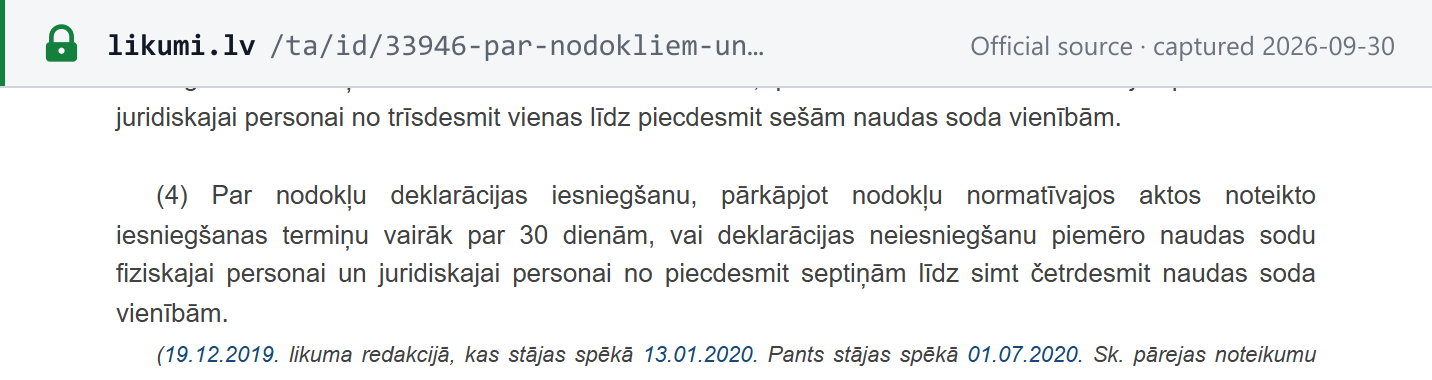
- Late VAT return (On Taxes and Fees s.141). The first lateness of up to five days in 12 months, for monthly or quarterly returns filed through EDS, is not fined. Otherwise: [13]
| Days late | Fine |
|---|---|
| 3–10 | Warning or 5–14 units (EUR 25–70) |
| 11–20 | 15–30 units (EUR 75–150) |
| 21–30 | 31–56 units (EUR 155–280) |
| More than 30, or not filed | 57–140 units (EUR 285–700) |
- Late informative declaration (for example an annex filed separately): warning or 3–30 units (s.142). [13]
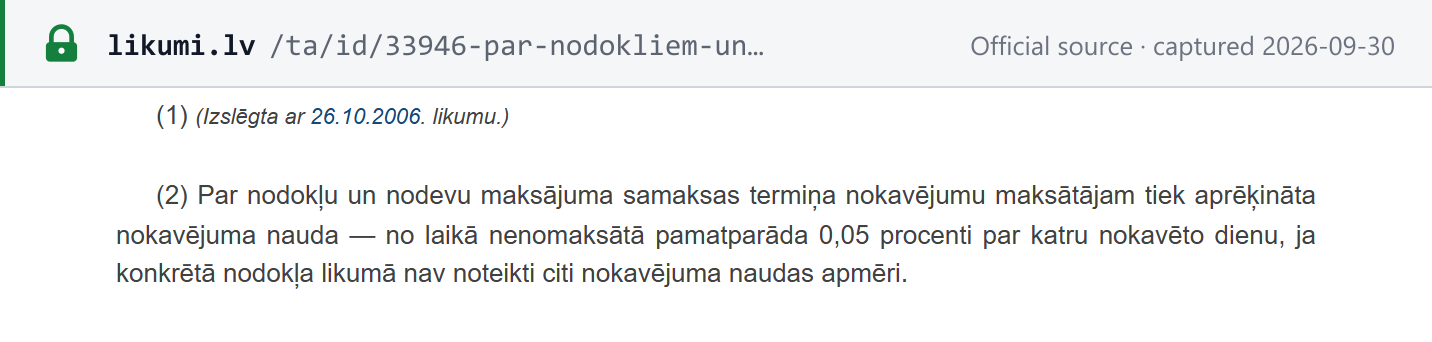
- Late-payment interest (nokavējuma nauda): 0.05% of the unpaid principal for each day late (s.29(2)) — about 18.25% a year. For taxes paid into the single tax account it is calculated twice a month, on the 1st and the 15th (s.29(2¹)), and none is charged if payment arrives by the last day of the month in which it fell due (s.29(2²)(1)). [13]
- Understatement found in an audit: 20% of the understated tax (or overstated refund) where it is no more than 15% of the tax due, 30% above that (s.32(4)–(5)); halved for a first offence by a taxpayer who filed and paid on time and cooperated (s.32(7)), doubled for a repeat within three years (s.32⁴). [13]
- VAT-specific penalties (PVN likums s.146): 100% of VAT unlawfully invoiced or collected (s.146(2)); 10% of import VAT not reported under the deferral regime (s.146(3)); 10% of unpaid self-assessed VAT on intra-EU acquisitions or services received (s.146(4)). [1]
Frequently asked questions
We are an EU company selling in Latvia below EUR 50,000 a year — do we need a Latvian VAT number?
Not necessarily. Since 1 January 2025, section 61(11) of the VAT Law lets a taxable person established in another EU member state use Latvia's EUR 50,000 registration threshold and the EUR 5,000 tolerance on the same terms as a Latvian business. Section 61(12) switches that right off if the business's total supplies across the EU, excluding VAT, exceeded EUR 100,000 in the current or previous calendar year. A business established outside the EU has no threshold at all: it registers before its first taxable supply in Latvia unless the customer accounts for the VAT under the reverse charge. [1]
Do exempt real-estate or financial sales count towards Latvia's EUR 50,000 threshold?
Yes, since 1 January 2025. Section 59(2) of the VAT Law counts taxable supplies plus the exempt insurance, financial, fund-management, real-estate sale, residential letting and statutory land-use transactions listed in section 52(1) points 20, 21, 22, 24, 25 and 26. Sales of fixed and intangible assets, and exempt transactions that are only incidental to the business, are left out (section 59(3)). [1]
Which bread, milk and poultry gets Latvia's 12% VAT rate, and until when?
From 1 July 2026 until 30 June 2027 only, under transitional provision 48 of the VAT Law. Annex 2 lists bread (including gluten-free, frozen and flatbreads, but not croissants, buns, pies, rusks, crackers or breadcrumbs), fresh, sterilised or pasteurised cow's, sheep's or goat's milk including lactose-free milk (not UHT, condensed or evaporated milk), fresh or chilled poultry meat and offal (not frozen), and eggs in shell. Unless the law is amended, these goods return to 21% on 1 July 2027. Fresh fruit, berries and vegetables are a separate, permanent 12% item, in place since 1 January 2024. [1] [8]
Do we have to send structured e-invoices to other Latvian businesses now?
Not yet. Under transitional provision 8 of the Accounting Law, as amended by the law of 5 June 2025, structured e-invoices between Latvian-registered businesses become mandatory from 1 January 2028; until then B2B use is voluntary. Invoices to and from state and municipal bodies (B2G, G2G, G2B) have had to be structured e-invoices since 1 January 2025, and since 1 January 2026 their data must be sent to the State Revenue Service within five working days of sending. [10] [12]
Why was our input VAT deduction rejected in Latvia?
Two common reasons. First, timing: section 97(1) of the VAT Law allows input VAT to be deducted in the period in which the goods or services and the invoice are received, but no later than the following tax period. Second, blocked costs: section 100 makes 60% of the VAT on representation costs and 50% of the VAT on most passenger cars and their running costs non-deductible, and blocks 100% on representative cars. The buyer must also check that the supplier is on the VAT register (section 92(6)). [1]
What does it cost to file a Latvian VAT return late?
Fines are set in fine units of EUR 5 each. Under section 141 of the law On Taxes and Fees, a return filed 3 to 10 days late attracts a warning or 5 to 14 units (EUR 25 to 70); 11 to 20 days, 15 to 30 units; 21 to 30 days, 31 to 56 units; and more than 30 days late or not filed, 57 to 140 units (EUR 285 to 700). The first lateness of up to five days in 12 months is not fined. Unpaid VAT also attracts late-payment interest of 0.05% of the unpaid amount per day (section 29). [13] [14]
Important websites
| Site | Purpose |
|---|---|
| VID Electronic Declaration System (EDS) | VAT registration applications, VAT returns and annexes, EC sales lists, e-invoice data uploads |
| VID — EDS information (EN) | How to access EDS, including login options for foreign users |
| VID — Value Added Tax (EN) | Registration guidance and forms, including for non-residents; reverse charge; OSS and IOSS |
| VID — VAT payer register | Check whether a Latvian VAT number is registered (enter the 11 digits without "LV") |
| VIES | EU VAT-number check |
| VID — VAT rates | Current rate table, with tax periods and exempt supplies |
| VID — E-invoices | E-invoicing timeline, channels, service-provider list |
| Ministry of Finance — Structured e-invoice | Background on the e-invoicing reform |
| Latvija.gov.lv | State portal hosting the official electronic address (e-adrese) used as an e-invoice channel |
| likumi.lv — VAT Law | Official consolidated text of the PVN likums |
Also see Lookuptax's own Latvia PVN number validator.
Recent changes
- 2026-07-01 — 12% VAT on bread, milk, fresh poultry meat and eggs, applying until 30 June 2027 (PVN likums s.42(16)(2), transitional provision 48). (Saeima) — see event
- 2026-01-01 — The 5% rate on books and periodicals limited to publications in Latvian, Latgalian, Livonian and listed EU, EEA, Swiss, EU-candidate and OECD languages (s.42(5), (7)). (likumi.lv)
- 2026-01-01 — E-invoice data for G2G, B2G and G2B invoices must be sent to VID within five working days (Cabinet Regulation 749; for invoices to budget institutions, Accounting Law transitional provision 10). (VID)
- 2025-06-12 — Mandatory B2B e-invoicing moved from 1 January 2026 to 1 January 2028 (law of 5 June 2025 amending the Accounting Law). (likumi.lv)
- 2025-01-01 — Threshold base widened to include listed exempt supplies, EUR 5,000 tolerance introduced, and EU businesses allowed to use the EUR 50,000 threshold (law of 12 December 2024); structured e-invoices mandatory for B2G, G2G and G2B. (likumi.lv)
- 2024-01-01 — Fresh fruit, berries and vegetables moved from 5% to 12% (law of 7 December 2023). (likumi.lv)
Ahead — scheduled changes that have not yet taken effect:
- 2027-07-01 — The temporary 12% rate on bread, milk, fresh poultry and eggs ends; these goods return to 21% unless the law is amended (transitional provision 48). (likumi.lv)
- 2028-01-01 — Structured e-invoices mandatory between Latvian-registered businesses, with data sent to VID (Accounting Law transitional provisions 8 and 10). (VID)
For the full chronology, see Latvia tax changes on Lookuptax.
Reference links
- likumi.lv — Value Added Tax Law (Pievienotās vērtības nodokļa likums), consolidated
- likumi.lv — VAT Law as in force on 31 December 2023
- likumi.lv — VAT Law as in force on 31 December 2024
- likumi.lv — VAT Law as in force on 31 December 2025
- likumi.lv — Accounting Law (Grāmatvedības likums)
- likumi.lv — Cabinet Regulation No. 749 of 9 December 2025 on e-invoice circulation and reporting
- likumi.lv — Law On Taxes and Fees (Par nodokļiem un nodevām)
- likumi.lv — Administrative Liability Law
- likumi.lv — Criminal Law (Krimināllikums)
- likumi.lv — Law on the Entry into Force and Application of the Criminal Law
- State Revenue Service — Value Added Tax (EN)
- State Revenue Service — VAT rates
- State Revenue Service — VAT payers
- State Revenue Service — E-invoices
- State Revenue Service — Electronic Declaration System (EN)
- Saeima — VAT will be reduced for certain food products
- Ministry of Economics — Reduced VAT on food
- Ministry of Finance — Structured electronic invoice
- Lookuptax — Latvia TIN and PVN number guide
- Lookuptax — How to verify an EU VAT number in VIES
- Lookuptax — EU VAT SME scheme
- Lookuptax — E-invoicing status and networks worldwide
- Lookuptax — VAT registration thresholds worldwide
- Lookuptax — Worldwide tax rates