India GST guidelines
| FACTSHEET | |
|---|---|
| Country code | IN |
| Tax name | Goods and Services Tax (GST) — माल और सेवा कर |
| Tax Authority | Central Board of Indirect Taxes and Customs (CBIC) and the State tax administrations |
| Rates (IGST) | 18% standard, 5% merit, 40% de-merit; special rates 3%, 1.5% and 0.25% (Notification 9/2025-CT(Rate), from 22 September 2025) |
| Registration threshold | ₹20 lakh (₹10 lakh in four States); ₹40 lakh for suppliers of goods only in most States; nil for non-residents |
| Tax number | GSTIN — 15 characters, PAN-based, one per State |
| E-invoicing | Mandatory on the IRP above ₹5 crore aggregate turnover; scope widens 1 January 2027 |
Overview
India's indirect tax is GST — Goods and Services Tax (Hindi: माल और सेवा कर, the form the GST Council uses for itself — "माल और सेवा कर परिषद"). It replaced VAT, central excise, service tax and a range of other levies from 1 July 2017; the CGST Act's registration provisions came into force on 22 June 2017 (CBIC — CGST Act s.22). It is administered by the Central Board of Indirect Taxes and Customs (CBIC) for the central and integrated taxes, together with the State tax administrations. Rates are set by Central Government notification "on the recommendations of the Council" — the GST Council.
- Currency: Indian rupee (₹, INR). Indian legislation writes amounts in lakh (1 lakh = ₹100,000) and crore (1 crore = ₹10,000,000); this guide gives both forms on first use.
- Financial year: 1 April to 31 March. Registration thresholds are tested on turnover "in a financial year", invoice serial numbers must be "unique for a financial year", and the annual return runs on the same year.
GST is one tax collected under three heads, and which head applies depends on where the supply goes. This is the single thing to get right before reading any rate below — the same 18% supply is billed as 9% + 9% or as 18%, depending on the direction of travel:
| Head | Levied by | Applies to |
|---|---|---|
| CGST — Central GST | Centre | The central half of an intra-State supply |
| SGST / UTGST — State / Union Territory GST | State or UT | The State half of the same intra-State supply |
| IGST — Integrated GST | Centre, then apportioned to the destination State | Inter-State supplies, imports, and supplies to or from an SEZ |
A supply within one State attracts CGST + SGST at half the headline rate each; a supply crossing a State line attracts IGST at the full rate. The rate notifications run in parallel: Notification 9/2025-Central Tax (Rate) sets CGST at 9% for Schedule II goods, and its integrated-tax twin sets IGST at 18% for the same goods. Compensation cess, historically charged on top for a narrow set of goods, has been withdrawn in full since 1 February 2026 — see Rates.
Registration follows the same logic: it is PAN-based and State-specific, so a business operating in four States holds four GSTINs against one PAN, and each is a separate taxable person to the others.
Registration
Section 22(1) of the CGST Act makes "every supplier" liable to register "in the State or Union territory … from where he makes a taxable supply of goods or services or both" once its aggregate turnover crosses the threshold. Registration is therefore per State: a person registered in one State is an unregistered person in every other. A unit in a Special Economic Zone, or an SEZ developer, "shall have to apply for a separate registration, as distinct from his place of business located outside the Special Economic Zone in the same State" (section 25(1) proviso) (CBIC — CGST Act s.25). There is no centralised registration covering units in several States.
Who should register
The threshold depends on what you supply and in which State. Thresholds as at 4 November 2026:
| Supplier | Threshold — aggregate turnover in a financial year | Legal basis |
|---|---|---|
| Services, or goods and services — most States and UTs | ₹20 lakh (₹2 million) | CGST Act s.22(1) |
| Services, or goods and services — Manipur, Mizoram, Nagaland, Tripura | ₹10 lakh (₹1 million) | s.22(1) first proviso; Explanation (iii) |
| Goods only — States that adopted the higher limit | ₹40 lakh (₹4 million), from 1 April 2019 | Notification 10/2019-Central Tax, 7 March 2019 |
| Goods only — Arunachal Pradesh, Meghalaya, Puducherry, Sikkim, Telangana, Uttarakhand | ₹20 lakh | s.22(1); 10/2019-CT clause (iii) |
| Goods only — Manipur, Mizoram, Nagaland, Tripura | ₹10 lakh | s.22(1) first proviso; 10/2019-CT clause (iii) |
| Suppliers of ice cream, pan masala or tobacco (the goods listed in 10/2019-CT) | ₹40 lakh relief does not apply — ₹20 lakh, or ₹10 lakh in the four States above | 10/2019-CT clause (b) |
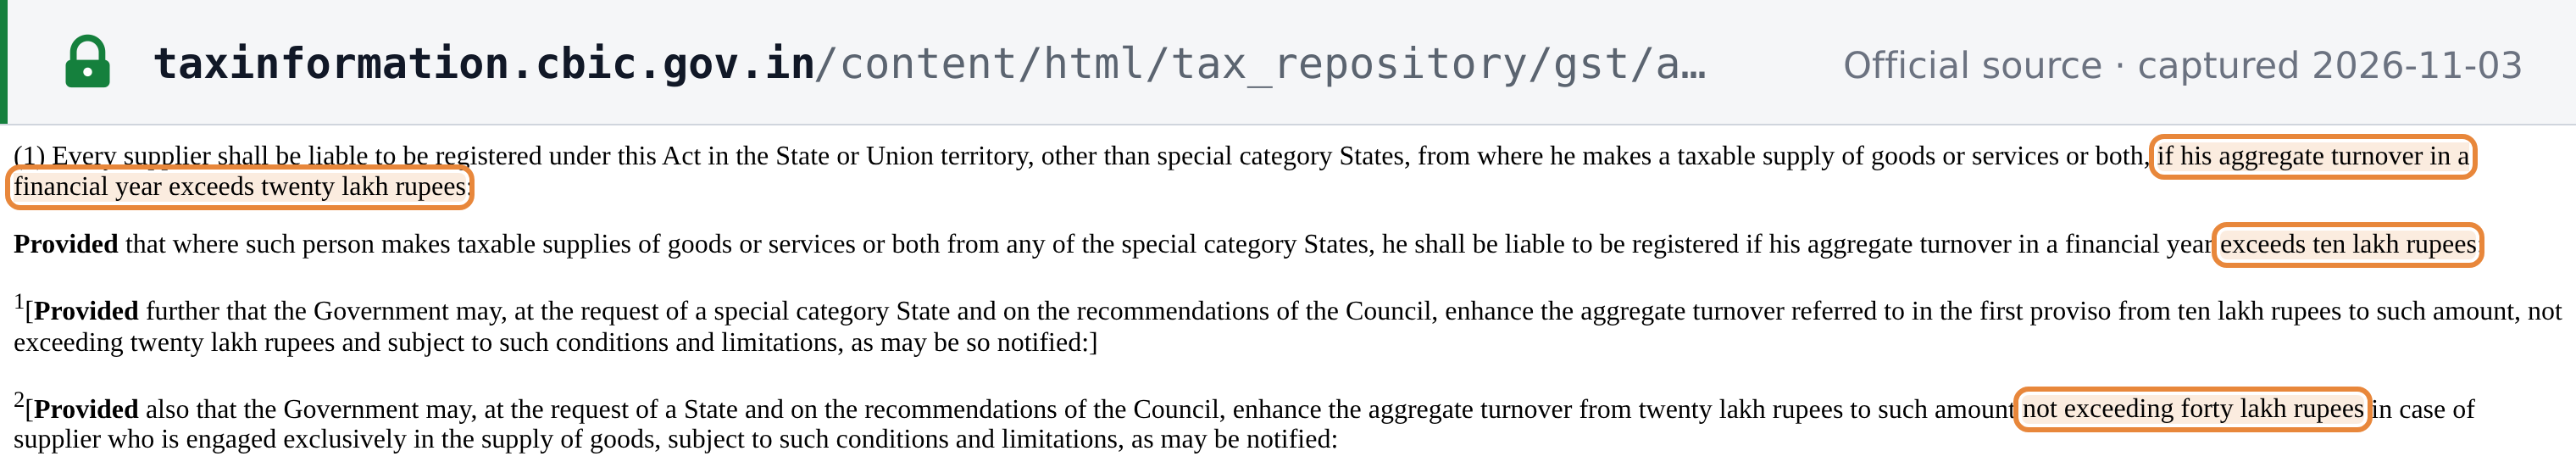
Section 22(1) sets the general limit — "if his aggregate turnover in a financial year exceeds twenty lakh rupees" — and its first proviso lowers it for the special category States: such a person "shall be liable to be registered if his aggregate turnover in a financial year exceeds ten lakh rupees". Explanation (iii) defines special category States by reference to Article 279A(4)(g) of the Constitution, but "except the State of Jammu and Kashmir" and "States of Arunachal Pradesh, Assam, Himachal Pradesh, Meghalaya, Sikkim and Uttarakhand", which leaves Manipur, Mizoram, Nagaland and Tripura on the ₹10 lakh line. A third proviso, in force from 1 January 2020, lets the Government raise the limit to "not exceeding forty lakh rupees" for suppliers "engaged exclusively in the supply of goods" (CBIC — CGST Act s.22).
 Source snapshot captured 2026-11-03 — original
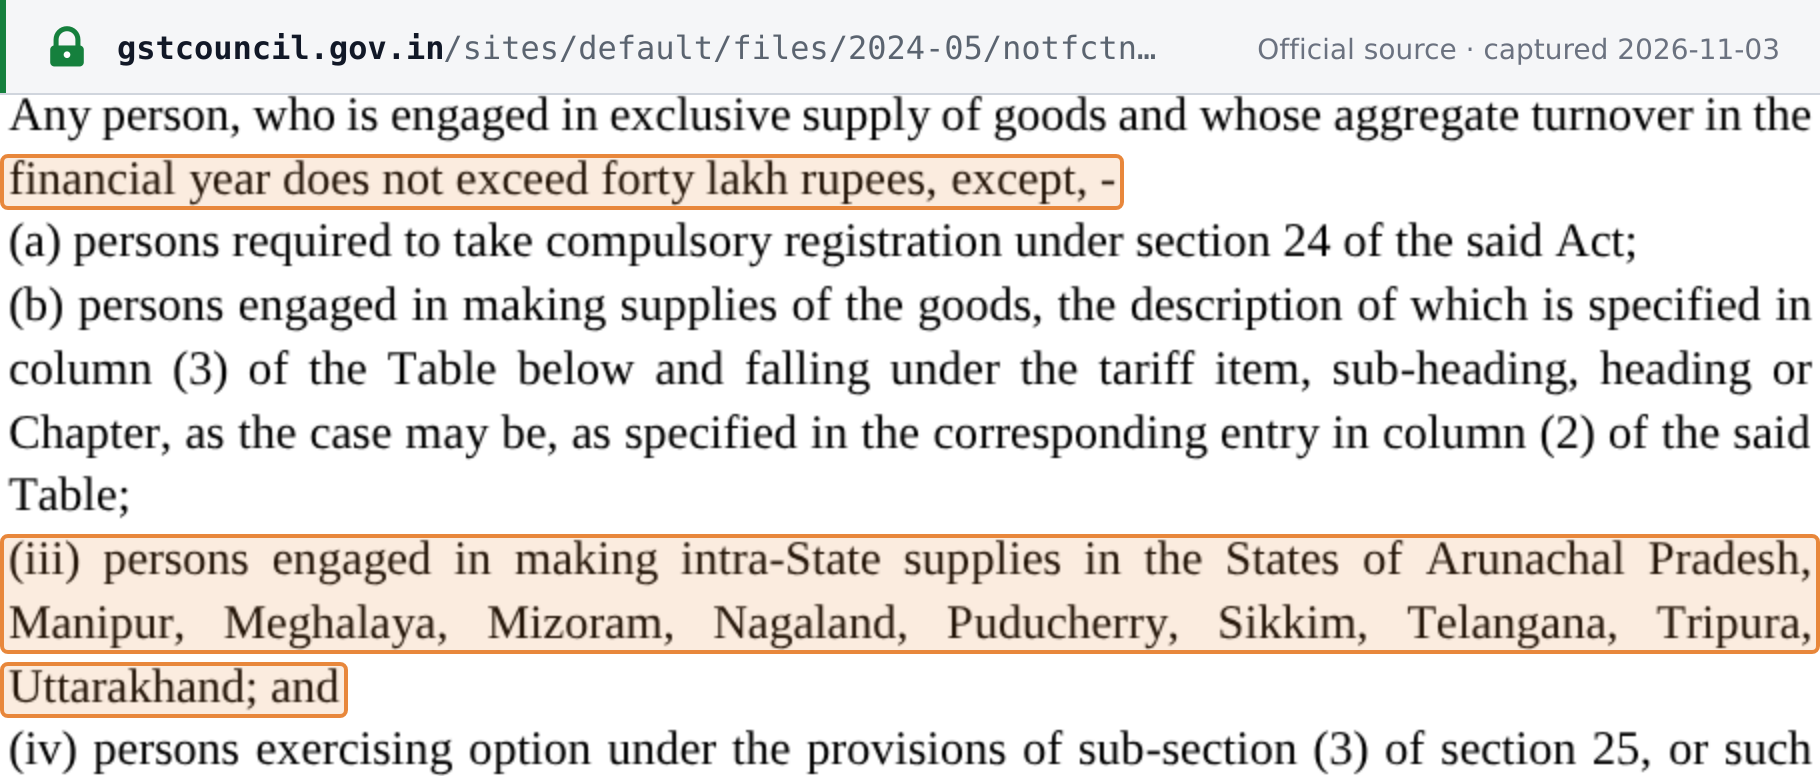
The ₹40 lakh limit for goods itself comes from Notification 10/2019-Central Tax (7 March 2019, in force 1 April 2019), issued under section 23(2), which lets the Government exempt categories of persons from registration: "Any person, who is engaged in exclusive supply of goods and whose aggregate turnover in the financial year does not exceed forty lakh rupees" is exempt from registration, except persons liable under section 24, suppliers of the listed goods, "persons engaged in making intra-State supplies in the States of Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Puducherry, Sikkim, Telangana, Tripura, Uttarakhand", and voluntary registrants (GST Council — Notification 10/2019-CT).
 Source snapshot captured 2026-11-03 — original
The threshold is tested on aggregate turnover, which is PAN-wide and all-India — it adds up taxable, exempt, export and inter-State supplies across every State, and is not limited to the State you are asking about. A business under the threshold in one State can still be liable there because of turnover elsewhere.
Registration with no threshold at all
Section 24 of the CGST Act makes registration compulsory regardless of turnover — "Notwithstanding anything contained in sub-section (1) of section 22" — for a list of categories (CBIC — CGST Act s.24). The ones that most often catch foreign and online businesses:
- Non-resident taxable persons (NRTP) making any taxable supply in India (clause (v)).
- Persons supplying OIDAR services from outside India "to a person in India, other than a registered person" (clause (xi)). Where the Indian customer is registered, the customer accounts for the tax under reverse charge instead — see Cross-border rules.
- Casual taxable persons — occasional supplies in a State where you have no fixed place of business (clause (ii)).
- Persons liable under reverse charge (clause (iii)), e-commerce operators required to collect tax at source (clause (x)), and suppliers selling through such operators (clause (ix)).
- Persons making any inter-State taxable supply (clause (i)). Exemption notifications under the IGST Act relieve some small inter-State suppliers of services from this; check the current notification before relying on the threshold for inter-State services.
There is no separate "non-resident threshold" — it is nil. A non-resident taxable person or an overseas OIDAR supplier to unregistered customers registers on the first rupee.
Voluntary registration
A person below the threshold may register voluntarily under section 25(3), and is then treated as a registered person with the full set of obligations — returns, invoices, the lot. Notification 10/2019-CT expressly keeps "persons exercising option under the provisions of sub-section (3) of section 25" outside the ₹40 lakh exemption. The usual reason is input tax credit: an unregistered supplier cannot pass credit to registered customers, which makes it commercially unattractive to sell B2B.
Deregistration
Registration is cancelled under section 29, either on application or by the officer — on closure of business, transfer, amalgamation, a change of constitution, or where the person is no longer liable to be registered; an officer may also cancel for prolonged non-filing or registration obtained by fraud. From 1 November 2026 a new Rule 20 tightens the application route (Notification 05/2026-Central Tax, 26 October 2026): the person "shall within a period of thirty days from the occurrence of the event warranting the cancellation submit an application in FORM GST REG-16" (the 30-day limit does not apply on the death of a sole proprietor), and no application may be filed until all returns due — including CMP-08 statements — are filed and GSTR-3B is filed for every period whose GSTR-1 or IFF has been filed (CBIC — Notification 05/2026-CT). A final return in FORM GSTR-10 is due "within three months of the date of cancellation or date of order of cancellation, whichever is later" (section 45) (CBIC — CGST Act s.45). Cancellation does not extinguish liability for anything owed before it.
Group registration
Not available in India. The CGST Act, as consolidated by CBIC, contains no VAT-grouping provision of the kind found in the UK or Singapore — no facility to treat related entities as a single taxable person, and intra-group supplies between distinct persons are taxable. Section 25(2) goes the other way: it allows a person to take separate registrations for multiple places of business within a State.
Where and how to register
Register on the GST portal — Services > Registration > New Registration.
- Forms. A resident business applies in FORM GST REG-01. A non-resident taxable person applies in FORM GST REG-09 and must apply "at least five days prior to the commencement of business" (section 25(1) proviso), with an advance deposit of tax for the period of registration. An overseas OIDAR supplier applies in FORM GST REG-10.
- Timeline. Under Rule 9(1) the officer approves "within a period of seven working days from the date of submission of the application"; where Aadhaar authentication fails or is not opted for, or the application is risk-flagged, "the registration shall be granted within thirty days of submission of application, after physical verification of the place of business". If the officer neither approves nor raises a query in FORM GST REG-03 in time, the application "shall be deemed to have been approved" (CBIC — CGST Rule 9). The 30-day path is the one most non-residents land on.
- Fast-track rules from 1 November 2025 (Notification 18/2025-Central Tax, 31 October 2025). Rule 9A: applicants identified "based on data analysis and risk parameters" are granted registration electronically "within three working days". Rule 14A: an applicant whose output tax on supplies to registered persons "does not exceed two lakh and fifty thousand rupees per month" may opt for electronic registration, subject to Aadhaar authentication (CBIC — Notification 18/2025-CT).
- E-commerce sellers, from 1 November 2026 — Rule 14B (Notification 05/2026-CT). A person already registered in one State may register "in any other State or Union territory where the person has no physical presence, by declaring a warehouse, of an electronic commerce operator" as principal place of business, subject to the same ₹2.5 lakh-a-month cap on output tax to registered persons.
Tax registration number — GSTIN
A registered person receives a 15-character GSTIN: a two-digit State code, the 10-character PAN, an entity code for the number of registrations under that PAN in the State, the letter "Z" by default, and a check character. Registration is not tax-specific — one GSTIN covers CGST, SGST/UTGST and IGST. Overseas OIDAR suppliers receive a GSTIN with a special State code. For the full structure, checksum and worked examples, see the India GSTIN tax identification number guide; to check a counterparty's GSTIN, see how to verify a GSTIN.
Rates
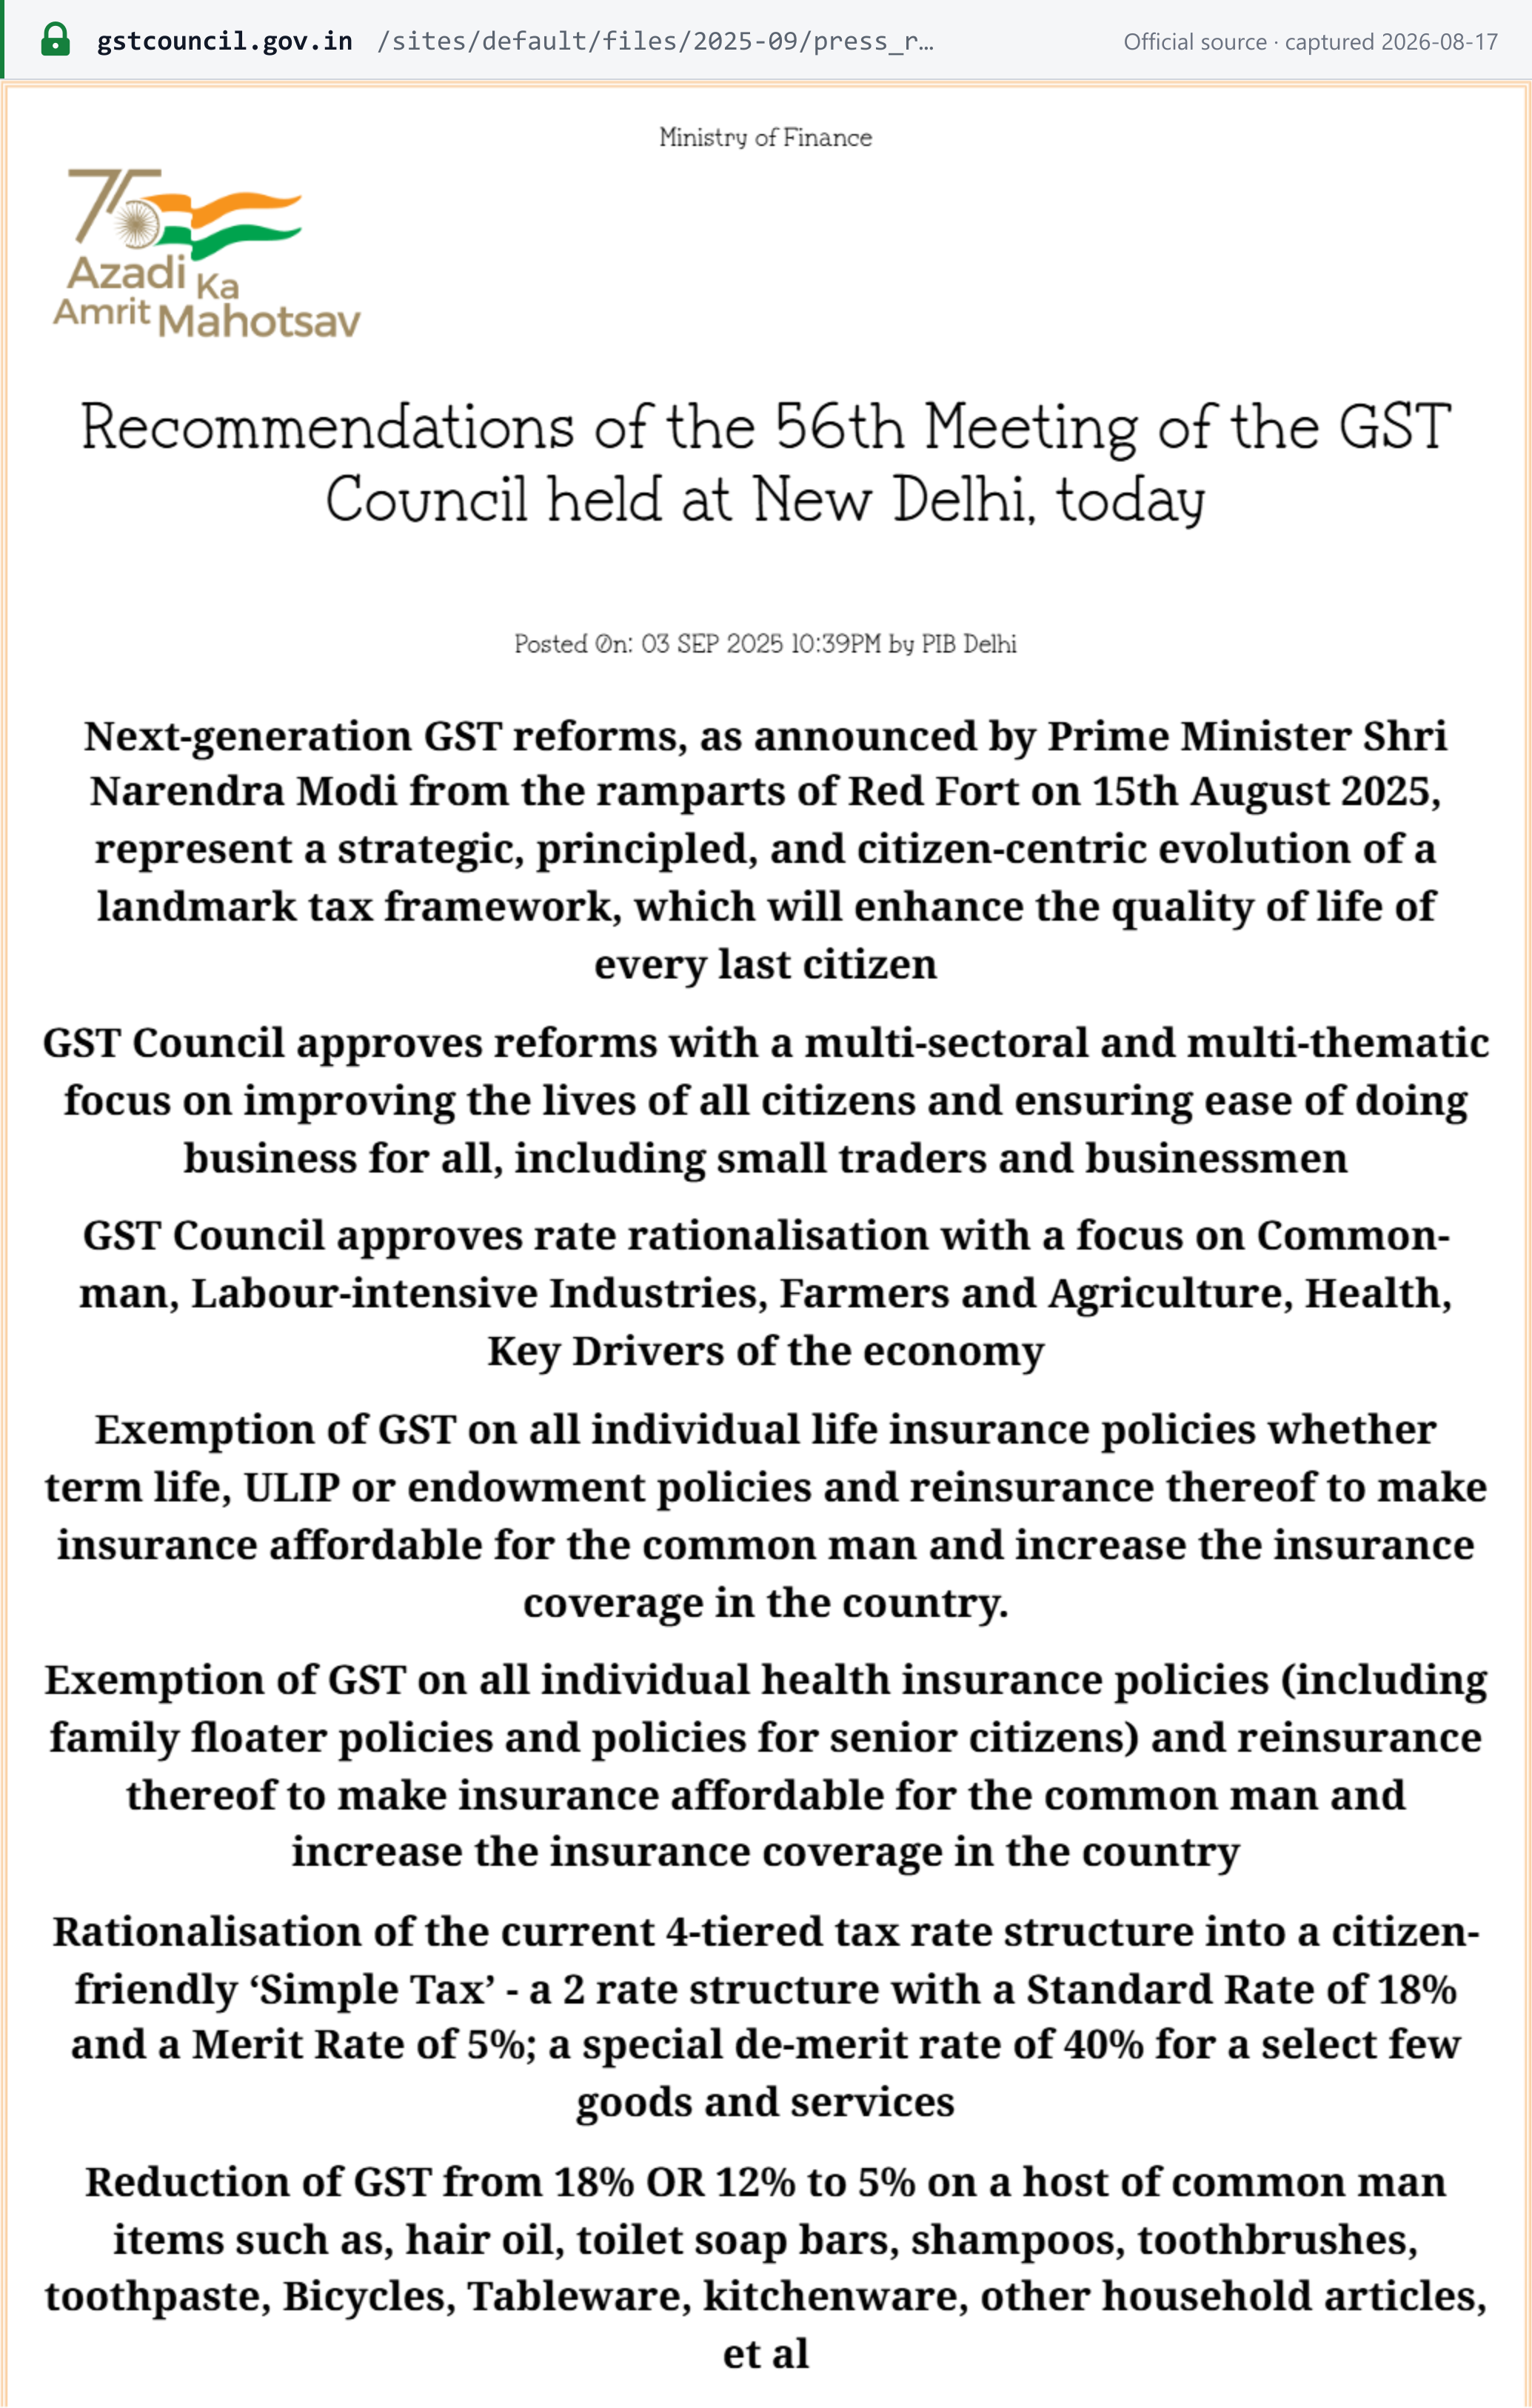
The slab structure changed on 22 September 2025. The 56th GST Council (3 September 2025) recommended "Rationalisation of the current 4-tiered tax rate structure into a citizen- friendly 'Simple Tax' - a 2 rate structure with a Standard Rate of 18% and a Merit Rate of 5%; a special de-merit rate of 40% for a select few goods and services". The changes applied from 22 September 2025 to services and to "all goods except pan masala, gutkha, cigarettes, chewing tobacco products like zarda, unmanufactured tobacco and bidi" (GST Council — PIB release on the 56th meeting). The 12% and 28% slabs no longer exist.
 Source snapshot captured 2026-08-17 — original
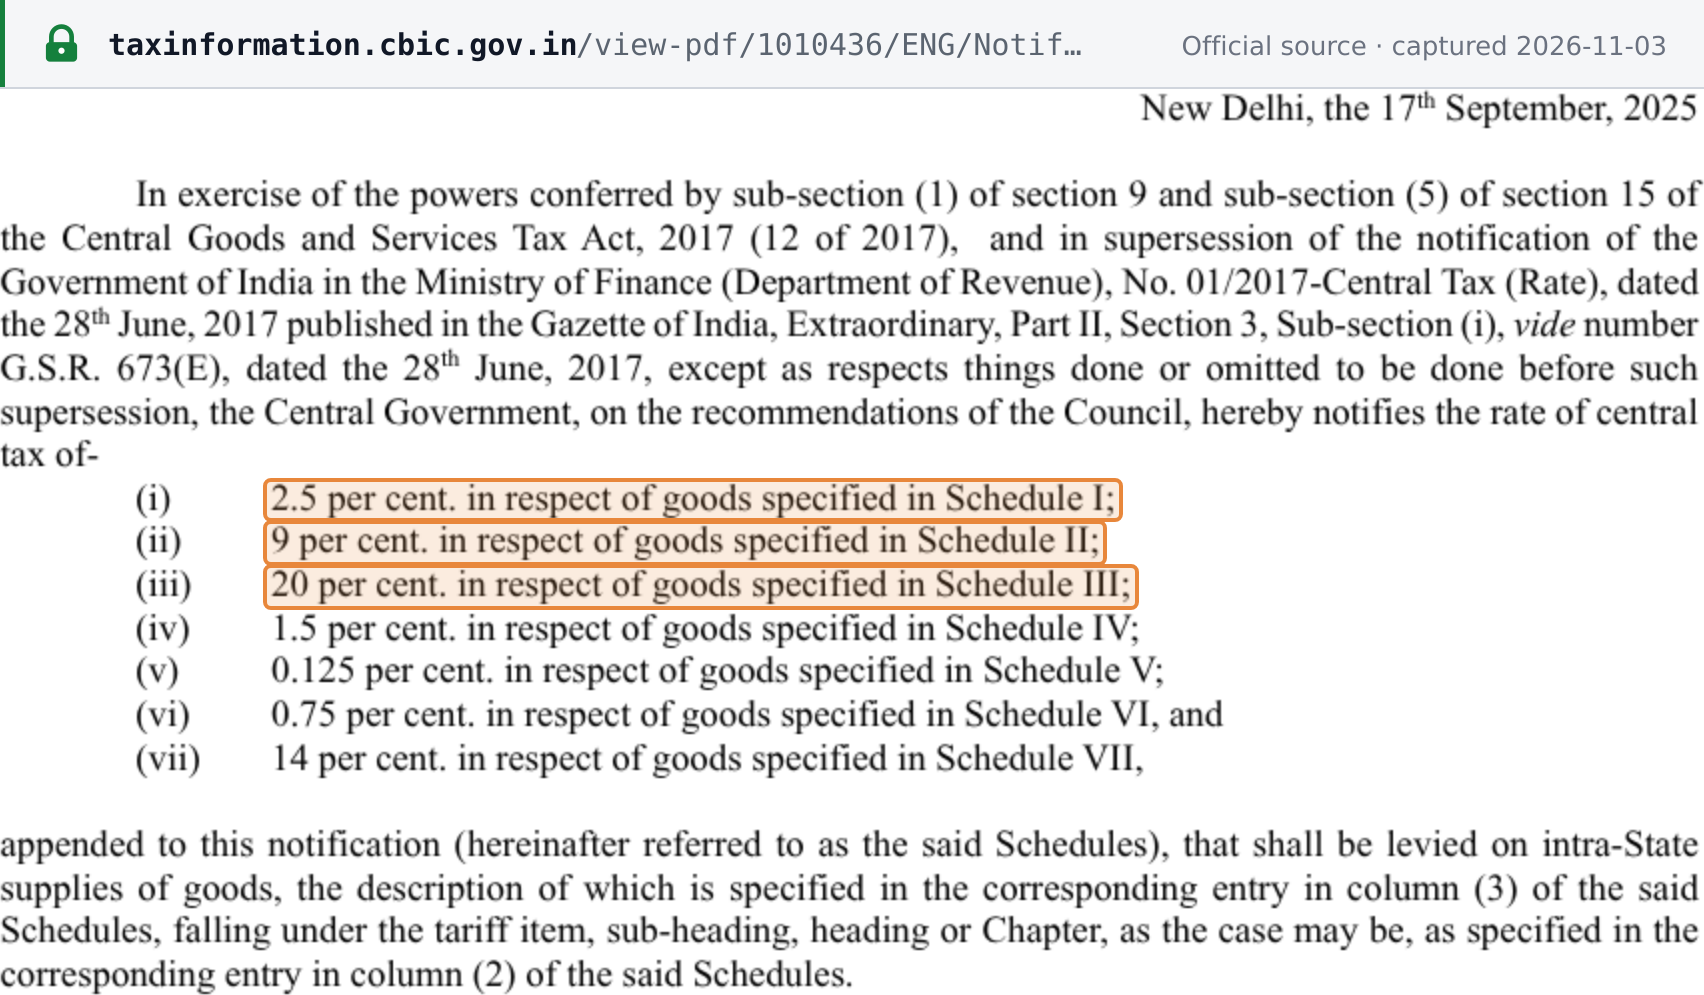
For goods, the operative instrument is Notification 9/2025-Central Tax (Rate), dated 17 September 2025 and in force from 22 September 2025, which superseded Notification 1/2017-CT(Rate). It sets the central tax rate at "(i) 2.5 per cent. in respect of goods specified in Schedule I; (ii) 9 per cent. … Schedule II; (iii) 20 per cent. … Schedule III; (iv) 1.5 per cent. … Schedule IV; (v) 0.125 per cent. … Schedule V; (vi) 0.75 per cent. in respect of goods specified in Schedule VI, and (vii) 14 per cent. in respect of goods specified in Schedule VII" (CBIC — Notification 9/2025-CT(Rate)). Schedule VII, the old 28% band kept for tobacco during the transition, was omitted from 1 February 2026 by Notification 19/2025-CT(Rate) of 31 December 2025, which moved pan masala and tobacco into Schedule III (40%) and biris into Schedule II (18%) (CBIC — Notification 19/2025-CT(Rate)).
 Source snapshot captured 2026-11-03 — original
Reading the table: the IGST column is the headline rate for the supply. The CGST and SGST columns are that same rate split in half for intra-State supplies. An 18% supply is either 9% CGST + 9% SGST, or 18% IGST — never both. Rates as at 4 November 2026:
| CGST (%) | SGST/UTGST (%) | IGST (%) | Applies to — examples | Schedule of 9/2025-CT(Rate) |
|---|---|---|---|---|
| 0 | 0 | 0 | Exempt and nil-rated supplies | Exemption notifications (see Exemptions) |
| 0.125 | 0.125 | 0.25 | Rough or simply sawn diamonds; precious, semi-precious and synthetic or reconstructed stones other than diamonds, whether or not worked | V |
| 0.75 | 0.75 | 1.5 | Cut and worked diamonds (heading 7102 other than Schedule V); worked synthetic or reconstructed diamonds | VI |
| 1.5 | 1.5 | 3 | Gold, silver, platinum, pearls, jewellery, imitation jewellery, coins | IV |
| 2.5 | 2.5 | 5 | Merit rate | I |
| 9 | 9 | 18 | Standard rate — including biris from 1 February 2026 | II |
| 20 | 20 | 40 | De-merit rate — aerated and sweetened waters, caffeinated beverages, motor cars above the size limits, motorcycles above 350 cc, yachts, aircraft for personal use, specified actionable claims (betting, casinos, gambling, horse racing, lottery, online money gaming); from 1 February 2026 also pan masala, cigarettes, unmanufactured and other manufactured tobacco | III |
A separate concessional rate for supplies to merchant exporters exists under Notification 40/2017-Central Tax (Rate); it is a concession conditional on export, not a schedule rate.
Services are rated under Notification 11/2017-Central Tax (Rate), as amended by Notification 15/2025-CT(Rate) of 17 September 2025 and later amendments. The 56th Council release gives examples: hotel accommodation up to ₹7,500 per day moved from 12% to 5%, and casinos, race clubs and specified actionable claims from 28% to 40%.
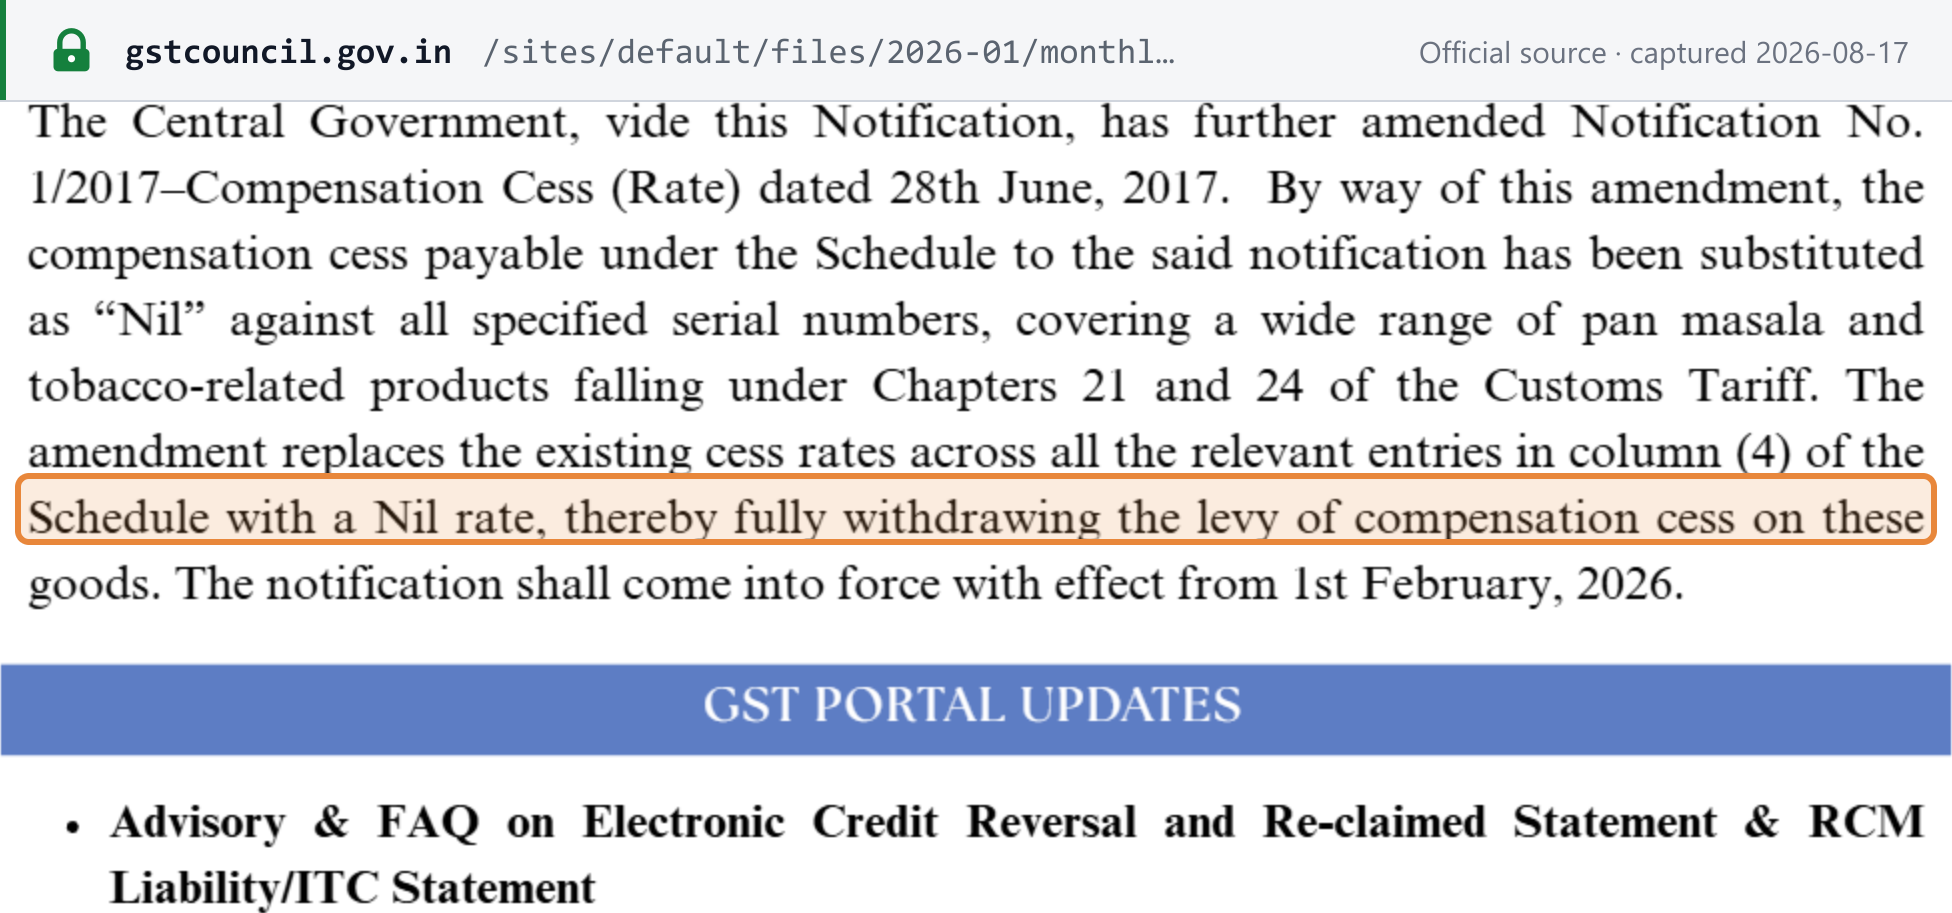
Compensation cess has been set to Nil on the goods it covered. It was withdrawn in two steps. From 22 September 2025, Notification 02/2025-Compensation Cess (Rate) substituted "Nil" for the cess against the listed serial numbers of the cess schedule — the entries other than pan masala and tobacco, which include coal and motor vehicles (CBIC — Notification 02/2025-Cess(Rate)). The 56th Council release separately moved coal from 5% to 18% GST. From 1 February 2026, Notification 03/2025-Compensation Cess (Rate) of 31 December 2025 set the cess to "Nil" against all remaining entries, "thereby fully withdrawing the levy of compensation cess on these goods" (GST Council — newsletter, December 2025).
 Source snapshot captured 2026-08-17 — original
Rate changes since the reform:
- 1 May 2026 — Notification 01/2026-CT(Rate), 30 April 2026, substitutes the beverage tariff-item codes in existing entries of Schedule I (5%, S. Nos. 150–151) and Schedule III (40%, S. Nos. 2–3), following the Customs Tariff changes in the Finance Act, 2026; the rates of those entries do not change (CBIC — Notification 01/2026-CT(Rate)) — see event.
- 1 November 2026 — Notification 02/2026-CT(Rate), 27 October 2026, adds "Retreaded tractor tyres" (heading 4012) to Schedule I at 5% and redefines the organic-fertiliser entry to include sea-weed-extract bio-stimulants (CBIC — Notification 02/2026-CT(Rate)).
Finding the rate for an item. The rate follows the HSN (goods) or SAC (services) classification of the individual supply. Find the code with the GST portal's HSN/SAC search, then read its entry in Notification 9/2025-CT(Rate) for goods or Notification 11/2017-CT(Rate) as amended for services, rather than assuming which of the two main rates applies.
Cross-border rules
Place of supply
GST is destination-based, so the place of supply decides both whether Indian GST applies and which head it is charged under. The rules sit in Chapter V of the IGST Act and differ for goods and services, and again for domestic and cross-border transactions.
Where the supplier or the recipient is outside India, section 13 applies. The default is:
"The place of supply of services except the services specified in sub-sections (3) to (13) shall be the location of the recipient of services" [19]
— with a proviso that where the recipient's location is not available in the ordinary course of business, the supplier's location applies instead. Sub-sections (3) to (13) carve out the usual exceptions: services performed on goods physically made available, services relating to immovable property, admission to events, transport and banking. Intermediary services are no longer among them — section 13(8)(b) was "Omitted by section 157 of The Finance Act, 2026 … with effect from 30.03.2026", so from 30 March 2026 the place of supply for an intermediary falls to the section 13(2) default of the recipient's location, which is what makes those services exportable [19].
Imports
- Goods. Imports are treated as inter-State supplies. IGST is levied on imported goods under section 3(7) of the Customs Tariff Act, 1975, and collected at customs clearance together with basic customs duty, on a value that includes that duty. Credit of the IGST is available to a registered importer; basic customs duty is not creditable and is a cost.
- Services. Import of services for a consideration in the course of business is a supply. Where the recipient is registered in India, the recipient accounts for the tax under reverse charge — see below.
Exports and SEZ supplies
Exports are zero-rated, not exempt, and the distinction is the whole point: a zero-rated supply carries no output tax and preserves the input tax credit behind it. Section 16 of the IGST Act:
"'zero rated supply' means any of the following supplies of goods or services or both, namely:- (a) export of goods or services or both; or (b) supply of goods or services or both for authorised operations to a Special Economic Zone developer or a Special Economic Zone unit." [20]
Two routes, and the choice is a cash-flow decision:
| Route | How it works | Refund claimed |
|---|---|---|
| Under LUT / bond | Supply without paying integrated tax | Refund of unutilised input tax credit |
| On payment of tax | Pay IGST on the export, then reclaim | Refund of the tax paid |
Export invoices must carry the endorsement set out under Mandatory content below, and show the country of destination. For how SEZ units and developers are treated, see Special Economic Zones in India.
Foreign companies selling into India
The answer differs sharply for B2B and B2C, and this is the question most non-resident readers arrive with.
| B2B — recipient is registered in India | B2C — recipient is not registered | |
|---|---|---|
| Services (general) | Reverse charge. Notification 10/2017-Integrated Tax (Rate), serial 1, makes the Indian recipient pay the IGST on "Any service supplied by any person who is located in a non-taxable territory to any person other than non-taxable online recipient". The law places the liability on the recipient. | Reverse charge on the recipient, registered or not. Serial 1 of 10/2017-IT(Rate) names "Any person located in the taxable territory other than non-taxable online recipient" as the person liable; such a recipient must register under CGST s.24(iii). The overseas supplier is not the liable person. For digital services, see OIDAR below. |
| OIDAR / digital services | Reverse charge by the registered recipient. Section 24(xi) does not require an overseas supplier selling only to registered persons to register. A supplier that is registered (because it also sells to unregistered customers) reports these supplies in GSTR-5A as well. | The overseas supplier must register in India and pay IGST. No threshold. |
| Goods | Importer of record pays IGST at customs. | Importer of record pays IGST at customs. |
Sources: GST Council — Notification 10/2017-IT(Rate) as amended to 1 April 2019; CBIC — CGST Act s.24; CBIC — CGST Rule 64.
Reverse charge shifts liability to the recipient. A registered Indian business receiving a service from outside India self-assesses IGST, pays it in cash (not from credit), and then takes credit of it if otherwise eligible. It also issues a self-invoice under section 31(3)(f) of the CGST Act; Rule 47A, in force from 1 November 2024, sets a thirty-day limit for self-invoices by persons liable under section 9(3) or 9(4). From 1 January 2027 these self-invoices — for imports of services and for supplies from unregistered persons under reverse charge — fall within e-invoicing for taxpayers in the e-invoicing class (see E-invoicing status). For the general mechanism, see the reverse charge explainer.
Digital services (OIDAR)
Online Information and Database Access or Retrieval services supplied from outside India are taxed where the customer is. Section 13(12):
"The place of supply of online information and database access or retrieval services shall be the location of the recipient of services." [19]
The recipient is deemed to be in India if any two of seven non-contradictory conditions hold — the address the recipient presents over the internet, billing address, the country of the card used, IP address, bank location, SIM country code, fixed landline location.
The scope widened on 1 October 2023. The Finance Act, 2023 widened the definition of a "non-taxable online recipient". Before that date it covered an unregistered person receiving OIDAR "in relation to any purpose other than commerce, industry or any other business or profession" (GST Council — OIDAR flyer). The substituted section 2(16) of the IGST Act now reads: "'non-taxable online recipient' means any unregistered person receiving online information and database access or retrieval services located in taxable territory" (CBIC — IGST Act s.2). The same Act dropped the requirement that an OIDAR service be "essentially automated and involving minimal human intervention". The practical effect: an overseas supplier of digital services is in scope for every sale to an unregistered person in India, business or consumer, whether or not a human is involved; a registered customer accounts under reverse charge instead. The changes were brought into force by Notification 28/2023-CT, and the return obligation was restated by Notification 51/2023-CT dated 29 September 2023.
 Source snapshot captured 2026-11-03 — original
An overseas OIDAR supplier registers in FORM GST REG-10 and files FORM GSTR-5A monthly, "on or before the twentieth day of the month succeeding the calendar month", reporting supplies to non-taxable online recipients and to registered persons (CGST Rule 64, as substituted by 51/2023-CT). Registering does not require a physical presence. Where the supplier has neither a physical presence nor a representative in India, IGST section 14 says it "may appoint" a person in India for the purpose of paying tax — a permission, not a standing requirement. The full rules — definitions, the two-of-seven test, intermediaries and app stores, and the GSTR-5A mechanics — are in the OIDAR explainer.
Marketplaces and e-commerce operators
An e-commerce operator required to collect tax at source (TCS) under section 52 must register regardless of turnover (section 24(x)), and collects TCS on the net value of taxable supplies made through it by other suppliers. Separately, under section 9(5) of the CGST Act (and section 5(5) of the IGST Act), the operator is treated as the deemed supplier — liable for the whole tax as if it had made the supply itself — for a notified list of services including passenger transport by radio-taxi, accommodation, housekeeping and restaurant services supplied through the platform. For those categories the underlying supplier is out of the loop entirely. From 1 November 2026, Rule 14B lets a seller registered in one State register in other States on the strength of an e-commerce operator's warehouse there (see Where and how to register). See also marketplace deemed-supplier rules.
Invoice requirements
GST law prescribes no invoice template — it prescribes a fixed list of particulars. Get the particulars right and any layout is valid. The rules live in Chapter VI of the CGST Rules, 2017 and sections 31 and 34 of the CGST Act, 2017.
The first decision is which document you owe:
| Document | When it is used | Contents prescribed by |
|---|---|---|
| Tax invoice | Taxable supply of goods or services by a registered person. [2] | Rule 46 [1] |
| Bill of supply | Supply of exempted goods or services, or any supply by a person paying tax under the composition scheme — "a registered person supplying exempted goods or services or both or paying tax under the provisions of section 10 shall issue, instead of a tax invoice, a bill of supply" (s.31(3)(c)). It carries no tax. [2] | Rule 49 [6] |
| Invoice-cum-bill of supply | A single document where taxable and exempt supplies go to the same unregistered person. It must carry the particulars of Rule 46 (or Rule 54) and Rule 49. [7] | Rule 46A [7] |
| Receipt voucher | Advance payment received against a supply. [2] | Rule 50 [16] |
| Refund voucher | Advance was received and a receipt voucher issued, but no supply followed and no invoice was raised. [2] | Rule 51 [17] |
| Payment voucher | Issued at the time of paying a supplier where the recipient is liable under reverse charge. [2] | Rule 52 [18] |
| Revised invoice | Supplies made between the effective date of registration and the date the registration certificate was issued; must show the words "Revised Invoice" prominently. [2] | Rule 53(1) [9] |
Mandatory content
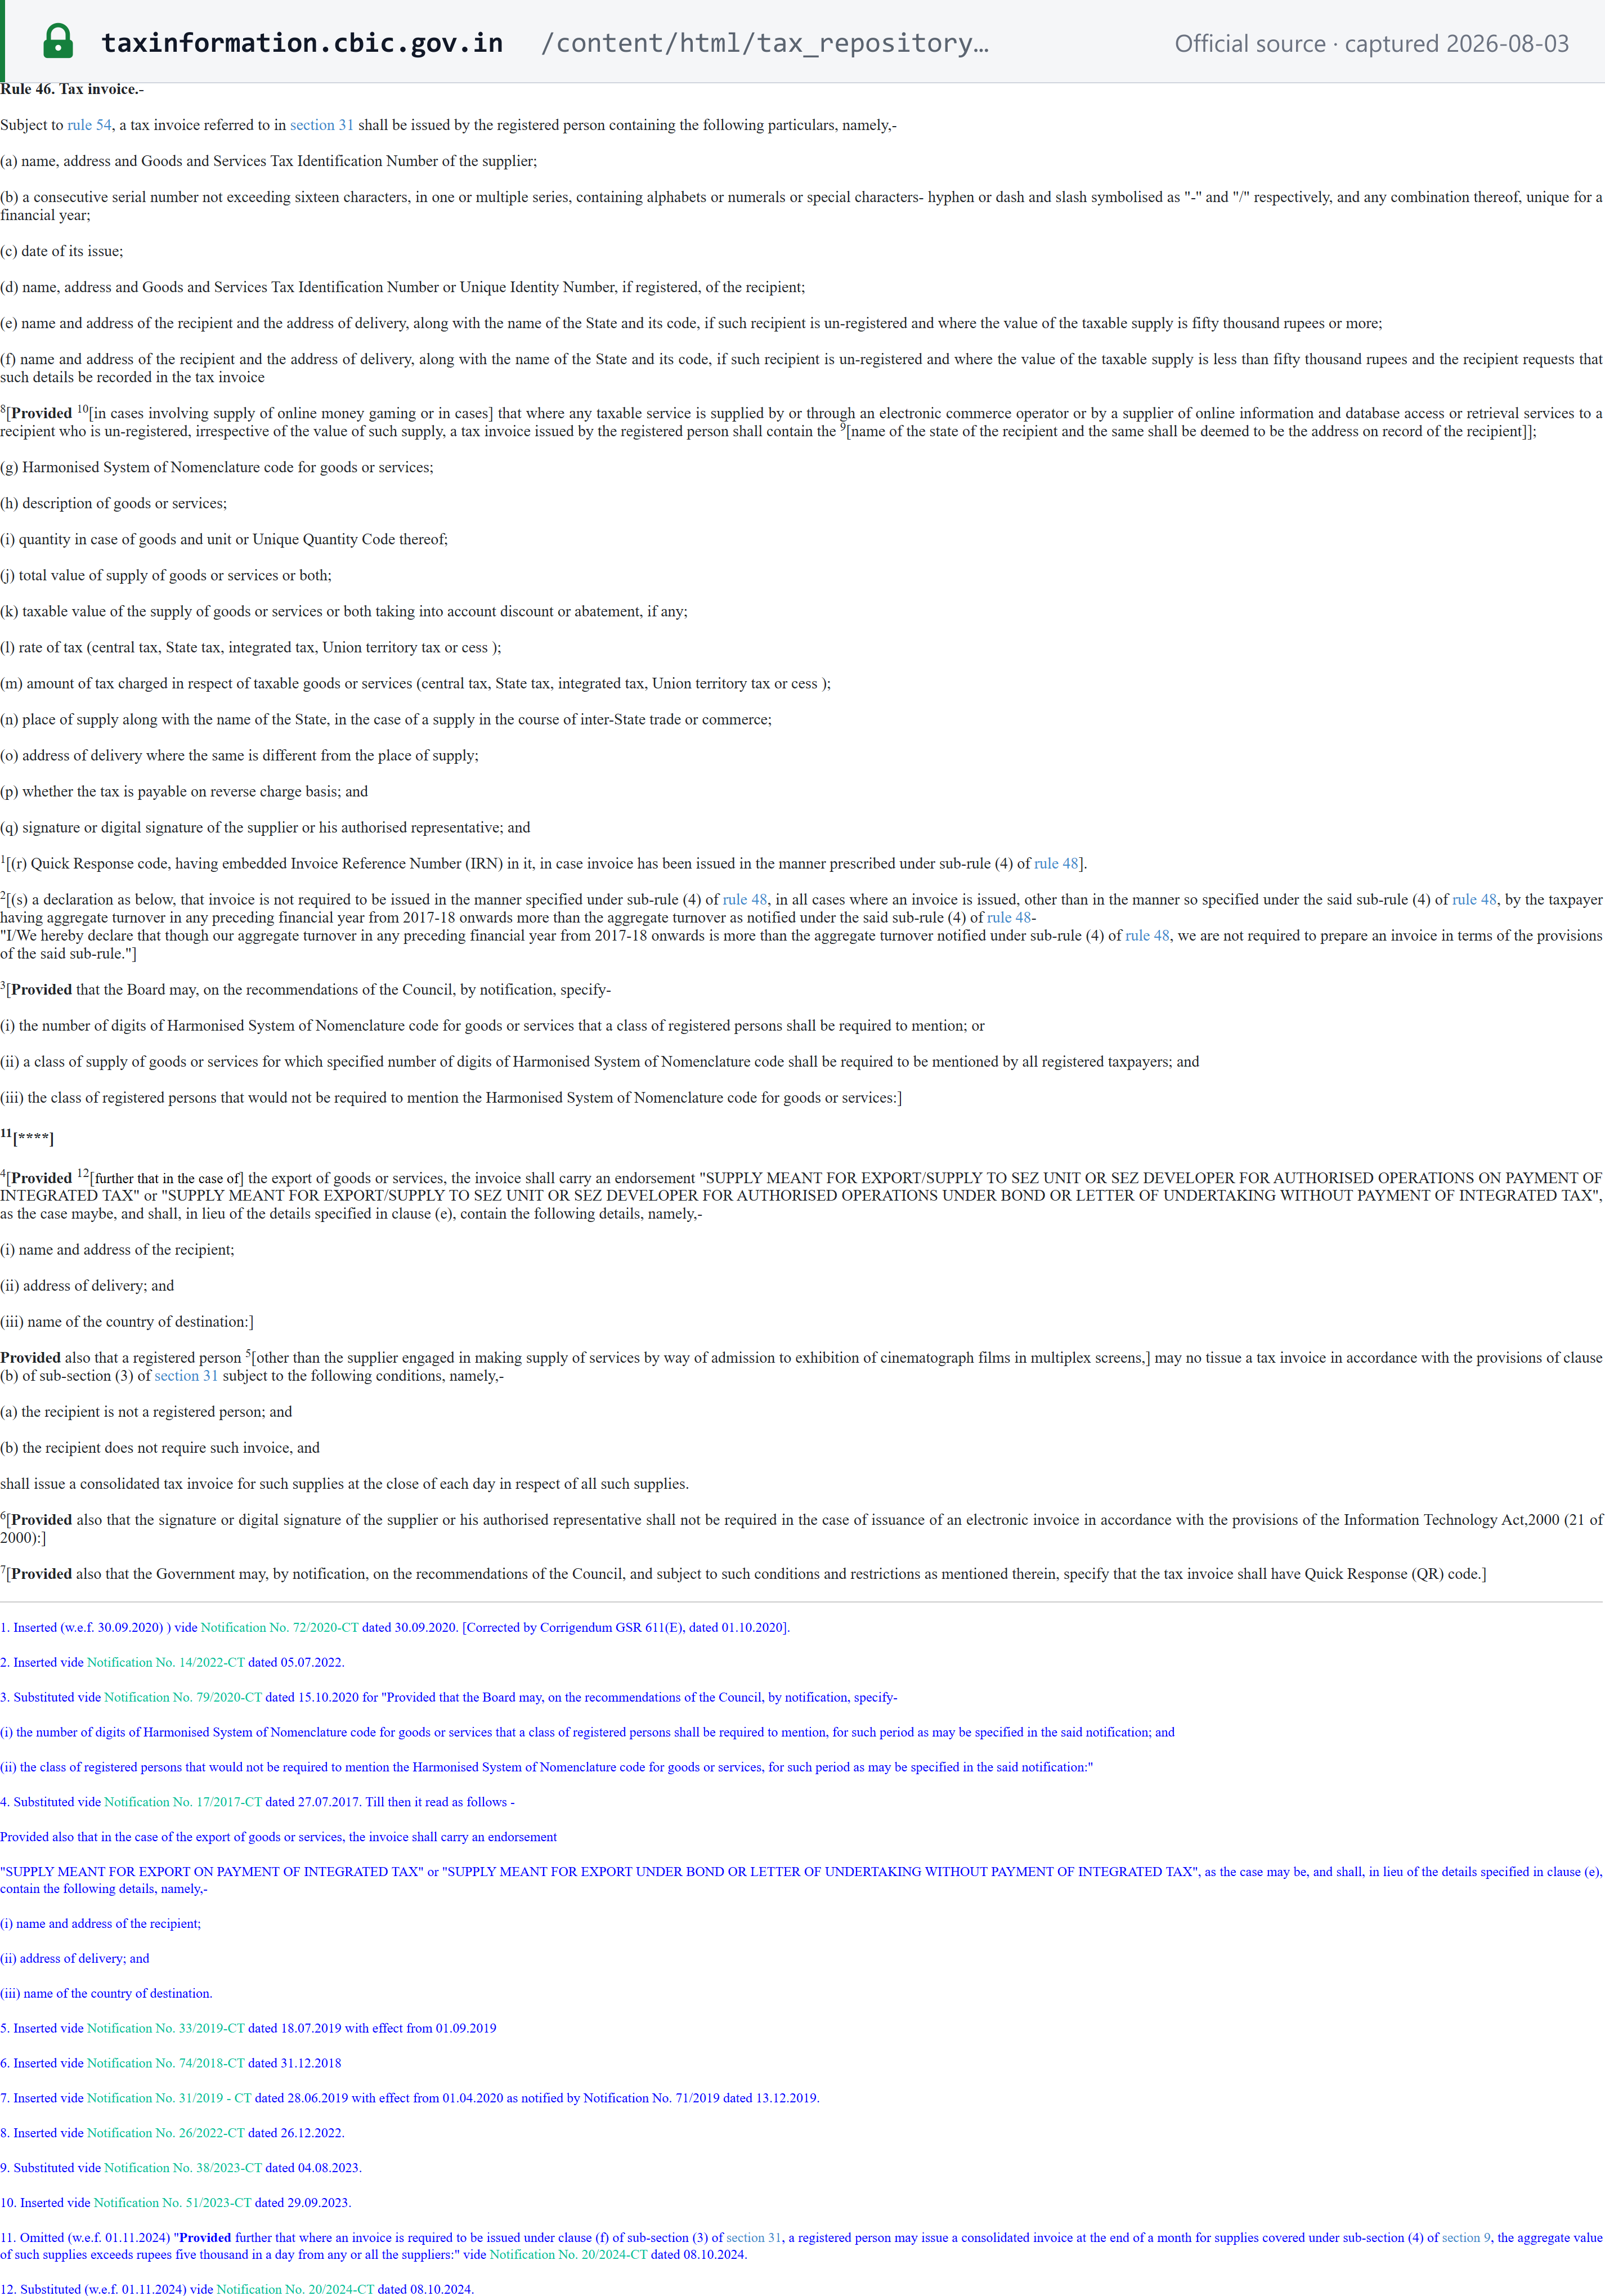
Particulars of a tax invoice under Rule 46. Clause references are to Rule 46 unless stated.
| Required particular | Notes |
|---|---|
| Name, address and GSTIN of the supplier | Clause (a). [1] |
| Consecutive serial number, not exceeding sixteen characters | Clause (b) — "in one or multiple series, containing alphabets or numerals or special characters- hyphen or dash and slash … and any combination thereof, unique for a financial year". [1] |
| Date of issue | Clause (c). [1] |
| Name, address and GSTIN or UIN of the recipient, if registered | Clause (d). [1] |
| Name, address and address of delivery of an unregistered recipient, with the State name and code | Clause (e) — required "if such recipient is un-registered and where the value of the taxable supply is fifty thousand rupees or more"; clause (f) requires the same details below that value if the recipient asks for them. Where a taxable service is supplied by or through an e-commerce operator or an OIDAR supplier to an unregistered recipient, or in cases involving online money gaming, the invoice must carry the name of the recipient's State irrespective of value, and that is deemed to be the recipient's address on record. [1] |
| HSN code for the goods or services | Clause (g). Under Notification 78/2020-Central Tax, from 1 April 2021, a supplier with aggregate turnover in the preceding financial year of up to ₹5 crore shows 4 digits and above ₹5 crore shows 6 digits; the smaller suppliers "may not mention the number of digits of HSN Code … in respect of supplies made to unregistered persons" (GST Council — Notification 78/2020-CT). |
| Description of the goods or services | Clause (h). [1] |
| Quantity, and unit or Unique Quantity Code (goods) | Clause (i). [1] |
| Total value of the supply | Clause (j). [1] |
| Taxable value of the supply, after any discount or abatement | Clause (k). [1] |
| Rate of tax — central, State, integrated, Union territory tax or cess | Clause (l). [1] |
| Amount of tax charged under each of those heads | Clause (m). [1] |
| Place of supply with the State name, for inter-State supplies | Clause (n). [1] |
| Address of delivery, where it differs from the place of supply | Clause (o). [1] |
| Whether tax is payable on a reverse charge basis | Clause (p). [1] |
| Signature or digital signature of the supplier or an authorised representative | Clause (q). A proviso inserted by Notification 74/2018-Central Tax says the signature "shall not be required in the case of issuance of an electronic invoice in accordance with the provisions of the Information Technology Act,2000". [1] |
| QR code with the IRN embedded in it | Clause (r) — applies only where the invoice is issued in the manner prescribed by Rule 48(4), i.e. registered on the IRP. See E-invoicing status below. [1] |
| Declaration that Rule 48(4) does not apply | Clause (s) — required where a taxpayer whose aggregate turnover in any preceding financial year from 2017-18 onwards exceeds the Rule 48(4) threshold issues an invoice outside the e-invoice route; the prescribed wording states that the taxpayer is not required to prepare an invoice under that sub-rule. [1] |
 Source snapshot captured 2026-08-03 — original
Export and SEZ endorsement. A proviso to Rule 46 requires an export invoice to carry the endorsement "SUPPLY MEANT FOR EXPORT/SUPPLY TO SEZ UNIT OR SEZ DEVELOPER FOR AUTHORISED OPERATIONS ON PAYMENT OF INTEGRATED TAX" or "SUPPLY MEANT FOR EXPORT/SUPPLY TO SEZ UNIT OR SEZ DEVELOPER FOR AUTHORISED OPERATIONS UNDER BOND OR LETTER OF UNDERTAKING WITHOUT PAYMENT OF INTEGRATED TAX", as the case may be. In place of the clause (e) details it must show the recipient's name and address, the address of delivery, and the name of the country of destination. [1]
A bill of supply carries a shorter list — supplier details, the same sixteen-character serial number, date, recipient details, HSN code, description, value after discount or abatement, and signature; the provisos to Rule 46 apply to it, and an electronic bill of supply needs no signature. [6]
Issuance deadline and numbering
| Supply | Deadline |
|---|---|
| Goods, where the supply involves movement | Before or at the time of removal of the goods for supply to the recipient. [2] |
| Goods, in any other case | Before or at the time of delivery, or of making the goods available to the recipient. [2] |
| Services — general rule | "within a period of thirty days from the date of the supply of service" (Rule 47). [3] |
| Services supplied by an insurer, a banking company, or a financial institution including an NBFC | Forty-five days from the date of supply of the service. [3] |
| Those same suppliers, plus telecom operators, supplying between distinct persons under section 25 | Before or at the time the supplier records the supply in its books, or before the end of the quarter in which the supply was made. [3] |
| Reverse-charge self-invoice under section 31(3)(f) by a person liable under section 9(3) or 9(4) | "within a period of thirty days from the date of receipt of the said supply" — Rule 47A, in force from 1 November 2024. [4] |
| Continuous supply of goods with successive statements or payments | Before or at the time each statement is issued or each payment is received. [2] |
| Continuous supply of services | On or before the due date of payment where it is ascertainable from the contract; otherwise when the supplier receives payment; where payment is tied to an event, on or before the date that event is completed. [2] |
| Service contract that ceases before completion | At the time the supply ceases, for the supply made up to that point. [2] |
| Goods sent on approval, for sale or return | Before or at the time of supply, or six months from the date of removal, whichever is earlier. [2] |
| Revised invoice for the pre-certificate period | Within one month from the date the registration certificate is issued. [2] |
Numbering. The serial number must be consecutive, no longer than sixteen characters, and unique for a financial year; multiple series are allowed, and only alphabets, numerals, hyphen/dash and slash may be used. The same sixteen-character rule is repeated for bills of supply, receipt/refund/payment vouchers, revised invoices, credit and debit notes, Input Service Distributor invoices and delivery challans. [1] [9] The serial numbers of invoices issued during a tax period must be furnished electronically through the common portal in FORM GSTR-1 (and in FORM GSTR-1A, if any). [5]
Manner of issue. "The invoice shall be prepared in triplicate, in the case of supply of goods" — marked ORIGINAL FOR RECIPIENT, DUPLICATE FOR TRANSPORTER and TRIPLICATE FOR SUPPLIER — and for services in duplicate (ORIGINAL FOR RECIPIENT, DUPLICATE FOR SUPPLIER). Neither applies to an invoice prepared under Rule 48(4). [5]
Self-billing. The CGST Act and Rules provide no general self-billing arrangement under which a customer issues the supplier's tax invoice. The self-invoice that does exist is the recipient's own invoice under section 31(3)(f) for supplies on which the recipient pays tax under reverse charge, issued within the Rule 47A time limit above.
Credit and debit notes
- Credit note — the supplier may issue one where the taxable value or tax charged on an invoice exceeds what was payable, where goods are returned, or where the goods or services are found deficient. One or more credit notes may be issued for supplies made in a financial year. [8]
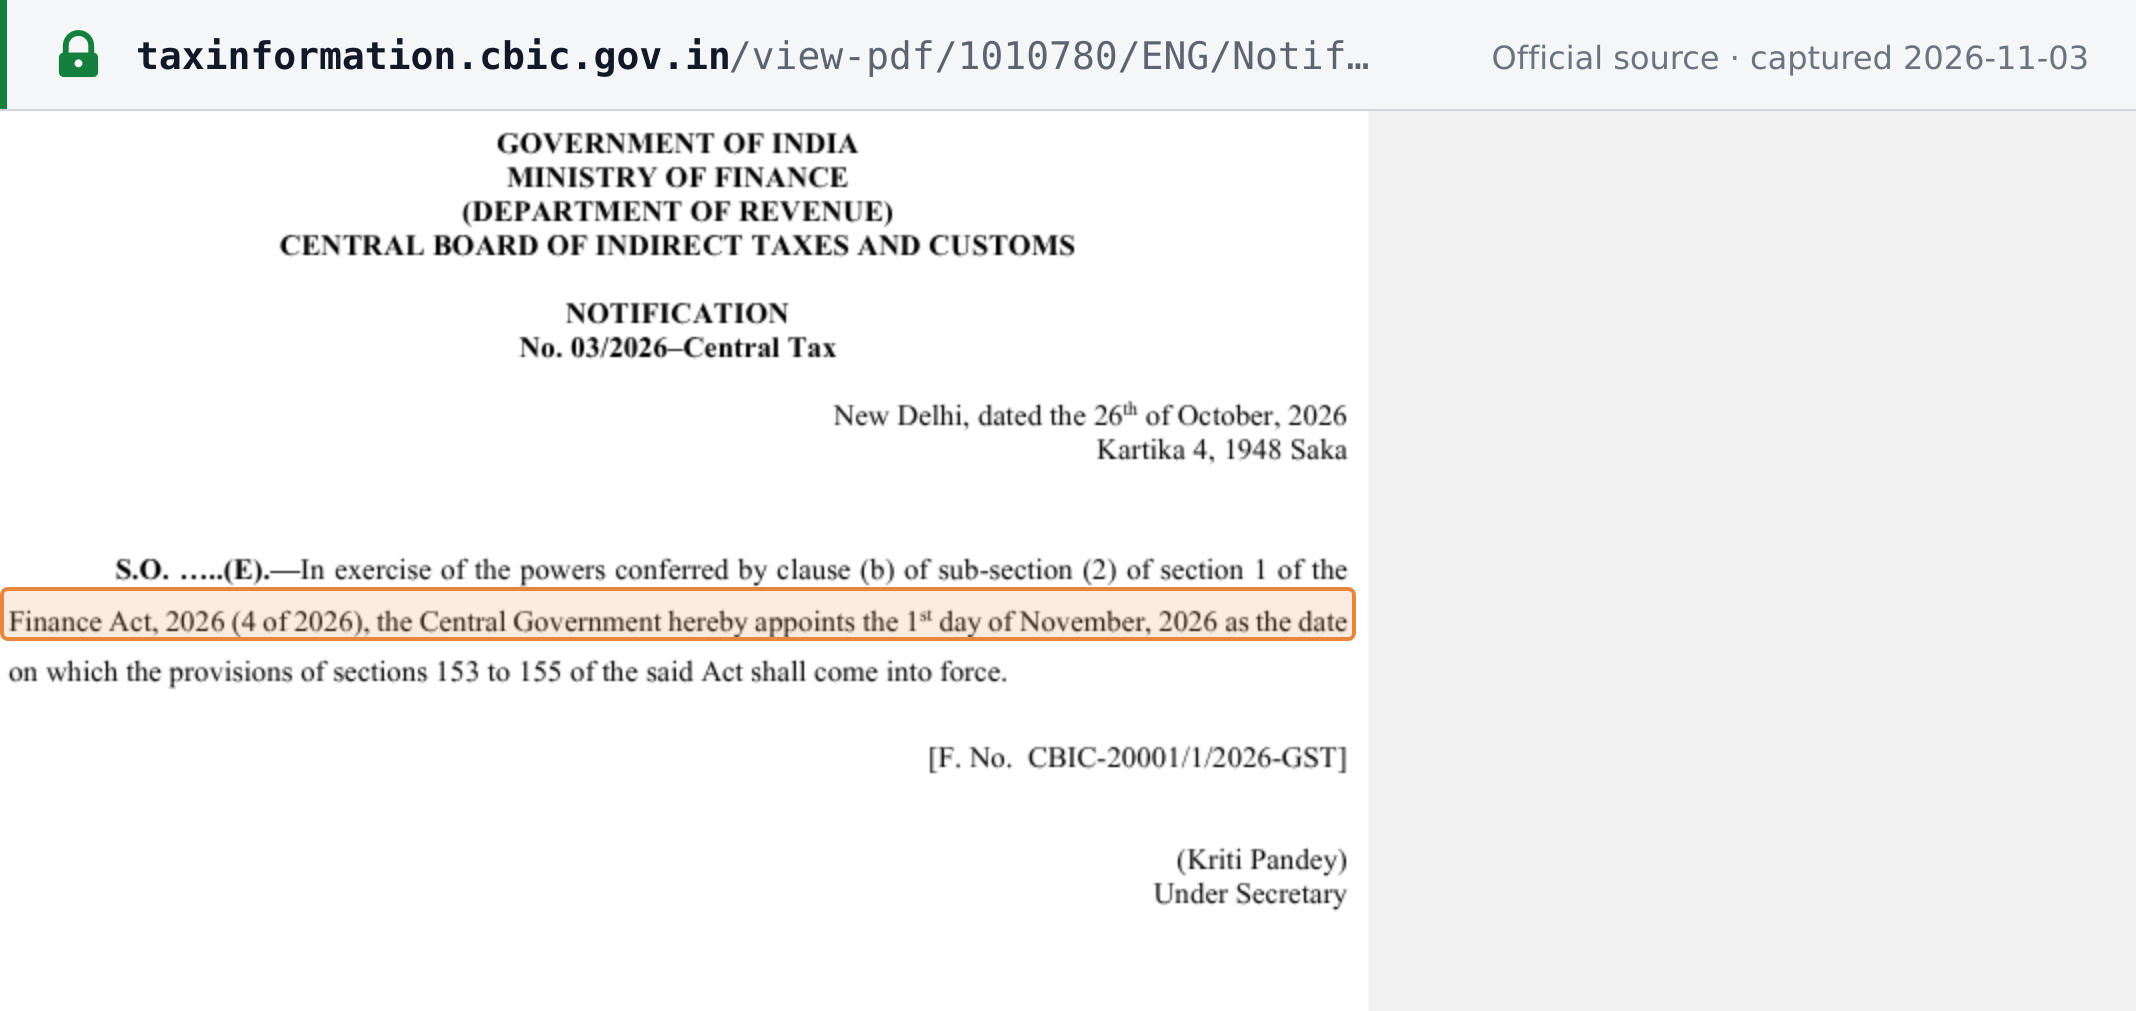
- Discounts, from 1 November 2026 — section 34(1) now also allows a credit note "where a discount referred to in clause (b) of sub-section (3) of section 15 is given", and the substituted section 15(3)(b) excludes a post-supply discount from the value of supply only "if for such discount, a credit note has been issued by the supplier and input tax credit as is attributable to such discount has been reversed by the recipient of the supply". These amendments are sections 153 to 155 of the Finance Act, 2026, brought into force on 1 November 2026 by Notification 03/2026-Central Tax dated 26 October 2026 (CBIC — Notification 03/2026-CT).
 Source snapshot captured 2026-11-03 — original
- Debit note — the supplier shall issue one where the taxable value or tax charged on an invoice is less than what was payable. For the purposes of the Act a debit note includes a supplementary invoice. [8]
- Contents (Rule 53(1A)) — supplier name, address and GSTIN; the nature of the document; a consecutive serial number of up to sixteen characters, unique for the financial year; date of issue; recipient details (and, for an unregistered recipient, name, address, address of delivery, State name and code); the serial number(s) and date(s) of the corresponding invoice(s) or bill(s) of supply; the value of the taxable supply, the rate of tax and the amount credited or debited; and the signature or digital signature. [9]
- Declaration deadline — a credit note must be declared in the return for the month of issue, and no later than 30 November following the end of the financial year in which the supply was made, or the date of furnishing the relevant annual return, whichever is earlier. The month was changed from September to the thirtieth day of November with effect from 1 October 2022. A debit note carries no such cut-off — it is declared in the return for the month of issue. [8]
- Credit-note conditionality (from 1 October 2025) — the supplier gets no reduction in output tax liability unless the recipient, if registered, has reversed the input tax credit attributable to the credit note; in other cases, unless the incidence of tax has not been passed on to anyone else. [8]
- Any invoice or debit note raised for tax payable under section 74, 129 or 130 must prominently carry the words "INPUT TAX CREDIT NOT ADMISSIBLE". [9]
Currency and language
Rule 46 fixes the particulars, not the currency, so an invoice may be denominated in a foreign currency — export invoices routinely are, provided they carry the endorsement above. Where the consideration is in a currency other than Indian rupees, Rule 34 fixes the conversion for determining the value of the supply: [11]
- Goods — the rate of exchange notified by the Board under section 14 of the Customs Act, 1962 for the date of the time of supply determined under section 12.
- Services — the rate of exchange determined as per generally accepted accounting principles for the date of the time of supply determined under section 13.
Language: the Rule 46 particulars do not include a language, and the CGST Act and Rules as consolidated by CBIC contain no invoice-language rule.
Simplified invoices
India has no general "simplified invoice" with a reduced field set. What exists instead is a de-minimis relief plus a set of special-case documents:
- Under ₹200 — under section 31(3)(b) "a registered person may not issue a tax invoice if the value of the goods or services or both supplied is less than two hundred rupees", but only if the recipient is unregistered and does not ask for an invoice; a consolidated tax invoice must then be issued at the close of each day covering all such supplies. Suppliers of admission to cinematograph films on multiplex screens are excluded from this relaxation. The same ₹200 relief applies to a bill of supply. [2] [1]
- Insurers, banks, financial institutions and NBFCs — may issue a consolidated monthly tax invoice or equivalent document at the end of the month, physically or electronically, whether or not serially numbered and whether or not it carries the recipient's address, provided it contains the other Rule 46 information; no signature is needed on an electronic one. [10]
- Passenger transport — a ticket in any form counts as the tax invoice, whether or not serially numbered and whether or not it carries the recipient's address, if it holds the other Rule 46 information; an electronically issued ticket needs no signature. A multiplex cinema e-ticket is deemed to be a tax invoice on the same basis. [10]
- Goods transport agencies — the invoice or consignment note must additionally show the gross weight of the consignment, consigner and consignee names, the goods carriage registration number, details of the goods and of the origin and destination, and the GSTIN of the person liable to pay the tax. [10]
- Input Service Distributors — a shorter particulars list under Rule 54(1); where the ISD is an office of a bank or NBFC, the invoice may be any document in lieu, whether or not serially numbered, so long as it carries the same information. [10]
- Consolidated revised invoices — for unregistered recipients, and, for inter-State supplies where a supply does not exceed ₹2,50,000, one consolidated revised invoice per State. [9]
Retention and audit trail
- Seventy-two months — every registered person required to keep books under section 35(1) "shall retain them until the expiry of seventy-two months from the due date of furnishing of annual return for the year pertaining to such accounts and records". [12]
- Extension where a dispute is live — a person who is party to an appeal, revision or other proceedings before an Appellate Authority, Revisional Authority, Appellate Tribunal or court, or who is under investigation for an offence under Chapter XIX, must keep the related records for one year after final disposal of that matter, or the 72-month period, whichever is later. [12]
- What is covered and where it is kept — accounts together with all invoices, bills of supply, credit and debit notes and delivery challans must be preserved for the section 36 period. Manual records must be kept at every related place of business named in the registration certificate; digitally maintained records must be accessible at every such place. Books are kept at the principal place of business, with each additional place holding its own. [13] [15]
- Electronic archiving is accepted — records may be maintained in electronic form, authenticated by digital signature. A proper electronic back-up must be kept so the information can be restored after accidental loss, and the records must be produced on demand in hard copy or in an electronically readable format, along with file details, passwords and an explanation of any codes used. [13] [14]
Audit trail. Retention says keep it; the audit trail says prove it was never quietly altered. Rule 56(8) of the CGST Rules supplies the GST rule: "Any entry in registers, accounts and documents shall not be erased, effaced or overwritten, and all incorrect entries, otherwise than those of clerical nature, shall be scored out under attestation and there after the correct entry shall be recorded and where the registers and other documents are maintained electronically, a log of every entry edited or deleted shall be maintained." [13] Companies may face separate audit-trail rules under company law; those are outside this guide.
Technical format
A format is mandated only for the class of registered persons notified under Rule 48(4): the invoice must be prepared by including the particulars of FORM GST INV-01 — the e-invoice schema, exchanged as JSON — and uploading them to the Invoice Registration Portal to obtain an Invoice Reference Number. An invoice that should have been issued this way but was not "shall not be treated as an invoice" (Rule 48(5)). [5] FORM GST INV-01 moves from schema version 1.1 to version 1.2 on 1 January 2027 (Notification 05/2026-CT). For thresholds, scope and reporting limits, see E-invoicing status below and the India IRP e-invoicing guide; NIC sets out the schema and API in the GST e-invoice system detailed overview (PDF).
What a compliant invoice looks like
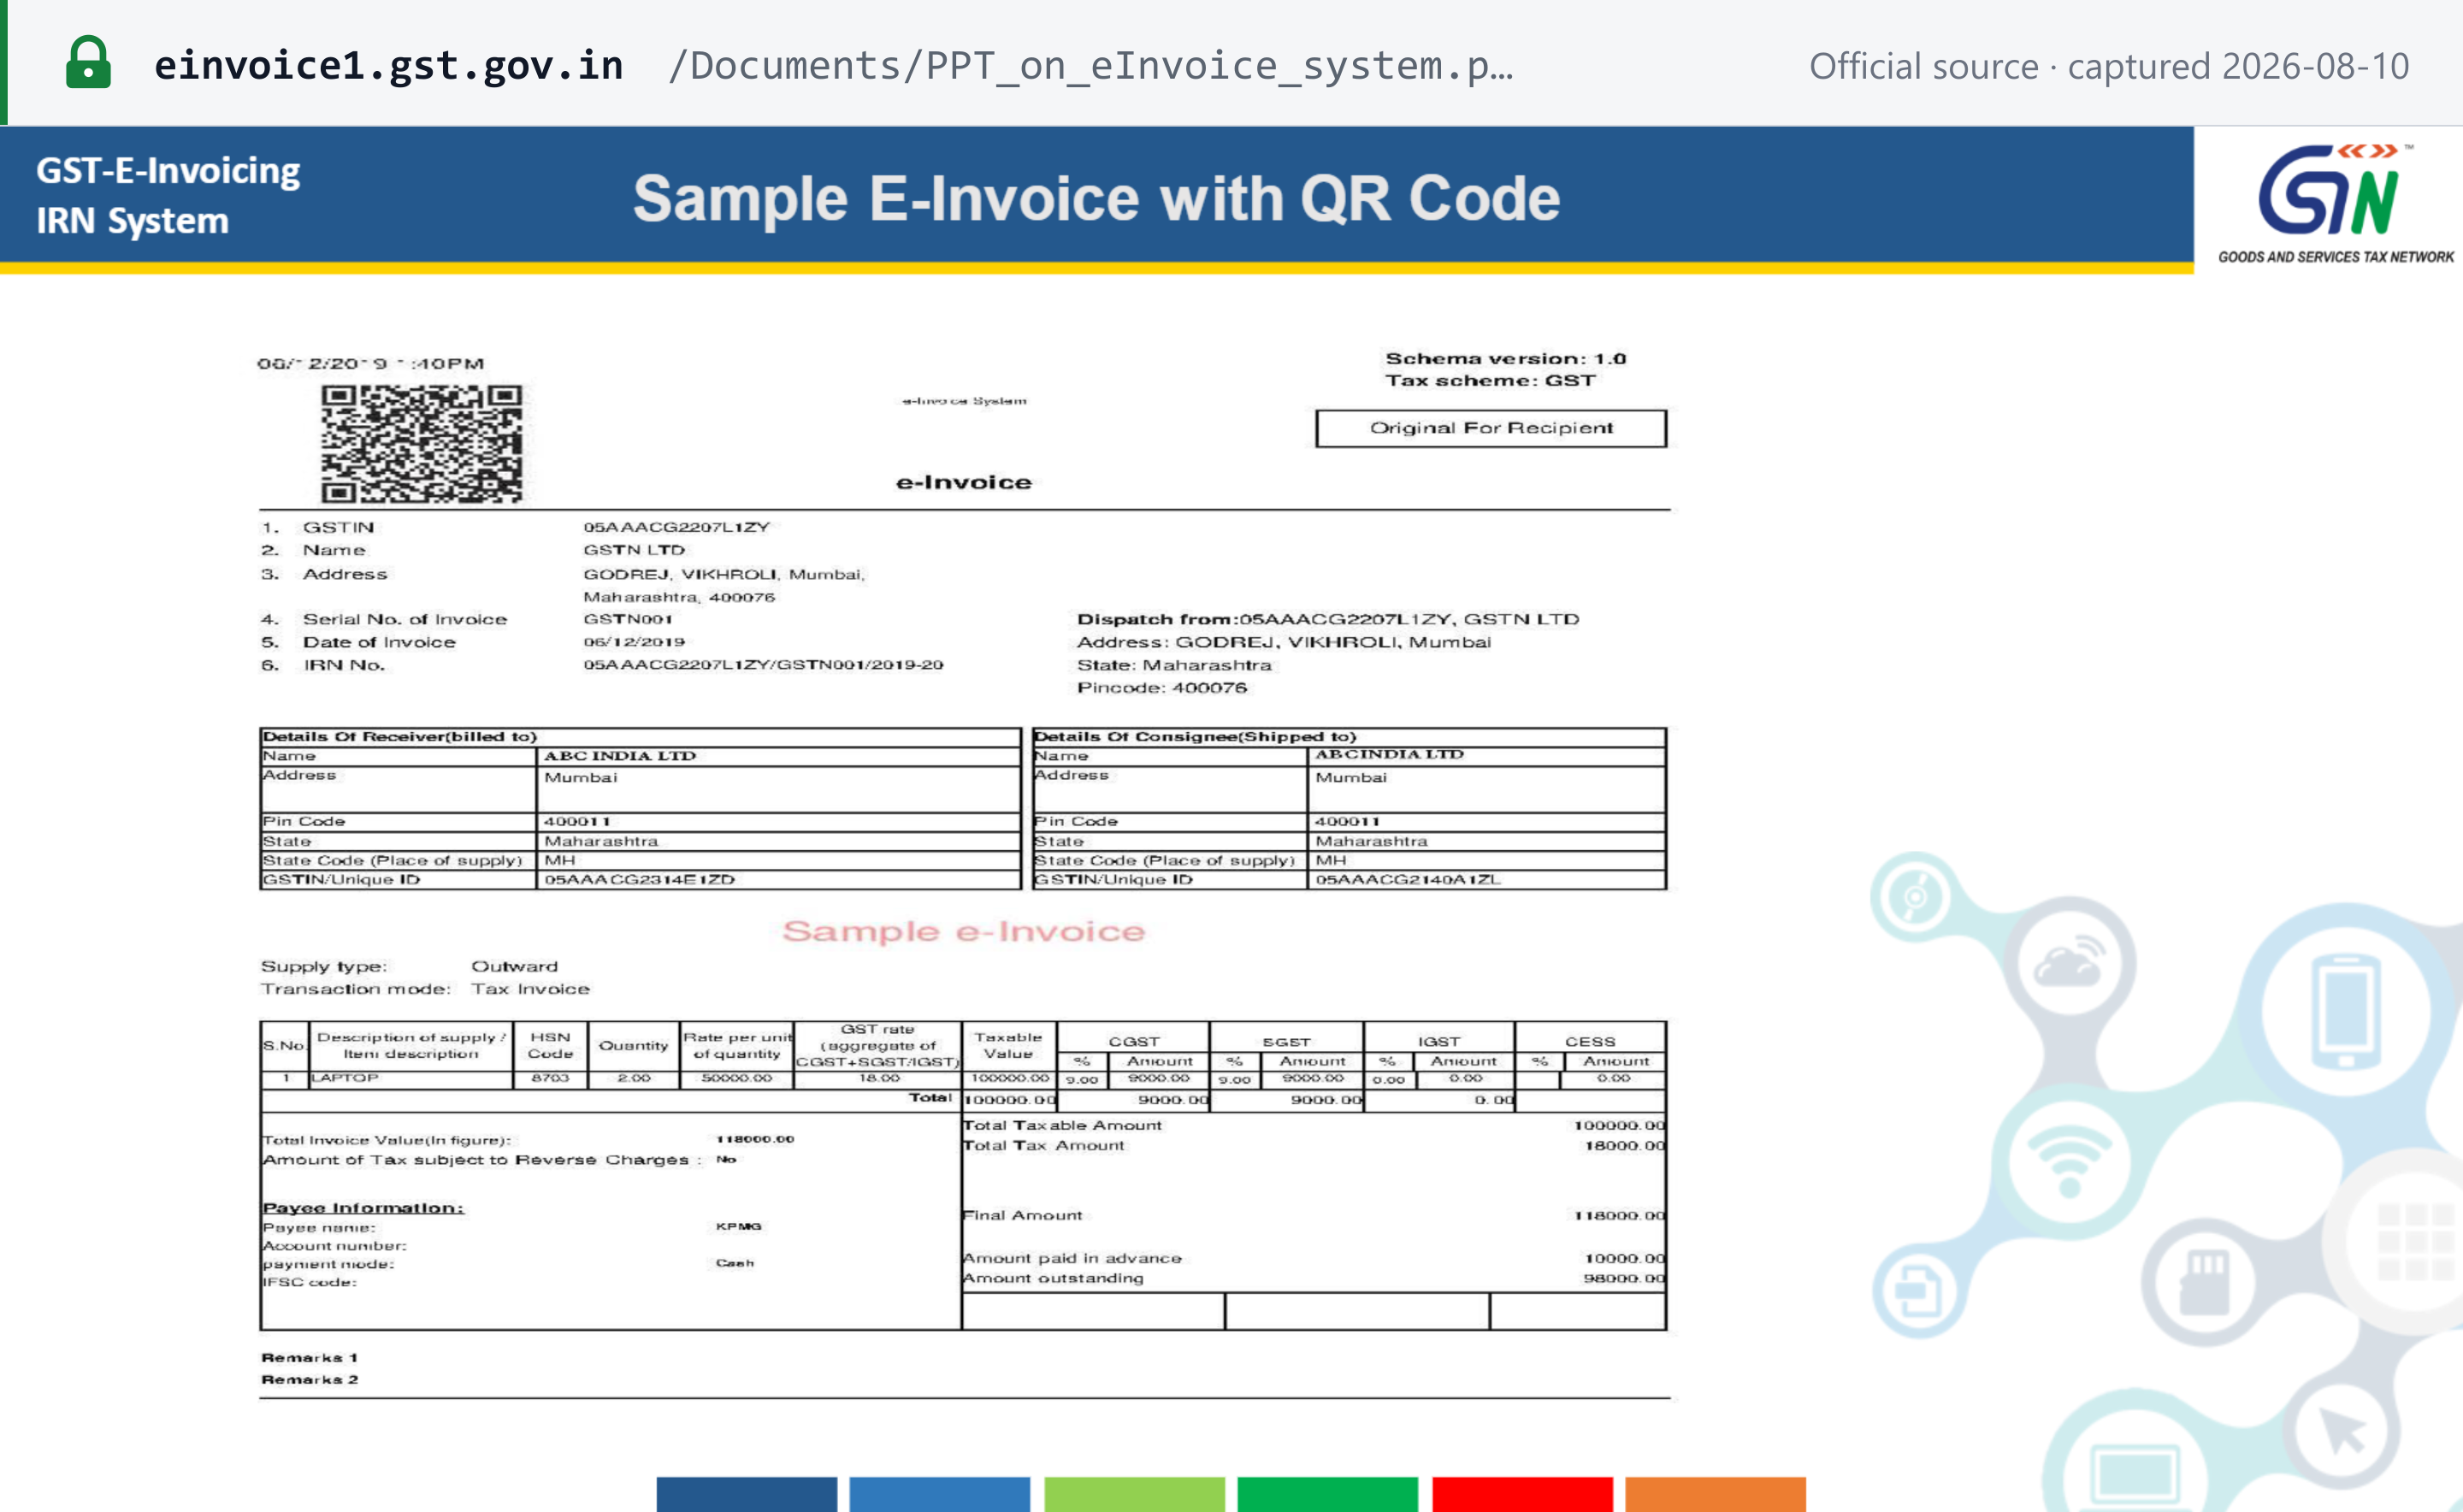
India prescribes particulars and a reporting schema, not a layout. Rule 46 lists what a tax invoice must contain, not where it goes, so a supplier may use its own design, logo and layout; for an e-invoice, the schema governs only what is reported to the IRP, and the QR code with the IRN must appear on the invoice because it is a mandatory particular under Rule 46(r) [1].
Within that freedom, GSTN publishes a worked sample showing the Rule 46 particulars alongside the IRN and QR code — supplier GSTIN, name and address, invoice serial number and date, IRN No., separate "billed to" and "shipped to" blocks with place of supply, and a line-item table carrying the HSN code, taxable value and separate CGST, SGST, IGST and cess columns (GSTN — presentation on the e-invoice system, p.38). The sample shows schema version 1.0 and an 18% intra-State supply billed as 9% CGST + 9% SGST.
 Source snapshot captured 2026-08-10 — original
E-invoicing status
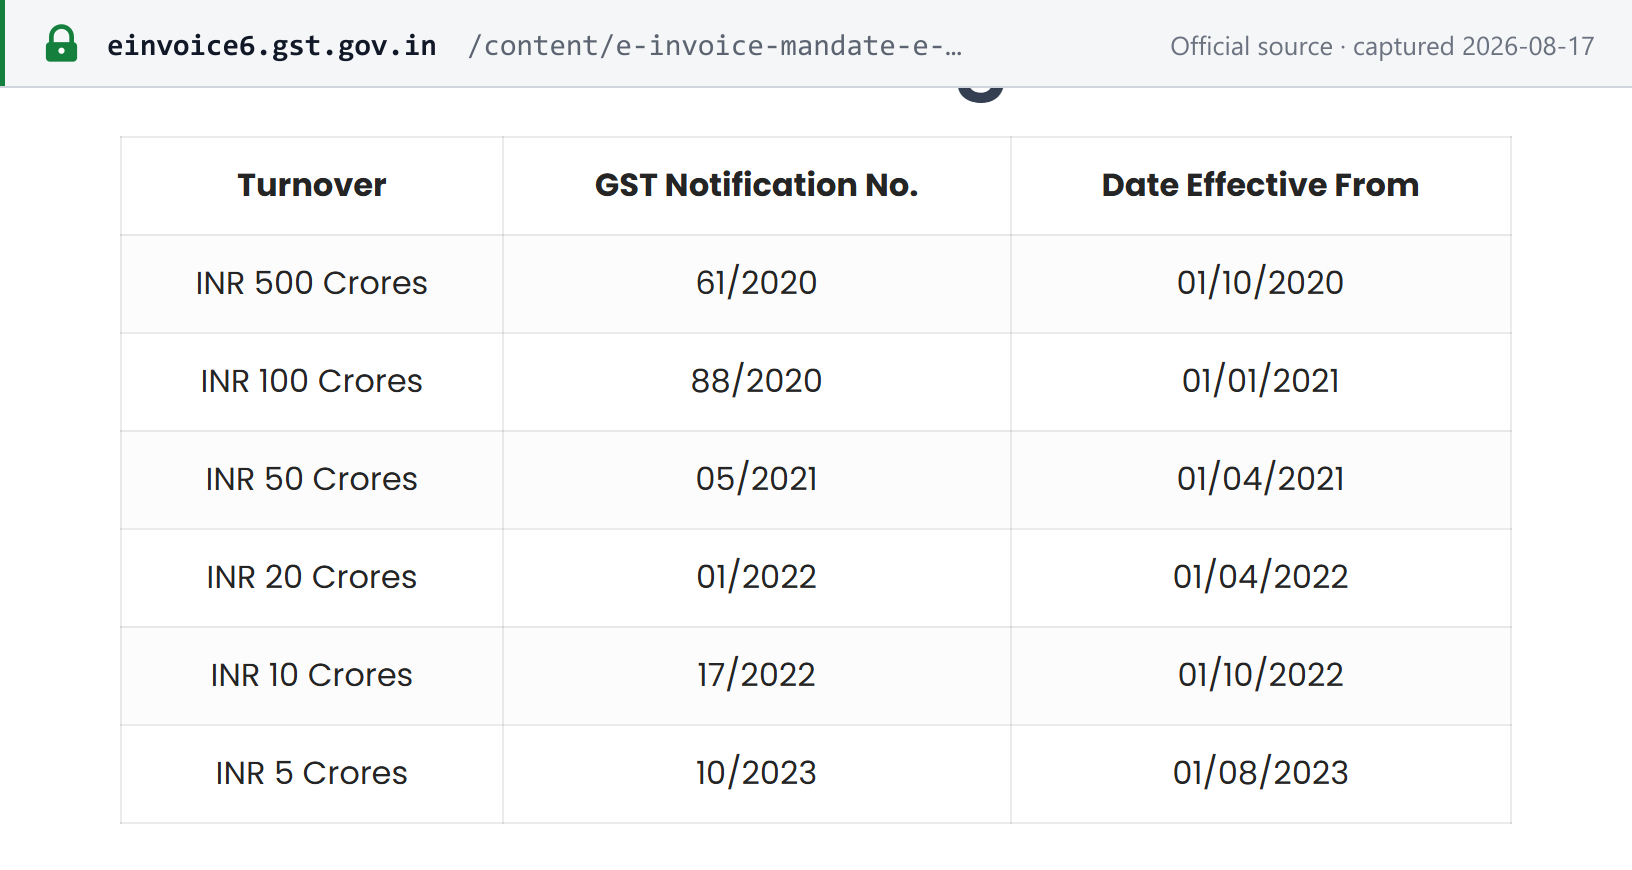
Status as at 4 November 2026: mandatory, phased by turnover. E-invoicing applies to every registered person, other than the exempt classes below, whose aggregate turnover in any preceding financial year from 2017-18 onwards exceeded ₹5 crore (₹50 million), from 1 August 2023: Notification 10/2023-Central Tax (10 May 2023) substituted "five crore rupees" for "ten crore rupees" "with effect from the 1 st day of August, 2023" (CBIC — Notification 10/2023-CT). The test looks back across all preceding years from 2017-18 (Notification 13/2020-CT as amended by 70/2020-CT), not just the last one: a business that crosses ₹5 crore during a year comes into scope from the next financial year, and once in, it stays in scope.
System: the Invoice Registration Portal (IRP), operated by NIC. It is a registration network, not a delivery network — after obtaining an IRN the supplier still has to send the invoice to the buyer itself. This is the key difference from Peppol, which delivers to the recipient. The format is FORM GST INV-01 in JSON (schema version 1.1; version 1.2 from 1 January 2027). The full system — IRN, QR code, APIs, portals — is covered in the India IRP e-invoicing guide.
Phase timeline
| Aggregate turnover above | Notification (Central Tax) | Effective |
|---|---|---|
| ₹500 crore | 13/2020 as amended by 61/2020 | 1 Oct 2020 |
| ₹100 crore | 88/2020 | 1 Jan 2021 |
| ₹50 crore | 05/2021 | 1 Apr 2021 |
| ₹20 crore | 01/2022 | 1 Apr 2022 |
| ₹10 crore | 17/2022 | 1 Oct 2022 |
| ₹5 crore | 10/2023 | 1 Aug 2023 — current |
| ₹5 crore — scope widened to reverse-charge supplies from unregistered persons and imports of services | 04/2026 | 1 Jan 2027 — announced |
 Source snapshot captured 2026-08-17 — original
Scope
Until 31 December 2026 the e-invoicing notification (13/2020-Central Tax) applies "in respect of supply of goods or services or both to a registered person or for exports":
- B2B — in scope. Supplies to registered persons, plus exports and supplies to SEZ units and developers.
- B2G — in scope where the government buyer is registered, on the same basis as B2B.
- B2C — out of scope. No IRN is generated for a supply to an unregistered person. A separate obligation applies instead: under Notification 14/2020-Central Tax, as amended by 71/2020-Central Tax, a registered person whose aggregate turnover in any preceding financial year from 2017-18 onwards exceeds ₹500 crore must show a dynamic QR code on B2C invoices, from 1 December 2020 (GST Council — Notification 14/2020-CT; 71/2020-CT). The two mechanisms are unrelated and are frequently confused.
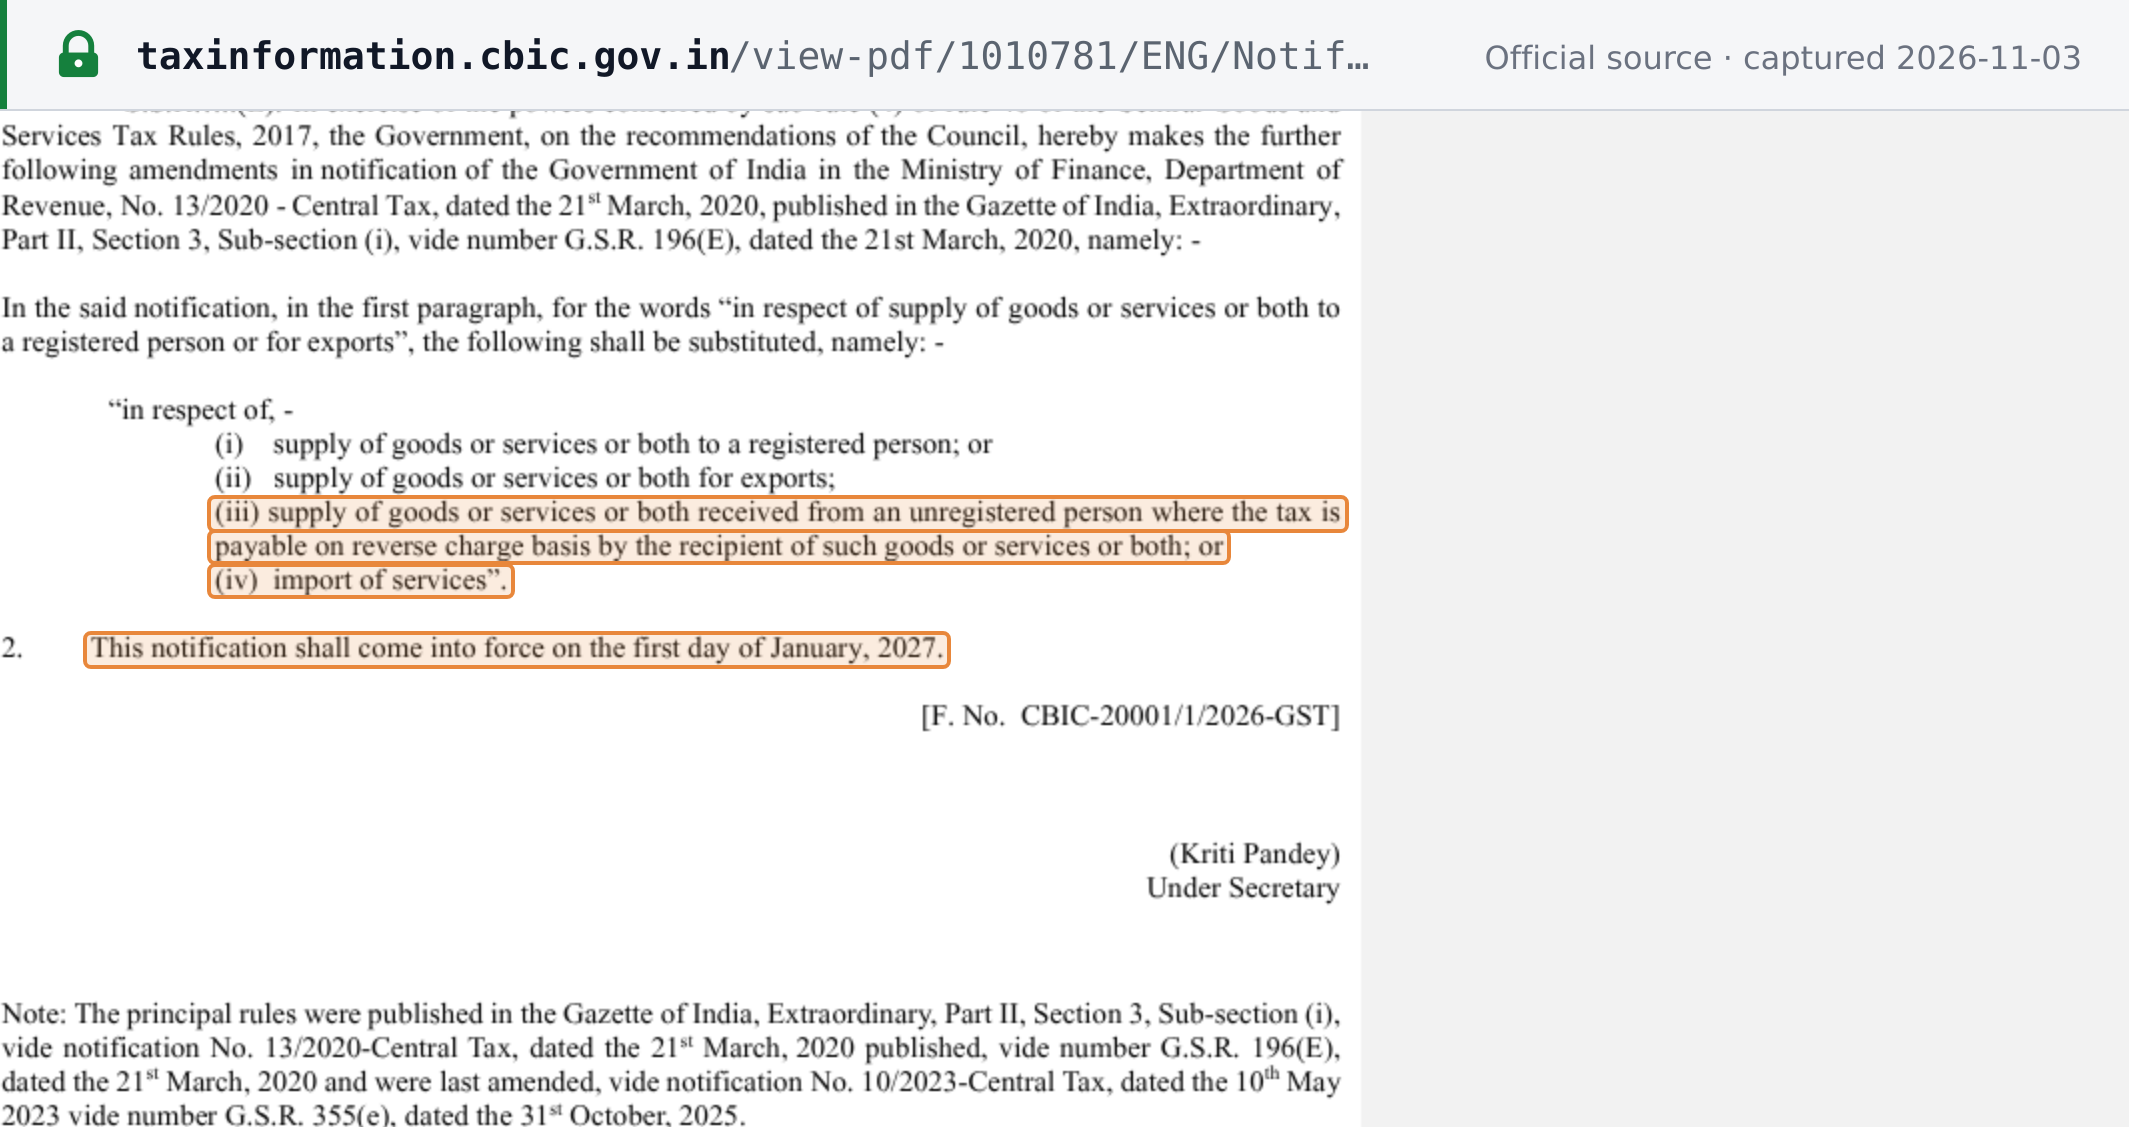
From 1 January 2027 the scope widens. Notification 04/2026-Central Tax (26 October 2026) substitutes the scope of 13/2020-CT so that it covers "(i) supply of goods or services or both to a registered person; or (ii) supply of goods or services or both for exports; (iii) supply of goods or services or both received from an unregistered person where the tax is payable on reverse charge basis by the recipient of such goods or services or both; or (iv) import of services", and "This notification shall come into force on the first day of January, 2027" (CBIC — Notification 04/2026-CT). In practice, the self-invoices that taxpayers in the e-invoicing class raise as recipients under reverse charge must then be reported to the IRP too. Notification 05/2026-CT moves FORM GST INV-01 to "Schema (Version 1.2)" from the same date and adds two supply types: "RCMDOM: Domestic supply from unregistered person under RCM" and "RCMIMP: Import of services". This implements the 57th GST Council's recommendation of 8 October 2026 — see event.
 Source snapshot captured 2026-11-03 — original
Documents covered: invoices, credit notes and debit notes issued by the supplier. Not covered: bills of supply, delivery challans and job-work challans.
Exempt classes, whatever their turnover: the persons in Rule 54(2), (3), (4) and (4A) — insurers, banks and financial institutions including NBFCs; goods transport agencies; passenger transport services; and suppliers of admission to the exhibition of cinematograph films in multiplex screens; SEZ units (added by 61/2020-CT; SEZ developers are not exempt); and, from 1 June 2021, "a government department, a local authority" (Notification 23/2021-Central Tax) (GST Council — Notification 23/2021-CT). Note the direction of travel: an SEZ unit is exempt as a supplier, while supplies made to an SEZ are in scope.
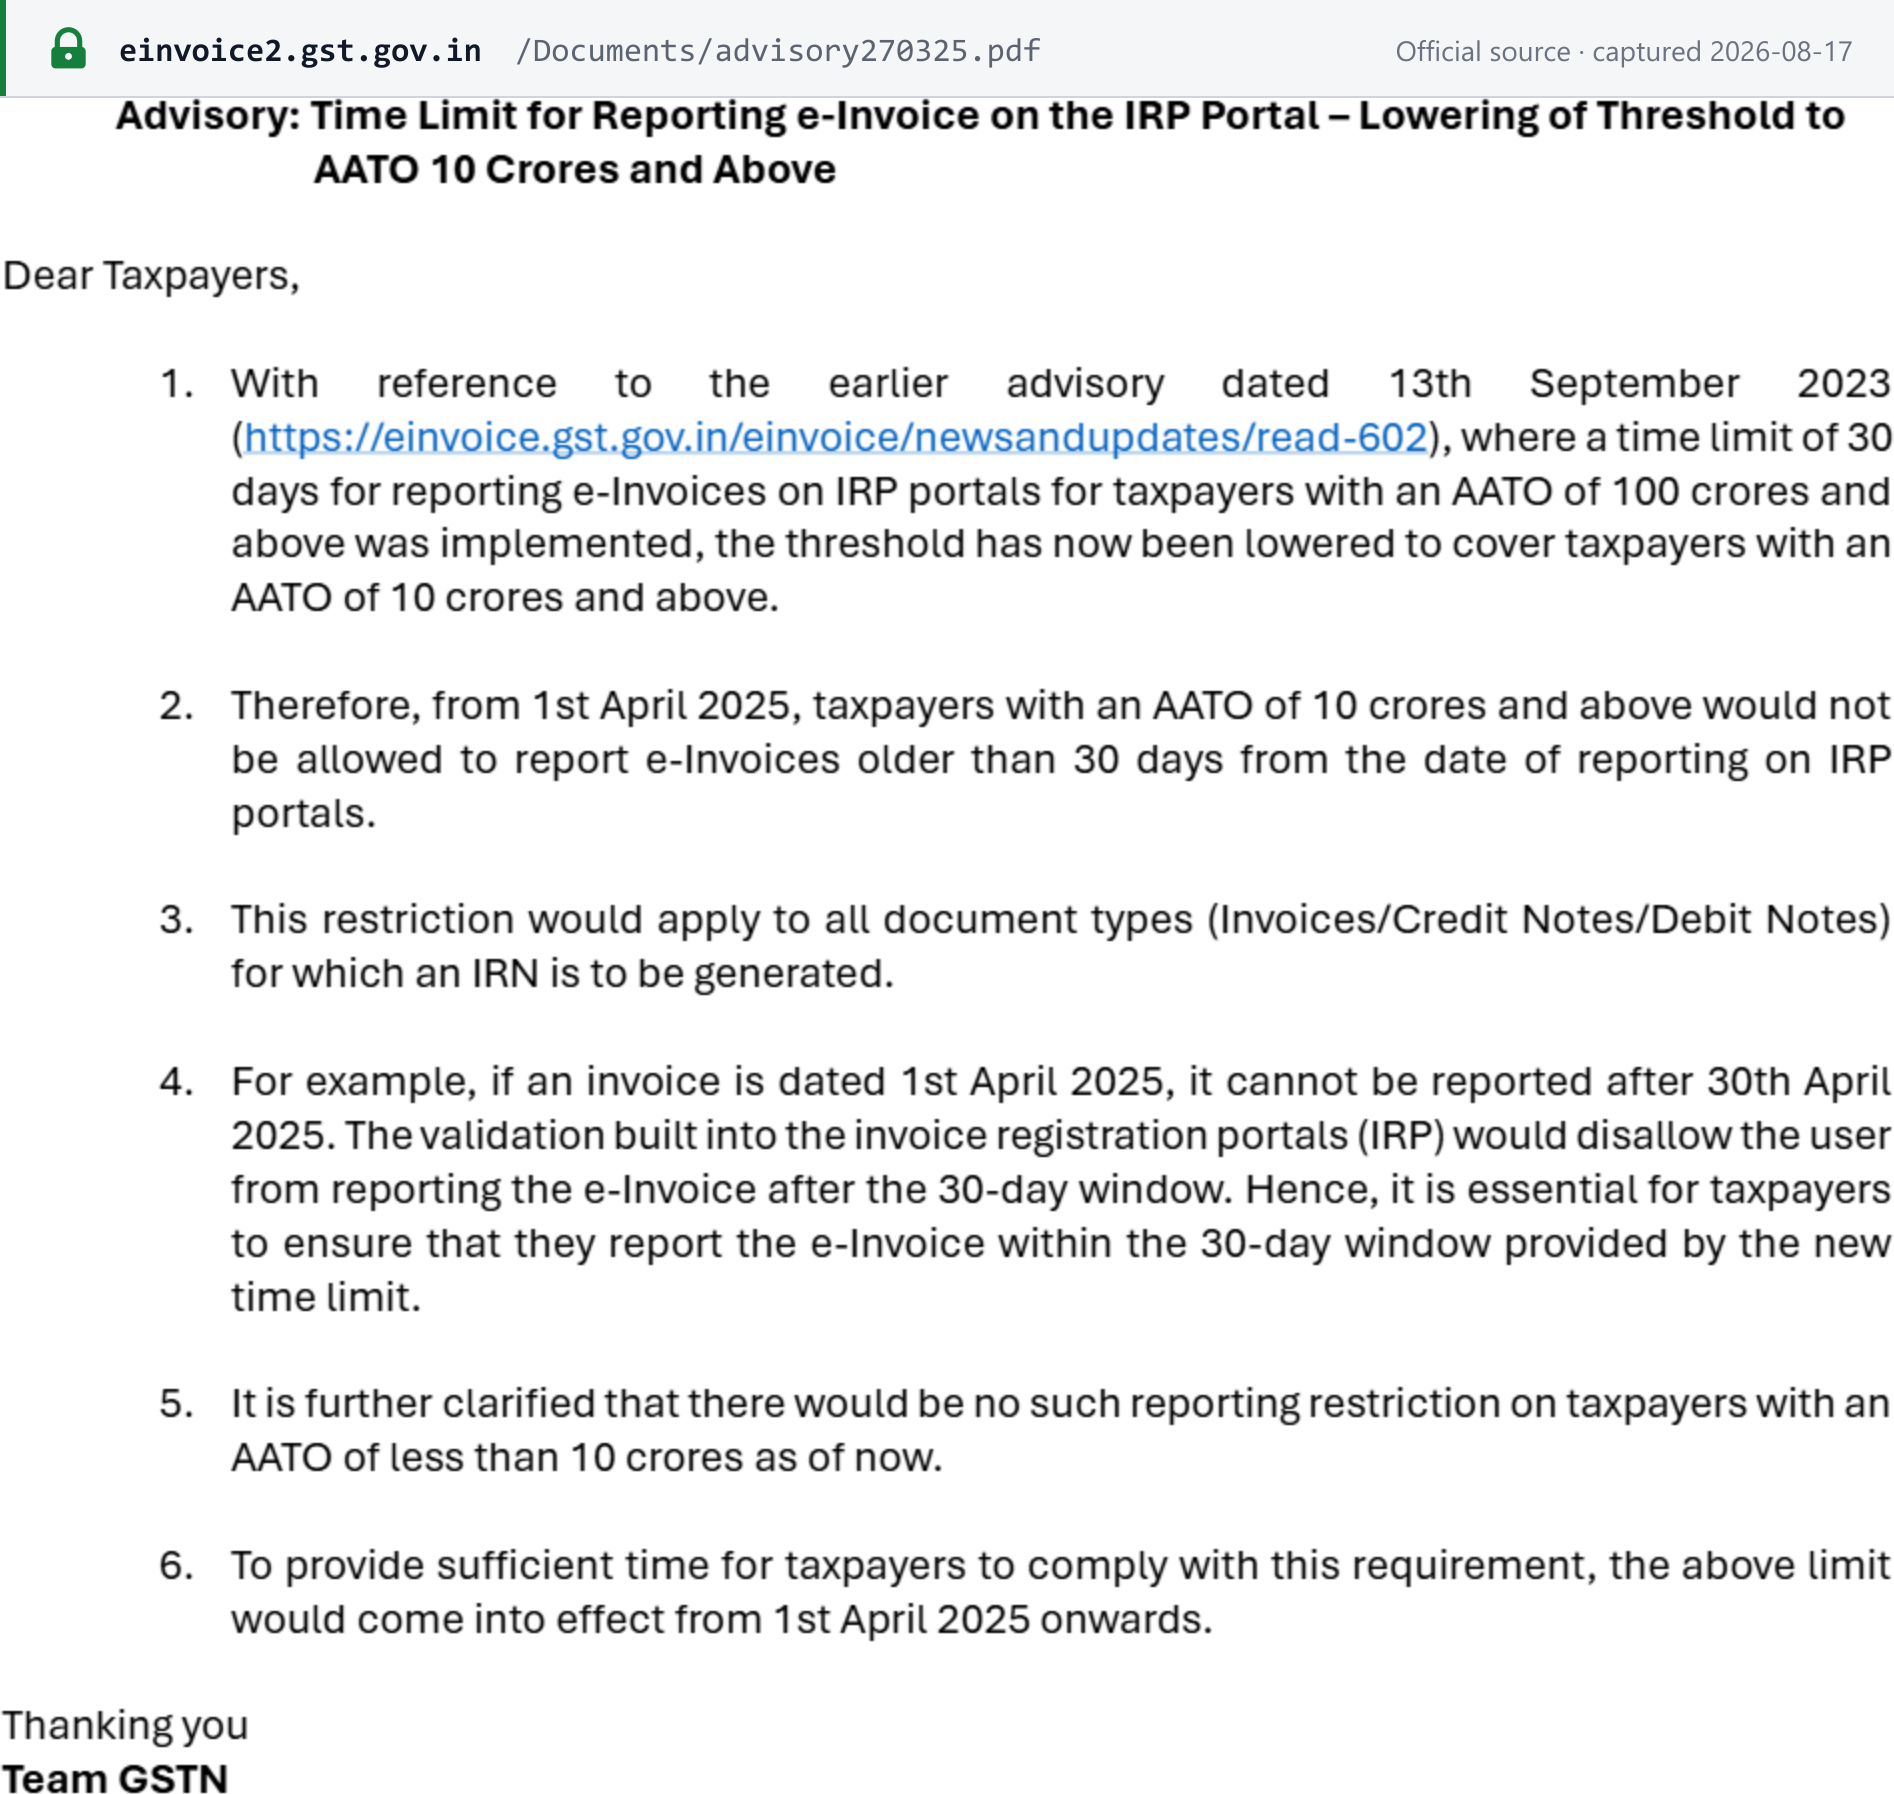
Reporting time limit: taxpayers with AATO of ₹10 crore and above must report an invoice to the IRP within 30 days of the invoice date, from 1 April 2025; the portal blocks IRN generation past that window. There is no reporting time limit below ₹10 crore (GSTN — advisory on the time limit for e-invoice reporting).
 Source snapshot captured 2026-08-17 — original
Failure to use it is not a paperwork slip: an invoice that should have been issued under Rule 48(4) but was not is not an invoice at all, which strips the customer's input tax credit as well.
Mechanics
Invoices are uploaded to the IRP, which returns an IRN (Invoice Reference Number) and a QR code. Under Rule 46(r) the QR code, with the IRN embedded in it, is a mandatory particular of the invoice given to the buyer. Because the invoice is electronic, no separate supplier signature is required — see the FAQ below. Invoices registered on the IRP are auto-populated into the supplier's GSTR-1 (GSTN — advisory on e-invoice data in GSTR-1).
e-Way Bill enhancements on hold
GSTN advisory of 29 July 2026 (GST portal news item 668) keeps on hold, until further notice, the e-Way Bill enhancements announced in the advisories of 9 and 17 June 2026 and the FAQs issued on 2 July 2026, which had been scheduled for 1 August 2026: mandatory Ship-To GSTIN in Bill-To/Ship-To transactions and the voluntary e-Way Bill closure facility. No production changes are required under those advisories, which together with the FAQs are to be withdrawn from the GST portal. No new date has been given (GSTN — news item 668).
Filing and payment
Which returns, and how often
Everyone registered under the normal scheme files two returns per period — an outward-supply statement and a summary-and-payment return.
| Return | What it is | Monthly filer | Quarterly filer (QRMP) |
|---|---|---|---|
| GSTR-1 | Outward supplies, invoice by invoice | 11th of the following month | 13th of the month after quarter-end |
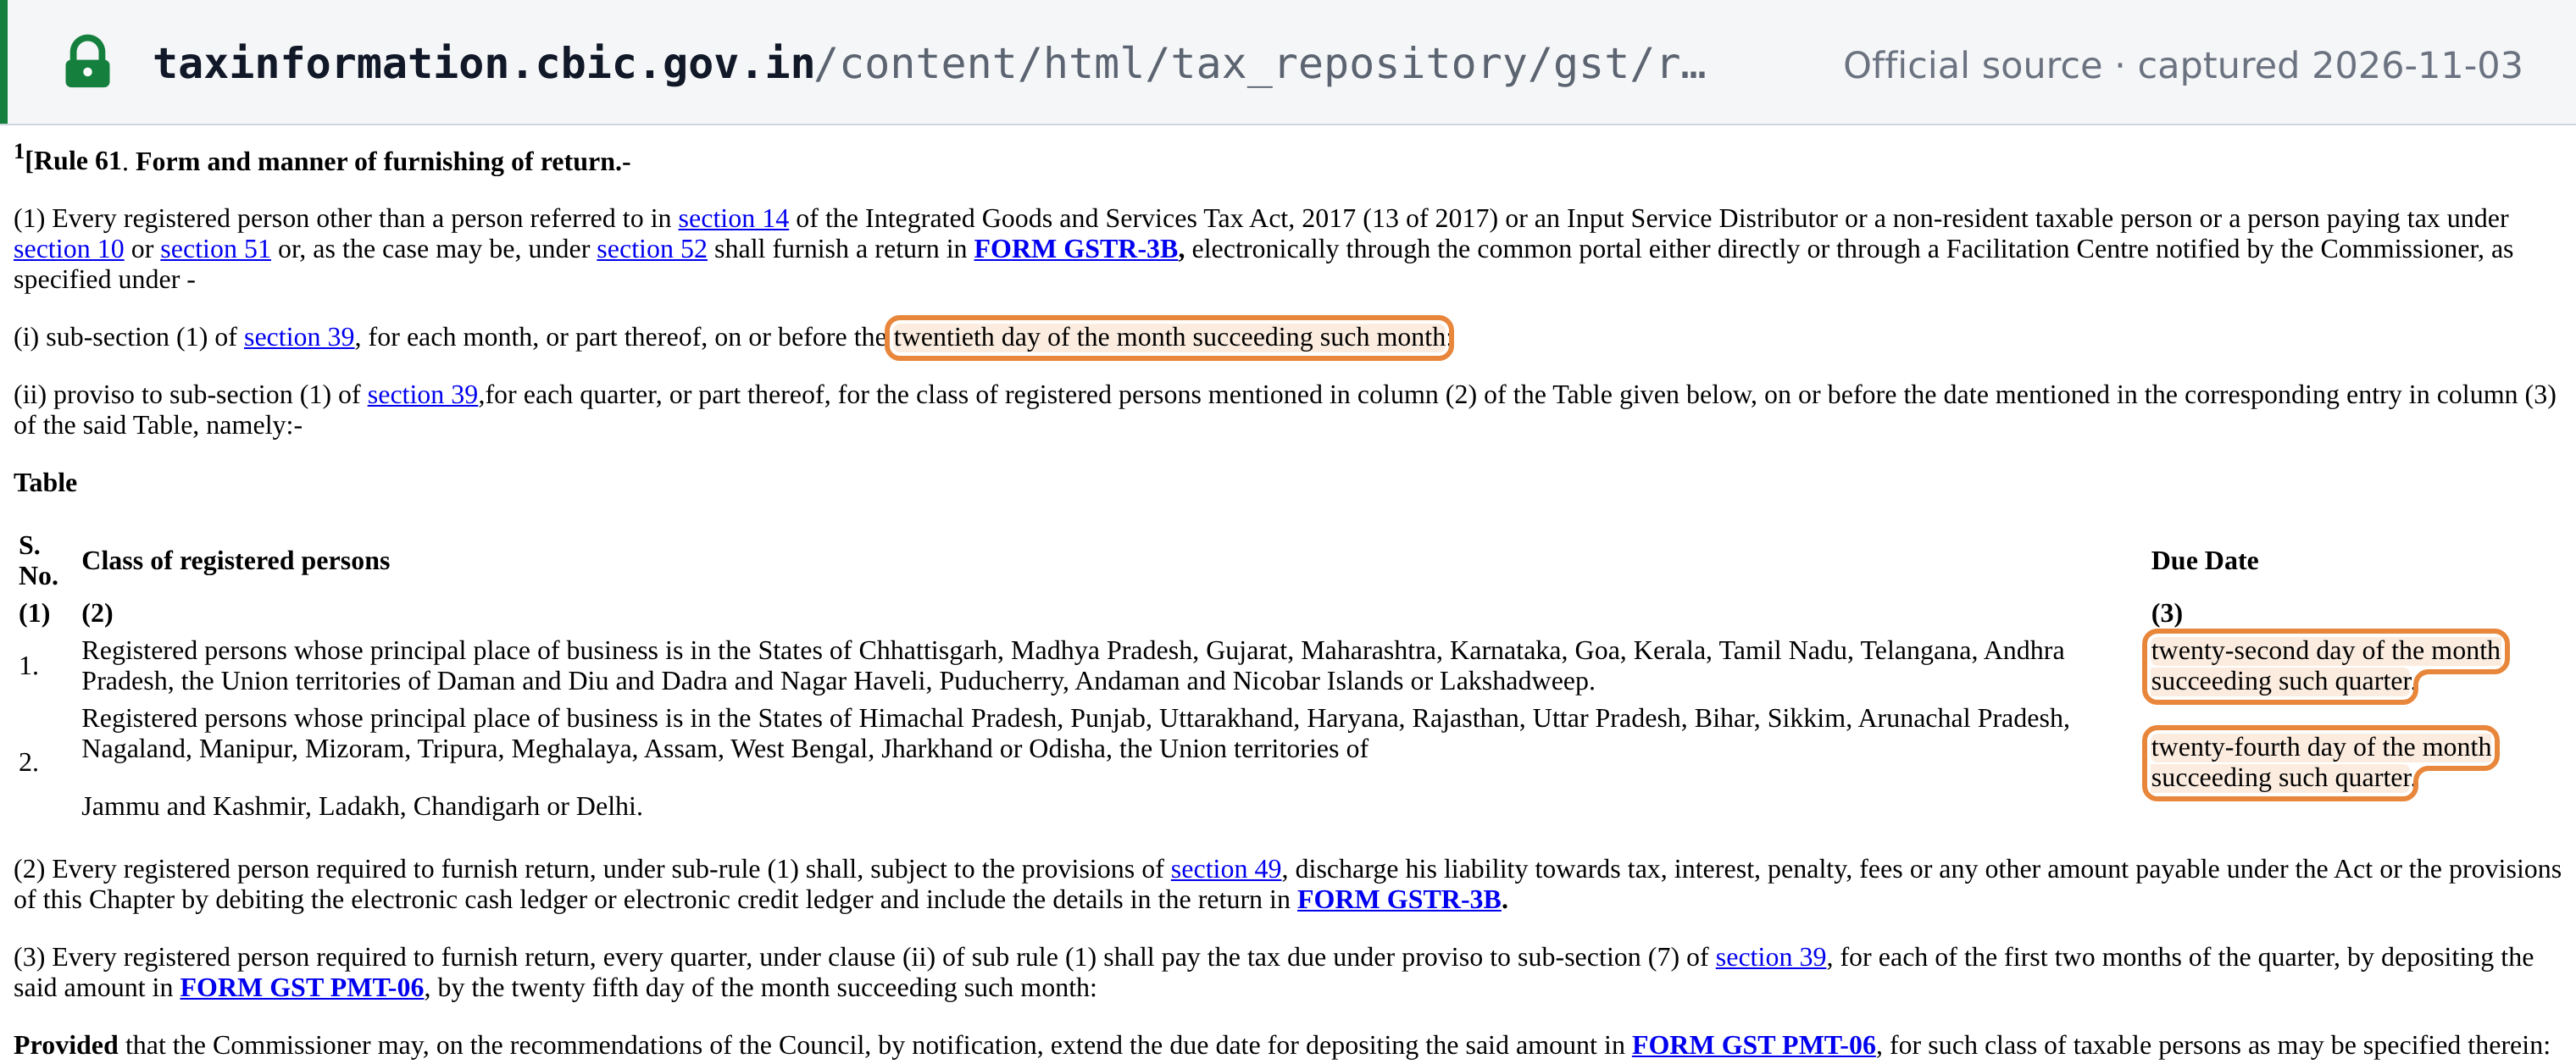
| GSTR-3B | Summary return; tax is paid with it | 20th of the following month | 22nd or 24th of the month after quarter-end, by State group |
GSTN's GSTR-1 user guide: "The due date to file Form GSTR-1 for a given tax period is 11th day of the succeeding month in case of taxpayers filing it monthly and 13th day of month succeeding the end of every quarter in case of taxpayers filing quarterly" (GSTN — GSTR-1 FAQ). The GSTR-3B dates are set by CGST Rule 61 (CBIC — CGST Rule 61).
 Source snapshot captured 2026-11-03 — original
What determines your frequency: aggregate turnover of ₹5 crore or less in the current and the preceding financial year makes you eligible for the QRMP scheme — Quarterly Return, Monthly Payment. Above ₹5 crore, filing is monthly and there is no choice. QRMP is opt-in and applies to both returns together: you cannot file GSTR-1 quarterly and GSTR-3B monthly.
Quarterly filers still pay monthly. Tax for the first two months of each quarter is deposited by challan (PMT-06, by the 25th of the following month), and only the return is quarterly. A quarterly filer who wants customers to see invoices sooner can use the Invoice Furnishing Facility (IFF) to upload B2B invoices in the first two months.
Invoice Management System (IMS). Since October 2024 recipients act on their suppliers' invoices before taking credit: "Invoice Management System (IMS) is a facility in GST system, where the invoices/records saved/filed by the supplier in GSTR-1/1A/IFF, can be accepted, rejected or kept pending by recipients in order to correctly avail ITC" (GSTN — FAQs on IMS, 22 September 2024).
Other returns
| Form | Who files it | When |
|---|---|---|
| GSTR-9 | Annual return. From FY 2024-25, persons whose aggregate turnover in the year is up to ₹2 crore are exempt (Notification 15/2025-Central Tax, 17 September 2025) | 31 December following the financial year (Rule 80(1)) |
| GSTR-9C | Reconciliation statement, aggregate turnover above ₹5 crore | With GSTR-9 |
| GSTR-5 | Non-resident taxable persons | Within 13 days after the end of the month, or within 7 days after the registration period ends, whichever is earlier (s.39(5); Rule 63 as amended by 05/2026-CT from 1 November 2026) |
| GSTR-5A | Overseas OIDAR suppliers | 20th of the following month (Rule 64) |
| GSTR-10 | Final return after cancellation | Within 3 months of the cancellation date or order, whichever is later (s.45) |
| CMP-08 | Composition taxpayers — quarterly statement and payment | By the 18th of the month after the quarter (Rule 62(1)) |
| GSTR-4 | Composition taxpayers — annual return | By 30 June following the financial year, from FY 2024-25 (Rule 62(1) proviso); for a person who leaves the scheme during the year, the same 30 June date applies from 1 November 2026 (Rule 62(5) as amended by 05/2026-CT) |
Notification 15/2025-Central Tax: the Commissioner, "in respect of filing of annual return for the financial year 2024-25 onwards, hereby exempts the registered person whose aggregate turnover in any financial year is up to two crore rupees, from filing annual return that said financial year" (CBIC — Notification 15/2025-CT). For CMP-08 and GSTR-4, see CBIC — CGST Rule 62; for the GSTR-9 due date, see CBIC — CGST Rule 80.
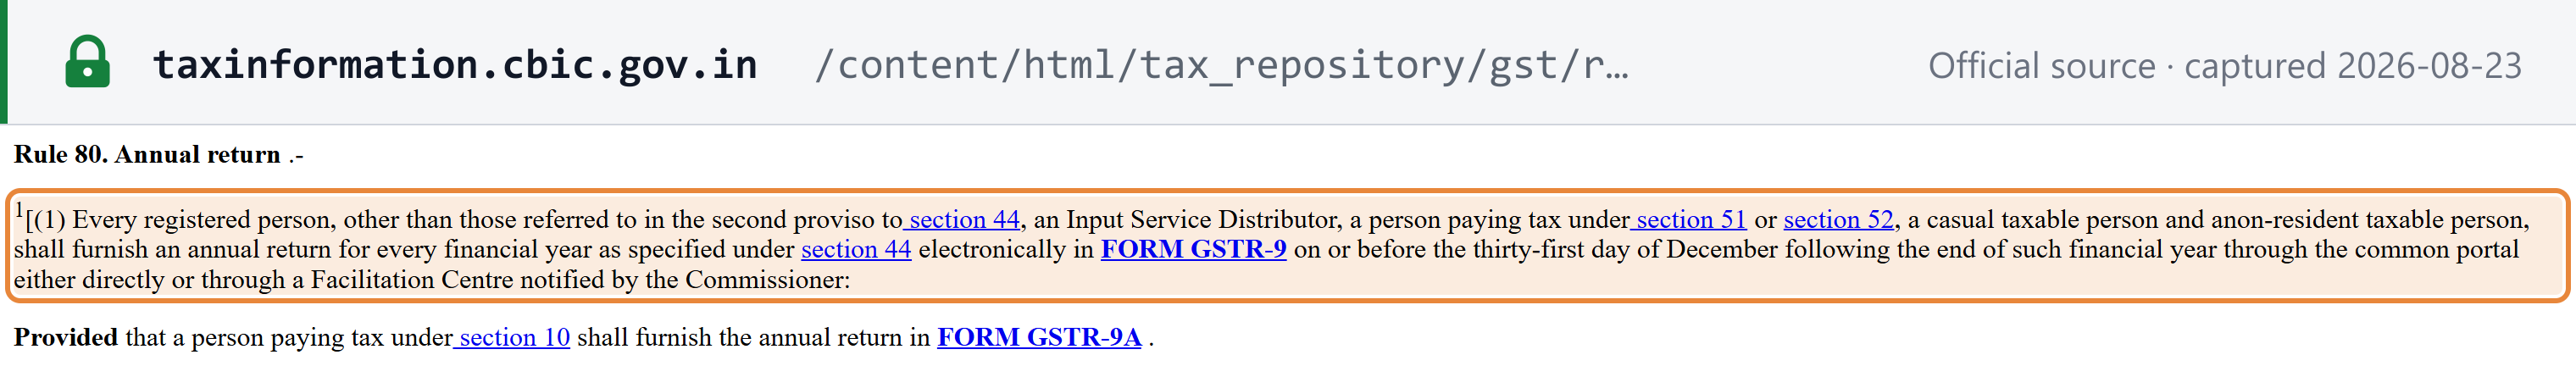 Source snapshot captured 2026-08-23 — original
Announced, not yet in force: the 57th GST Council (8 October 2026) recommended a new mechanism for amending returns from the April 2027 return period; see event.
Payment
Tax is paid through the electronic cash ledger on the GST portal, by net banking, NEFT/RTGS, card or over the counter (subject to limits). Liability is discharged with the GSTR-3B, so the payment deadline is the return deadline for monthly filers. Interest runs on late payment (see Penalties), and tax due under reverse charge must be paid in cash, not from the electronic credit ledger.
Input tax credit
Credit is available on inputs, input services and capital goods used in the course or furtherance of business, subject to conditions in section 16 — you must hold the invoice, have received the goods or services, the supplier must have paid the tax, and the invoice must appear in your auto-populated statement. Credit is time-barred: it cannot be taken "after the thirtieth day of November following the end of financial year to which such invoice or debit note pertains or furnishing of the relevant annual return, whichever is earlier" (CBIC — CGST Act s.16).
Blocked credits (section 17(5)) — no credit is available on: [21]
- Motor vehicles for passenger transport with an "approved seating capacity of not more than thirteen persons (including the driver)" — unless used for onward supply of such vehicles, passenger transport, or driving instruction. Vessels and aircraft are restricted on the same pattern, as are their insurance, servicing, repair and maintenance.
- Food and beverages, outdoor catering, beauty treatment, health services, cosmetic and plastic surgery, and life and health insurance — unless resupplied in the same category or forming part of a taxable composite supply.
- Works contract services for construction of immovable property, except where used for a further works contract supply; and goods or services used for construction of immovable property on one's own account.
- Goods or services received by a non-resident taxable person, except on imports.
- Corporate social responsibility activities under section 135 of the Companies Act, 2013.
- Goods or services used for personal consumption.
- Goods lost, stolen, destroyed, written off, or disposed of by way of gift or free samples.
Refunds
Refunds are claimed in FORM RFD-01, "before the expiry of two years from the relevant date" (section 54(1)) (CBIC — CGST Act s.54). The common grounds:
- Zero-rated supplies — either refund of unutilised credit (LUT route) or of the IGST paid (payment route). See Exports and SEZ supplies. Exporters of goods receive IGST refunds substantially automatically, matched against shipping-bill data.
- Inverted duty structure — where the rate on inputs exceeds the rate on outputs and credit accumulates. From 1 November 2026 the 90% provisional refund under section 54(6), previously limited to zero-rated supplies, also covers inverted-duty claims (section 155 of the Finance Act, 2026, in force by Notification 03/2026-CT).
- Excess balance in the electronic cash ledger.
Bad debt relief: not available. The CGST Act contains no mechanism to recover output tax on a receivable that goes bad — tax is due on the supply, and non-payment by the customer does not reverse it. The customer's credit is a different matter: a recipient who does not pay the supplier "within a period of one hundred and eighty days from the date of issue of invoice" must pay back the credit with interest (section 16(2) second proviso).
Exemptions
Exempt supplies are notified by rate notification rather than listed in the Act. For goods, the operative list is Notification 10/2025-Central Tax (Rate), which superseded Notification 2/2017-CT(Rate) with the September 2025 reform (CBIC — Notification 10/2025-CT(Rate)). Broad categories include unbranded staple foods, fresh produce, health and education services, and certain financial services.
Exempt is not the same as zero-rated, and the difference is money. Both carry no output tax. Only one preserves your input tax credit. The CGST Act also defines "exempt supply" to include a supply "which attracts nil rate of tax" (section 2(47)), so nil-rated supplies are treated as exempt:
| Output tax | Input tax credit on related purchases | |
|---|---|---|
| Zero-rated (exports, SEZ supplies) | None | Preserved — recoverable as a refund |
| Exempt (notified supplies) | None | Blocked — becomes a cost |
| Nil-rated (0% slab) | None | Blocked, same as exempt |
A business making exempt supplies alongside taxable ones must apportion credit under section 17(2) and reverse the exempt share. Treating an exempt supply as if it were zero-rated overstates recoverable credit, and it is the most common error in this area. See zero-rated vs exempt.
Composition scheme. Small suppliers may opt to pay tax at a flat rate on turnover instead of the normal mechanism. Under Notification 14/2019-Central Tax (7 March 2019), an eligible registered person "whose aggregate turnover in the preceding financial year did not exceed one crore and fifty lakh rupees" may opt in — ₹1.5 crore, or ₹75 lakh in Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, Tripura and Uttarakhand (GST Council — Notification 14/2019-CT). A composition taxpayer cannot charge GST on invoices, cannot claim input tax credit, and issues a bill of supply rather than a tax invoice, and files CMP-08 quarterly.
Special Economic Zones. Supplies to an SEZ developer or unit for authorised operations are zero-rated. An entity with both an SEZ unit and a domestic tariff area unit in the same State must hold separate registrations for each.
Offences and penalties
Offences and penalties are distinct exposures. The offence is the conduct; the penalty is the money; and for the more serious offences there is criminal prosecution on top of both.
Offences
Section 122(1) of the CGST Act lists the offences that attract a penalty (CBIC — CGST Act s.122):
- Making a supply without an invoice or with a false or incorrect invoice;
- Issuing an invoice without making a supply;
- Not paying tax collected for a period exceeding three months;
- Not paying tax collected in contravention of the Act for a period exceeding three months;
- Not deducting, or short-deducting, tax at source under section 51, or not depositing it;
- Not collecting, or short-collecting, tax at source under section 52, or not paying it;
- Taking or using input tax credit without actually receiving the goods or services;
- Fraudulently obtaining a refund;
- Taking or distributing input tax credit as an Input Service Distributor in violation of section 20;
- Furnishing false information, falsifying financial records or furnishing fake accounts or documents with intent to evade tax;
- Failing to register despite being liable to pay tax;
- Furnishing false information on registration particulars, at application or later;
- Obstructing or preventing an officer in the discharge of duty;
- Transporting goods without the prescribed documents;
- Suppressing turnover leading to tax evasion;
- Failing to keep accounts and documents in the manner specified, or to retain them for the period specified;
- Failing to furnish information or documents required by an officer, or furnishing false information or documents in proceedings;
- Supplying, transporting or storing goods liable to confiscation;
- Issuing an invoice or document using another person's GSTIN;
- Tampering with or destroying material evidence;
- Disposing of or tampering with goods detained, seized or attached under the Act.
Penalties
Figures below are the CGST amounts as at 4 November 2026; an equal amount generally applies under the State GST Act.
- Offences in section 122(1) — "ten thousand rupees or an amount equivalent to the tax evaded" (or the refund, credit or tax not deducted or collected), whichever is higher.
- Tax not paid or short paid, or credit wrongly taken (section 122(2)) — "(a) for any reason, other than the reason of fraud or any wilful misstatement or suppression of facts to evade tax, … a penalty of ten thousand rupees or ten per cent. of the tax due from such person, whichever is higher; (b) for reason of fraud … a penalty equal to ten thousand rupees or the tax due from such person, whichever is higher" (CBIC — CGST Act s.122).
- General penalty (section 125) — for a contravention with no separate penalty, "a penalty which may extend to twenty-five thousand rupees" (CBIC — CGST Act s.125). The 57th GST Council recommended cutting this to ₹10,000; that needs an amendment to the Act and is not law as at 4 November 2026.
- Late filing (section 47) — a late fee of "one hundred rupees for every day during which such failure continues subject to a maximum amount of five thousand rupees" for GSTR-1, GSTR-3B and the final return; for the annual return, up to "a quarter per cent. of his turnover in the State or Union territory" (CBIC — CGST Act s.47). For GSTR-3B from the June 2021 tax period, Notification 19/2021-Central Tax caps the CGST late fee at ₹250 where the tax payable is nil, ₹1,000 for aggregate turnover up to ₹1.5 crore and ₹2,500 for turnover above ₹1.5 crore up to ₹5 crore (GST Council — Notification 19/2021-CT). The late fee applies even to a nil return, and filing is sequential — a missed return blocks the ones after it.
- Interest (section 50) — on tax paid late, "at such rate, not exceeding eighteen per cent., as may be notified"; on input tax credit "wrongly availed and utilised", "at such rate not exceeding twenty-four per cent. as may be notified" (CBIC — CGST Act s.50).
Non-compliant invoicing. Failure to issue an invoice, or issuing an incorrect or false one, is an offence in its own right (items 1 and 2 above). Separately, an invoice that should have been issued under Rule 48(4) but was not is not a valid invoice, which denies the customer's input tax credit — commercially the larger exposure.
Prosecution
Section 132 makes the serious offences — including issuing an invoice without a supply, taking credit on such an invoice, and fraudulently obtaining a refund — punishable with imprisonment, scaled by the amount of tax evaded, credit wrongly availed or utilised, or refund wrongly taken (CBIC — CGST Act s.132):
| Amount involved | Maximum imprisonment |
|---|---|
| More than ₹5 crore ("five hundred lakh rupees") | Up to 5 years and fine |
| More than ₹2 crore, up to ₹5 crore | Up to 3 years and fine |
| More than ₹1 crore, up to ₹2 crore — only for the offence in clause (b), invoices issued without supply | Up to 1 year and fine |
The offences in clauses (a) to (d) punishable in the top band "shall be cognizable and non-bailable", and no one may be prosecuted "except with the previous sanction of the Commissioner". Certain offences may be compounded on payment. The 57th GST Council has recommended raising the prosecution threshold and removing the power of arrest; both need amendments to the Act and are not law as at 4 November 2026.
Frequently asked questions
We sell SaaS from outside India only to GST-registered Indian businesses. Do we have to register for GST in India?
Not because of those sales alone. Section 24(xi) of the CGST Act makes registration compulsory, with no threshold, for a person supplying online information and database access or retrieval (OIDAR) services from outside India to a person in India other than a registered person. Where the customer is registered, Notification 10/2017-Integrated Tax (Rate) makes the customer pay the IGST under reverse charge. Once you also sell to an unregistered customer in India, including an unregistered business, you must register in FORM GST REG-10, pay IGST on those sales and file GSTR-5A by the 20th of the following month. A registered overseas supplier then reports its supplies to registered persons in GSTR-5A as well (CGST Rule 64).
We only sell goods and our turnover is under 40 lakh rupees. Do we still need to register?
It depends on the State and on what you sell. Notification 10/2019-Central Tax, in force from 1 April 2019, exempts suppliers of goods only up to 40 lakh rupees of aggregate turnover, but not in Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Puducherry, Sikkim, Telangana, Tripura or Uttarakhand, and not for suppliers of ice cream, pan masala or tobacco. In those cases the section 22 threshold applies: 20 lakh rupees, or 10 lakh rupees in Manipur, Mizoram, Nagaland and Tripura. Aggregate turnover is counted across every State under the same PAN, and no threshold applies to the section 24 categories, such as non-resident taxable persons and persons making inter-State taxable supplies of goods.
Do reverse-charge self-invoices and imports of services need an IRN?
From 1 January 2027, yes, if you are in the e-invoicing class (aggregate turnover above 5 crore rupees in any preceding financial year from 2017-18 onwards). Notification 04/2026-Central Tax, dated 26 October 2026, widens the e-invoicing notification 13/2020-Central Tax to cover supplies received from an unregistered person where the recipient pays tax under reverse charge, and imports of services. Notification 05/2026-Central Tax moves FORM GST INV-01 to schema version 1.2 from the same date, adding the supply types RCMDOM (domestic supply from an unregistered person under reverse charge) and RCMIMP (import of services). Until then the e-invoicing notification covers only supplies to registered persons and exports.
We give our customers discounts after the sale. Can we issue a GST credit note for them?
From 1 November 2026, yes. Notification 03/2026-Central Tax, dated 26 October 2026, brought sections 153 to 155 of the Finance Act, 2026 into force on that date. They add a discount referred to in section 15(3)(b) as a ground for a credit note under section 34(1), and the substituted section 15(3)(b) excludes a post-supply discount from the value of supply only if the supplier issues a credit note and the recipient reverses the input tax credit attributable to the discount.
Do I need to add a digital signature on an e-invoice?
No. Rule 46(q) of the CGST Rules requires the signature or digital signature of the supplier on a tax invoice, but a proviso inserted by Notification 74/2018-Central Tax removes that requirement for an electronic invoice issued in accordance with the Information Technology Act, 2000. An e-invoice must instead carry the QR code with the Invoice Reference Number (IRN) embedded in it, under Rule 46(r).
Do I need to generate e-invoices for B2C sales?
No IRN is generated for B2C invoices: the e-invoicing notification 13/2020-Central Tax covers supplies to registered persons and exports. A separate rule applies to large suppliers. Under Notification 14/2020-Central Tax, as amended by Notification 71/2020-Central Tax, a registered person whose aggregate turnover in any preceding financial year from 2017-18 onwards exceeds 500 crore rupees must show a dynamic QR code on invoices to unregistered persons, from 1 December 2020. Insurers, banks and other financial institutions, goods transport agencies, passenger transport and multiplex cinema suppliers, and overseas OIDAR suppliers are outside that rule.
Important websites
Where the work actually happens, grouped by what you are trying to do. (Where a claim on this page came from is in Reference links below.)
Register, file and pay
| What for | Website |
|---|---|
| New registration | GST portal — new registration |
| File returns and pay | GST portal login |
| E-invoicing (IRP) | e-Invoice portal |
| E-way bills | e-Way Bill portal |
Look something up
| What for | Website |
|---|---|
| GSTIN lookup / verify a counterparty | GST portal — search taxpayer |
| HSN / SAC code search (the starting point for the rate) | GST portal — HSN/SAC search |
| GST user guides and FAQs | GSTN tutorials |
Law, policy and notifications
| What for | Website |
|---|---|
| GST Council (meetings, press releases, notification mirrors) | gstcouncil.gov.in |
| CGST and IGST Acts and Rules, consolidated | CBIC tax information portal |
| Notifications, including rate notifications | CBIC — explore notifications |
To check a GSTIN one at a time, use the GSTIN lookup and verification guide. For the format, checksum and structure of the number itself, see the India GSTIN tax identification number guide. To validate GSTINs in bulk or from your own systems, use the India GSTIN validation API.
Recent changes
- 2026-11-01 — Finance Act, 2026 sections 153 to 155 in force: post-supply discount credit notes and 90% provisional refunds for inverted-duty claims (Notification 03/2026-CT). The CGST (Amendment) Rules, 2026 take effect: Rule 14B registration on an e-commerce operator's warehouse, a 30-day window for cancellation applications under the new Rule 20, and the GSTR-5 due date in Rule 63 aligned to 13 days (Notification 05/2026-CT). Retreaded tractor tyres move to 5% (Notification 02/2026-CT(Rate)). (CBIC)
- 2026-10-26 — Notification 04/2026-CT extends e-invoicing from 1 January 2027 to supplies received from unregistered persons under reverse charge and to imports of services; FORM GST INV-01 moves to schema version 1.2 on the same date (Notification 05/2026-CT). (CBIC) — see event
- 2026-10-08 — 57th GST Council recommends a return-amendment mechanism from the April 2027 return period, a lower section 125 general penalty and changes to arrest and prosecution provisions. These are recommendations; the parts needing amendments to the Act are not law. (GST Council) — see event
- 2026-07-29 — GSTN advisory 668 keeps on hold, until further notice, the e-Way Bill enhancements that had been scheduled for 1 August 2026; no production changes are required and no new date is given. (GSTN) — see event
- 2026-05-01 — Beverage tariff-item codes updated in existing 5% and 40% entries, following the Finance Act, 2026 tariff changes (Notification 01/2026-CT(Rate)). (CBIC) — see event
- 2026-02-01 — Pan masala and tobacco move to 40% and biris to 18%; Schedule VII (14% CGST) omitted (Notification 19/2025-CT(Rate)); compensation cess set to Nil on all remaining goods (Notification 03/2025-Compensation Cess (Rate)). (CBIC)
- 2025-11-01 — Fast-track registration: Rule 9A (risk-based, three working days) and Rule 14A (opt-in for output tax to registered persons up to ₹2.5 lakh a month) (Notification 18/2025-CT). (CBIC)
- 2025-09-22 — Two-rate structure of 5% and 18% plus a 40% de-merit rate replaces the 5/12/18/28% slabs (Notification 9/2025-CT(Rate)); compensation cess removed from all goods other than pan masala and tobacco. (CBIC)
For the full chronology, see India tax changes on Lookuptax.
Reference links
Acts and Rules (CBIC consolidated text)
- CGST Act, 2017 — section 22 (persons liable for registration)
- CGST Act, 2017 — section 24 (compulsory registration)
- CGST Act, 2017 — section 31 (tax invoice)
- CGST Act, 2017 — section 34 (credit and debit notes)
- CGST Rules, 2017 — Rule 46 (tax invoice)
- CGST Rules, 2017 — Rule 48 (manner of issuing invoice)
- IGST Act, 2017 — section 13 (place of supply, cross-border services)
- CGST Act, 2017 — section 132 (punishment for certain offences)
Notifications
- Notification 9/2025-Central Tax (Rate) — goods rate schedules
- Notification 19/2025-Central Tax (Rate) — tobacco transition from 1 February 2026
- Notification 10/2019-Central Tax — ₹40 lakh goods threshold
- Notification 14/2019-Central Tax — composition thresholds
- Notification 13/2020-Central Tax — e-invoicing class
- Notification 01/2022-Central Tax — e-invoicing at ₹20 crore
- Notification 10/2023-Central Tax — e-invoicing at ₹5 crore
- Notification 15/2025-Central Tax — annual return exemption up to ₹2 crore
- Notification 18/2025-Central Tax — Rules 9A and 14A
- Notification 03/2026-Central Tax — Finance Act, 2026 sections 153 to 155 in force
- Notification 04/2026-Central Tax — e-invoicing scope from 1 January 2027
- Notification 05/2026-Central Tax — CGST (Amendment) Rules, 2026
Guidance
- GST Council — OIDAR services flyer
- NIC — GST e-invoice system detailed overview
- NIC — e-invoice user manual
- GST portal help modules
- GST concept and status, 2019 (historical CBIC overview)
Related on Lookuptax: