A Guide to the Import One Stop Shop (IOSS)
The Import One Stop Shop (IOSS) is a new scheme introduced as part of the EU’s eCommerce Package that came into effect on July 1, 2021. It allows suppliers selling goods from outside the EU to customers within the EU to collect and remit the VAT due at import through a simplified monthly return, instead of the VAT being collected at the time of importation.
The IOSS aims to simplify VAT collection on low-value imported goods and provides benefits for both suppliers and consumers. It enables suppliers to deal with VAT registration, collection, reporting and payment in the EU through a single point of registration. For consumers, it avoids unexpected additional VAT charges and delays on delivery that may occur if VAT is due at the point of importation.
Overview of the IOSS
Prior to July 1, 2021, goods imported into the EU with a value of less than €22 were exempt from VAT. On July 1, 2021, this low-value exemption was removed meaning VAT is now due on all goods imported into the EU regardless of their value.
To facilitate VAT collection and avoid delays for low-value goods, the eCommerce Package introduced the IOSS. This allows suppliers based outside the EU to collect, declare and pay import VAT for consignments not exceeding €150 in value through a monthly return in one EU Member State.
Use of the IOSS is optional. Suppliers not using the IOSS must pay import VAT at the time goods are imported as before.
Some key points about the IOSS:
- It can only be used for goods with a value of €150 or less, excluding excise goods (a draft Directive on which the Council reached a general approach on 9 November 2026 would remove this limit from 1 July 2028; it is not yet adopted — see below)
- VAT must be collected from the customer at the point of sale
- Suppliers or intermediaries acting on their behalf submit monthly VAT returns detailing VAT collected per EU Member State
- VAT is paid to the Member State of Identification by the end of the month following the month in which the customer's payment was accepted (the return period)
- Goods can pass through customs controls without payment of VAT if a valid IOSS VAT Identification Number is declared
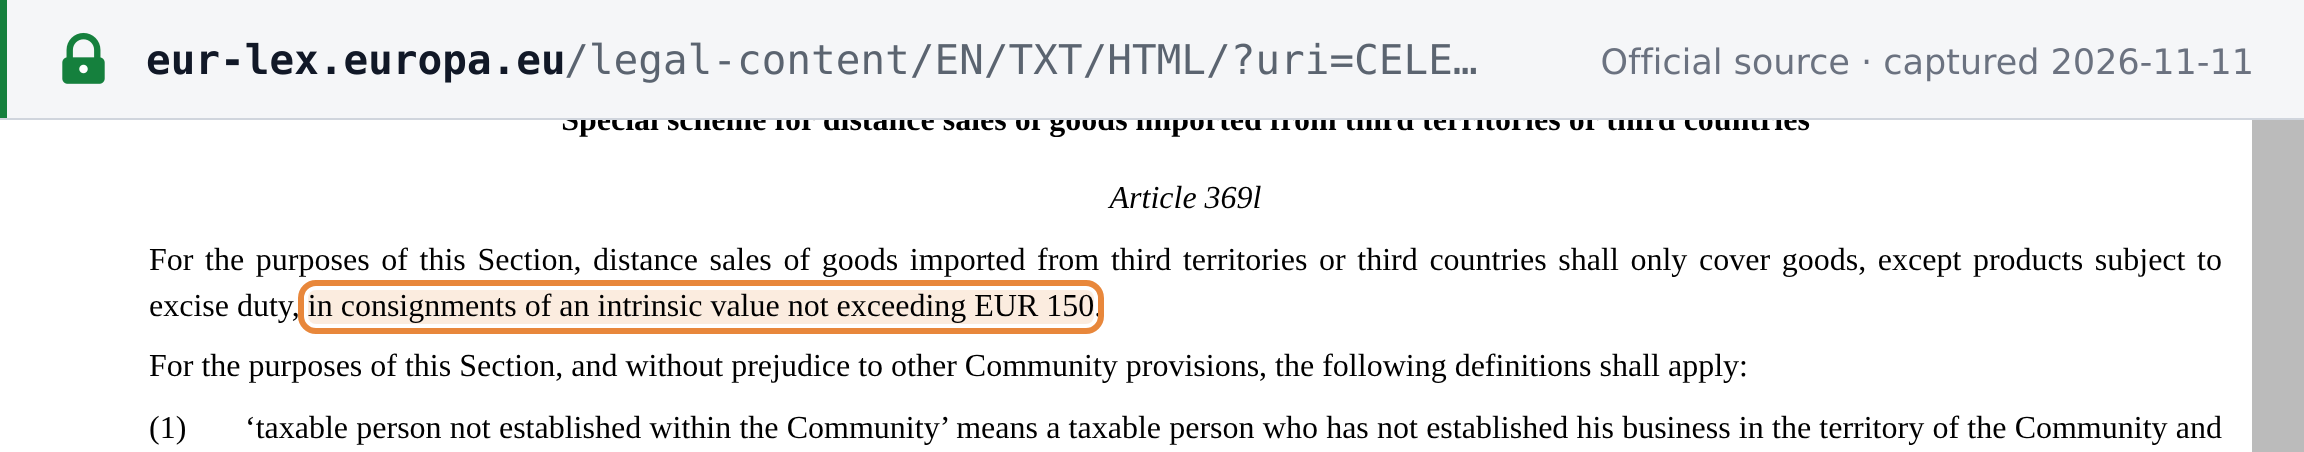 Source snapshot captured 2026-11-11 — original
Benefits of the IOSS
Use of the IOSS provides important benefits and simplifications for both suppliers and consumers.
For suppliers, the key benefits are:
- VAT registration in just one EU Member State to cover all EU distance sales of imported goods up to €150
- Single monthly return and payment to cover VAT due across the EU
- No payment of import VAT at the border which speeds up customs clearance
For consumers, the benefits are:
- VAT is paid at point of sale so no unexpected VAT charges or delays on delivery
By declaring and paying VAT upfront through the IOSS, the process of importing low value goods is significantly streamlined.
Suppliers avoid having to register for VAT separately in all Member States into which they import goods. For consumers, delivery delays and administrative hassles are reduced as VAT has already been collected and customs simply have to confirm the validity of the IOSS VAT ID.
Supplies Covered by the IOSS
The IOSS can only be used for specific types of supplies of goods. To fall within the scope of the scheme, all of the following conditions must be met:
- Goods must be located outside the EU at the time of sale
- Goods must be sold via distance selling to non-taxable customers in the EU
- Goods must be physically transported or dispatched from outside the EU to customers in the EU
- Goods must be dispatched in consignments not exceeding €150 in intrinsic value
- Goods cannot be subject to excise duties
Distance selling refers to situations where the supplier is responsible for the transportation or dispatch of the goods from outside the EU. This includes where the supplier engages a third party to deliver the goods to the customer.
The intrinsic value refers to the value of the goods themselves excluding transport and insurance costs, unless those costs are included in the sales price and not itemized separately on the invoice.
Types of goods excluded from the IOSS besides excise goods are new transport vehicles and goods supplied after assembly or installation in the EU. Goods already stored in an EU warehouse cannot be sold under the distance selling arrangements of the IOSS.
Who Can Use the IOSS?
The IOSS can be used by suppliers established both within and outside the EU.
Suppliers established within the EU can register for the IOSS in their own Member State to account for VAT on eligible distance sales of imported goods from outside the EU.
Suppliers established outside the EU can also access the IOSS but through different mechanisms depending on where they are based:
- Suppliers based in third countries covered by a relevant mutual assistance agreement (currently only Norway) can register directly in any Member State
- Suppliers based in all other non-EU countries must appoint an intermediary established in the EU to fulfill IOSS obligations on their behalf
Electronic interfaces such as marketplaces can also use the IOSS as deemed suppliers if they facilitate sales by third country suppliers to EU consumers and those sales are distance sales of imported goods within the scope of the scheme.
ViDA Widens the Deemed-Supplier Rule's Customer Group (From 2027)
The deemed-supplier rule — a marketplace, not the underlying seller, accounts for the VAT — has applied since 1 July 2021 in two limbs of Art 14a: imported consignments of EUR 150 or less (14a(1)) and goods already in the EU sold by a seller not established in the EU, at any value (14a(2)). Directive (EU) 2025/516 does not newly bring intra-EU supplies into the rule; they have been covered since 2021. From 1 January 2027 its recast Art 14a(2) also covers sales to taxable persons and non-taxable legal persons whose intra-Community acquisitions of goods are not subject to VAT under Article 3(1) ('Schwellenerwerber') (Art 2(1), Art 6(2)). See marketplace deemed-supplier rules for how both limbs work.
As with the rest of Article 2, national transposition is running at two different speeds:
- Malta — already law. The Budget Measures Implementation Act, 2026 (Act III of 2026, Government Gazette of Malta No. 21,599, published 10 March 2026) amends the VAT Act (Cap. 406); per the Malta Tax and Customs Administration's explanatory notes, the substituted item 12A(2) of the Second Schedule "extends the deemed supplier rule for e-commerce platforms facilitating supplies of goods within the EU made to taxable persons, or a non-taxable legal person, whose intra-community acquisitions of goods are not subject to VAT pursuant to article 3(1) of the EU VAT Directive", in force from 1 January 2027. (Malta Tax and Customs Administration explanatory notes; legislation.mt, checked 2026-09-20)
- Poland — a draft. On 2 September 2026 Poland's Council of Ministers backed, but did not pass, a VAT Act amendment that "clarifies which supplies count as facilitated by electronic interfaces," also targeting 1 January 2027; it has not yet cleared the Sejm. (Ministerstwo Finansów, gov.pl, checked 2026-09-20)
For a marketplace already running IOSS deemed-supplier obligations for imports, the practical takeaway is: from 1 January 2027, Art 14a(2) deemed-supplier treatment also reaches a non-EU seller's EU-stock sales to Article 3(1) customers; sales to consumers have been covered since July 2021. That is a separate liability from the IOSS import flow, and one to confirm jurisdiction by jurisdiction, since Malta's version is settled and Poland's is not. See ViDA — VAT in the Digital Age for the full national-transposition picture and Guide to the VAT One Stop Shop for the companion EUR 10,000 threshold clarification and call-off-stock phase-out that land alongside it.
Proposed: Removal of the EUR 150 Limit (Council General Approach, 9 November 2026)
Status: proposed, not adopted (as at 2026-11-11). On 9 November 2026 the Council of the EU reached a general approach on the draft Directive amending the VAT Directive (2006/112/EC) on taxable persons who facilitate distance sales of imported goods and on the IOSS (Council doc 15179/26, procedure 2023/0158 CNS). The text deletes the EUR 150 consignment-value limit from both the deemed-supplier rule (Art 14a(1)) and the IOSS, so that both would apply to distance sales of imported goods of any value. Recital (2) says the deemed-supplier regime "should cover all distance sales of goods imported from third territories or third countries into the Union, irrespective of their value"; recital (3a) gives the reason for the IOSS change — so that sellers "are not obliged to register for import VAT in each Member State of destination of the goods".
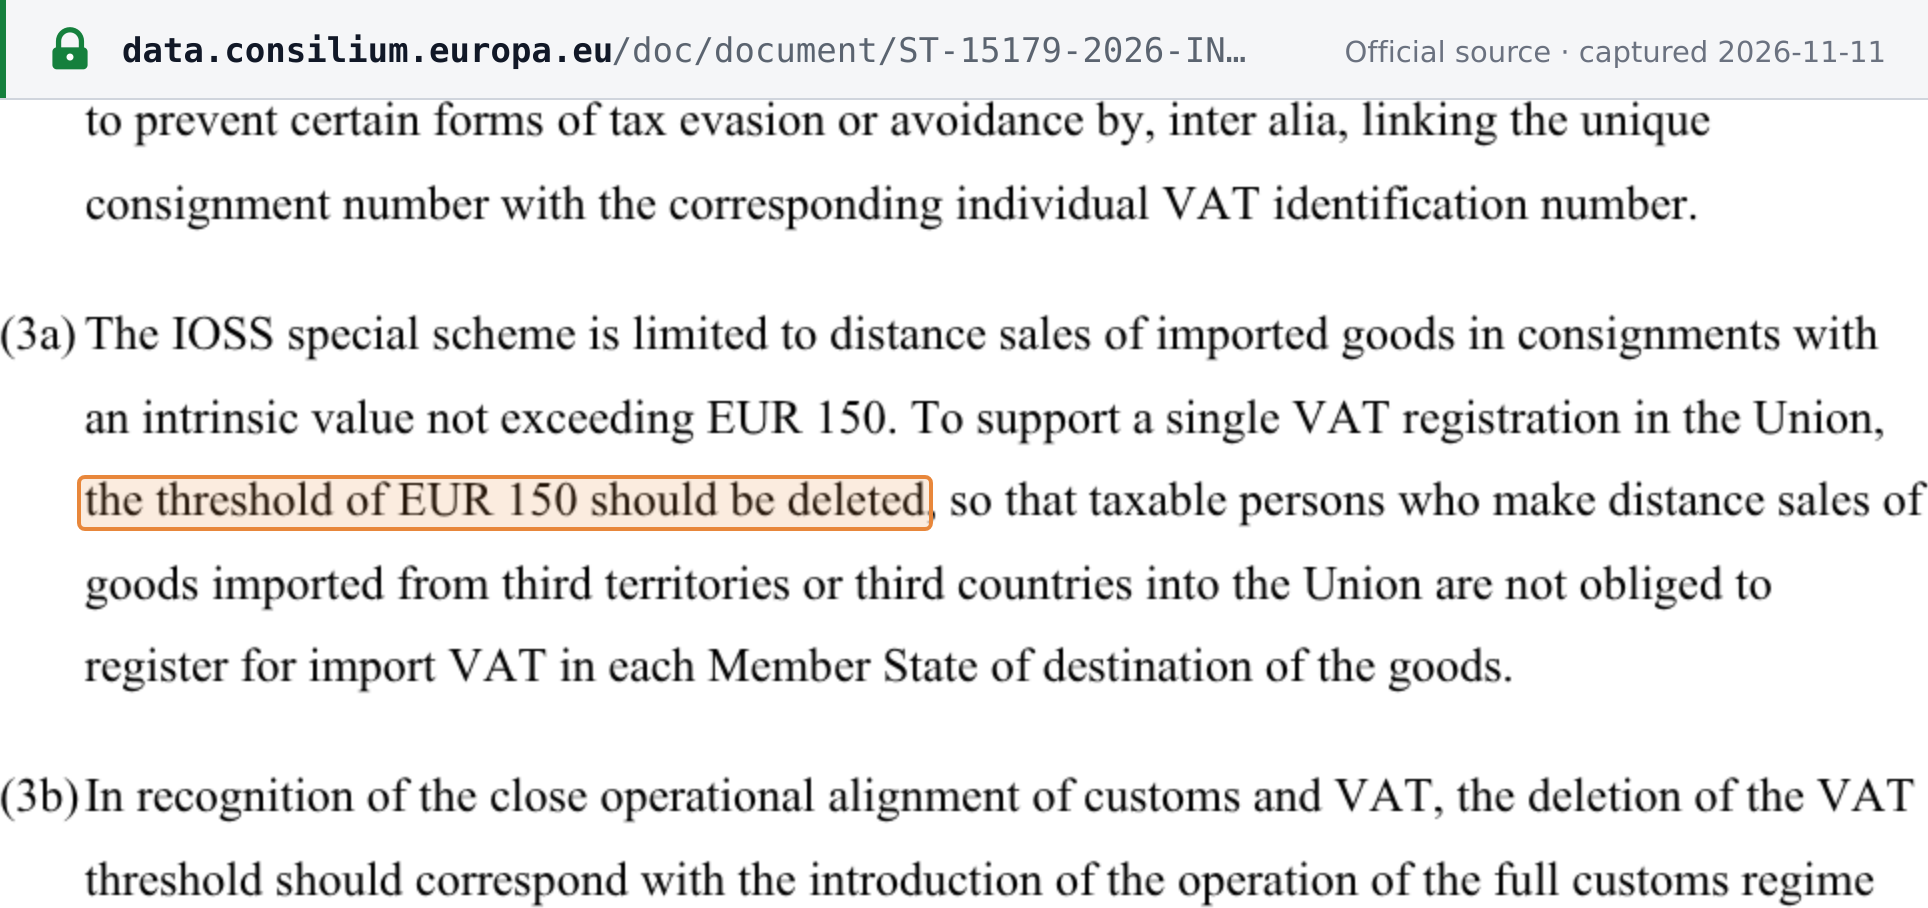 Source snapshot captured 2026-11-11 — original
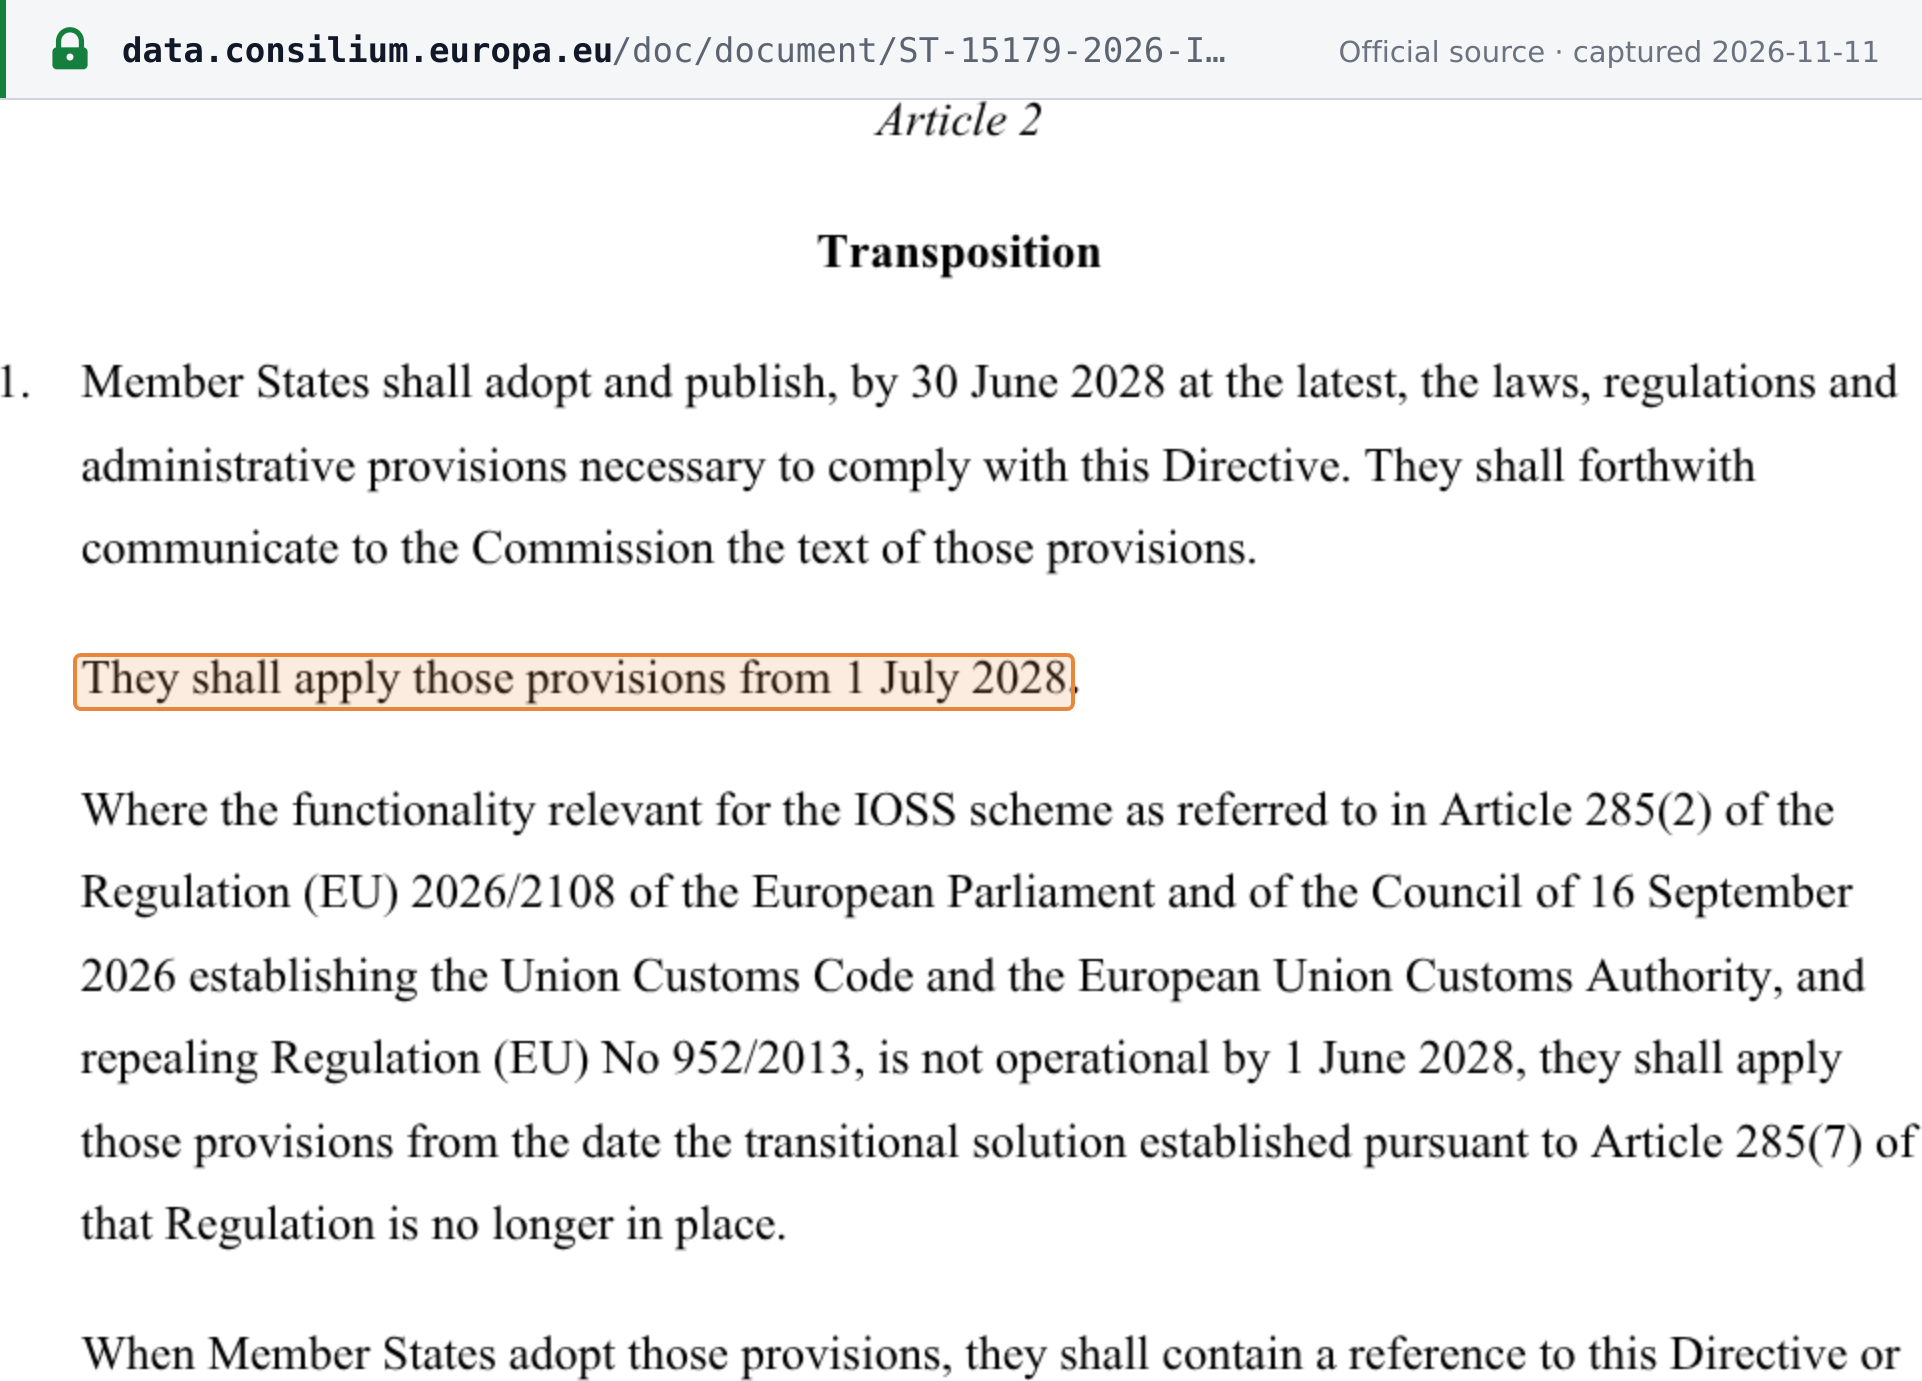 Source snapshot captured 2026-11-11 — original
(Council of the EU — doc 15179/26)
Dates in the draft. Member States would adopt their transposing laws by 30 June 2028 and "shall apply those provisions from 1 July 2028" (Article 2). The draft adds a fallback: if the IOSS functionality of the new customs system under Regulation (EU) 2026/2108 is not operational by 1 June 2028, the provisions apply only once the customs transitional solution ends. The change is aligned with the customs reform, which removes the EUR 150 customs-duty relief. (Council of the EU — doc 15179/26)
What still has to happen. A general approach is the Council's agreed position, not law. The European Parliament gave its opinion on the original proposal on 22 November 2023 and must be consulted again on the Council's text before the Council can formally adopt the Directive. Until then, the EUR 150 limit described on this page remains the rule.
New Union Customs Code: the "Importer for Distance Sales" (From 21 September 2027)
Regulation (EU) 2026/2108 of 16 September 2026, published in the Official Journal on 19 September 2026, establishes a new Union Customs Code and the European Union Customs Authority and repeals the current Union Customs Code, Regulation (EU) No 952/2013. Article 5, point (14) defines an "importer for distance sales" as "either the person supplying goods in distance sales or the person facilitating distance sales", and point (15) gives "distance sales" the meaning of distance sales of imported goods in Article 14(4), point (2) of the VAT Directive — the category of sales the IOSS applies to for consignments up to EUR 150. Recital 62 states that "there should be only one importer at a time"; recital 63 explains that for distance sales the importer is either the supplier or the person facilitating the sales, depending on the arrangements made. (EUR-Lex)
The Regulation entered into force the day after publication but applies from 21 September 2027 (Article 287(2)). A short list of provisions applies earlier, from entry into force — including the point (15) definition of distance sales — but the point (14) "importer for distance sales" definition is not among them. (EUR-Lex)
VAT Registration for the IOSS
The process for registering for the IOSS depends on whether the supplier is based within or outside the EU.
Suppliers established in the EU (including electronic interfaces deemed to be suppliers):
- Register directly in their own Member State
- Provide name, address, VAT number and website
- Will be issued an IOSS VAT Identification Number
Suppliers established outside the EU:
- If based in Norway, can register directly in any Member State
- If based elsewhere, must appoint EU-established intermediary
- Provide name, address, VAT no (if registered outside EU), website
- Intermediary will be issued IOSS VAT ID Number to use
Member State of Identification:
- For EU and Norway suppliers - Member State of registration
- For other 3rd country suppliers - Member State where intermediary is established
Registration is done electronically through the VAT OSS portal for the Member State of Identification.
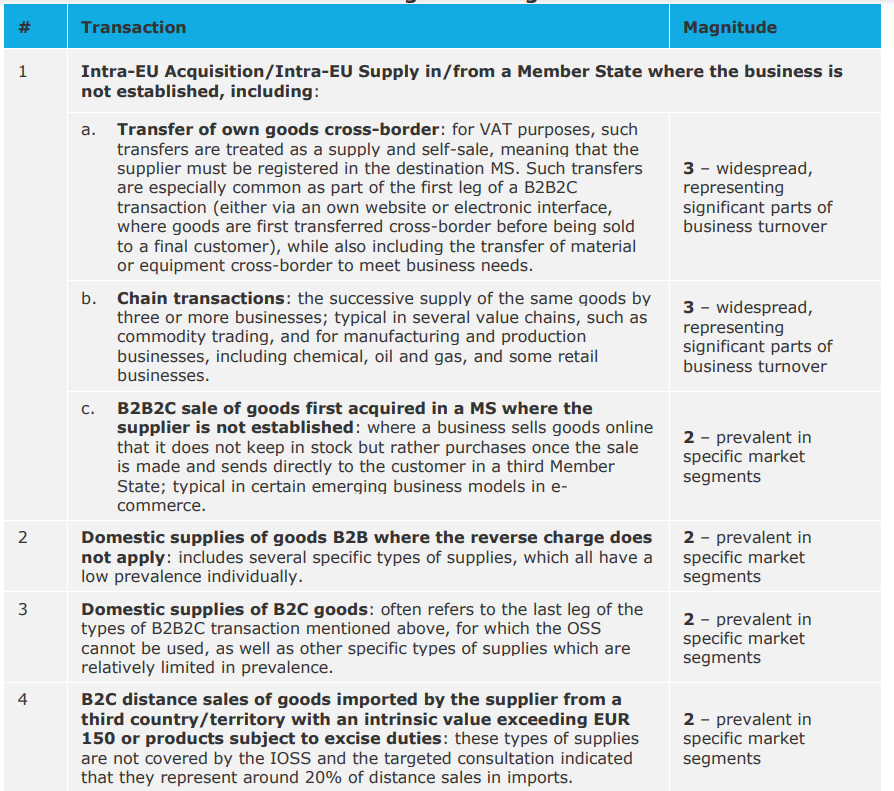 |
| Summary of transactions that require VAT registration by nonestablished businesses and their degree of magnitude |
The Role of Intermediaries
Suppliers based outside the EU, except those in Norway, must appoint an EU established intermediary to fulfill IOSS obligations on their behalf.
An intermediary is a taxable person established in the EU who registers and declares IOSS VAT on behalf of the third country supplier. The intermediary is responsible for:
- Registering the supplier for the IOSS
- Filing monthly IOSS VAT returns
- Paying the VAT due to the tax authorities
The intermediary is appointed as the person liable for payment of the IOSS VAT and fulfils the scheme's obligations in the supplier's name and on its behalf.
Key points about IOSS intermediaries:
- Must have an establishment in the EU
- Does not need to be an IOSS specialist and can conduct other business activities
- Subject to normal VAT registration requirements in Member State of establishment
- Must register as an intermediary before acting on behalf of IOSS suppliers
- Will be issued a unique IOSS Identification Number
- Can represent multiple suppliers at the same time
While optional for EU suppliers, the use of intermediary is mandatory for imports under IOSS by suppliers based outside the EU and Norway.
Registering as an Intermediary
Persons established in Ireland who wish to act as intermediaries for IOSS suppliers must take the following steps:
- Obtain a Tax Advisory Identification Number (TAIN)
- Apply by post or email to the National TAIN Unit
- Register for VAT in Ireland if not already VAT registered
- Register as IOSS intermediary via Revenue Online Service (ROS)
- Will be issued a unique IOSS Identification Number (IN)
- For each supplier represented, submit IOSS Intermediary Link Notification Form
- Issued separate IOSS VAT ID for sales by each supplier
The registration process ensures the intermediary has been authorized to act on behalf of third country IOSS suppliers before an IOSS VAT Identification Number is issued.
When Registration Takes Effect
Registration for the IOSS takes effect from the date the VAT Identification Number is issued to the supplier or intermediary. This enables immediate use of the IOSS scheme.
For EU suppliers, this is the date of issue of their individual IOSS VAT ID after submitting VAT registration details.
For third country suppliers, it is the date the intermediary receives the IOSS VAT ID associated with that supplier, after submitting the Intermediary Link Notification Form.
No sales can be declared retroactively or before the issuance of the VAT Identification Number.
Using the IOSS
When making sales under the IOSS, the supplier must:
- Charge the applicable VAT rate to the customer at the point of sale
- Obtain evidence that VAT has been paid by the customer
- Ensure the correct IOSS VAT ID is provided to customs for import clearance
- Submit monthly IOSS VAT returns detailing sales and VAT collected
The VAT rate to be charged is that which applies in the EU Member State where the customer receives the goods. This is known as the Member State of Consumption.
The Taxes in Europe Database from the EU Commission has details of all VAT rates in force and can help identify the relevant VAT rate.
The VAT collected must be declared and remitted to the Member State of Identification via the monthly IOSS VAT return submitted electronically by the end of the next month.
The return breaks down the total VAT due into the amounts relating to each Member State of Consumption. The VAT is paid to the Member State of Identification along with the return submission.
VAT Return Filing and Payment Obligations
Suppliers or their intermediaries have obligations for reporting under the IOSS they must comply with.
The key obligations are:
Monthly VAT Return Submissions
- Must be submitted electronically by end of month following the return period
- Nil returns must also be submitted if no sales took place
Return Details
- Breakdown of VAT collected per Member State of Consumption
- Total value of goods per Member State and applicable VAT rate
- Total VAT amount payable
Payment Deadlines
- Full VAT amount to be paid by deadline for return submission
- Paid electronically to bank account in Member State of Identification
Reminders are issued by the tax authority if returns are not submitted or VAT is unpaid. Persistent failures can result in exclusion from the IOSS.
Record Keeping Requirements
Suppliers must retain records of transactions covered by the IOSS for a period of 10 years. Sufficiently detailed records must be made available electronically on request.
The information to be recorded includes:
- Description, quantity, value of goods
- Customer details, invoices
- VAT rates applied and VAT amounts collected
- Evidence of payment
- Delivery details and proof of returns
- Unique order or transaction numbers
EU Member States can request access to these records to verify the accuracy of IOSS VAT returns.
Keeping proper electronic records enables suppliers to comply swiftly with information requests from tax authorities.
Correcting Submitted VAT Returns
Corrections to IOSS VAT returns already submitted must be done through an amendment on a subsequent VAT return.
Amendments are made as follows:
- Select amended return and the Member State of Consumption
- Enter additional or reduced VAT amount attributable to that Member State
- Provide details of the original VAT return period for the transaction
Direct amendments to previously submitted returns are not possible under the IOSS. The self-correction approach avoids the need to submit separate credit or debit notes.
VAT Recovery
Input VAT incurred in the course of IOSS activities cannot be recovered through the IOSS VAT return.
Suppliers must recover input VAT through the normal procedures applicable in each Member State, namely:
- The 13th Directive refund process for non-EU businesses
- The 8th Directive refund process for EU businesses not registered in that Member State
- Deduction through the normal VAT return if registered for domestic business there
The IOSS serves only as a simplified mechanism for collecting and declaring EU import VAT. It does not provide a means for recovering VAT.
Currency Conversion
Where IOSS sales have been made in currencies other than euro, the VAT return must convert amounts to euro using the European Central Bank exchange rate.
The applicable exchange rate is the rate published on the last day of the return period, or where unavailable, the next published rate.
Consistent use of European Central Bank rates ensures fairness and prevents distortions when translating foreign currency transactions into local VAT returns.
Alternatives to the IOSS
While it provides major benefits, use of the IOSS is not mandatory for suppliers.
Suppliers can opt to pay import VAT through normal customs clearance rules and procedures. In that case, VAT will be due at the time of import declaration along with any customs duties.
Where the IOSS is not used for consignments up to EUR 150, the person presenting the goods to customs (typically a postal operator or courier) may use the special arrangements: it collects import VAT from the customer and pays it monthly. Council Directive (EU) 2025/1539 of 18 July 2025, already adopted, deletes these special arrangements from 1 July 2028 and makes the supplier or deemed supplier liable for import VAT on IOSS-eligible distance sales where the IOSS is not used. [Directive 2025/1539]
De-registration and Removal from the IOSS
Suppliers or intermediaries can voluntarily de-register from the IOSS by informing the tax authority in the Member State of Identification at least 15 days before the end of the month.
Involuntary removal from the IOSS can occur if:
For suppliers:
- Cease trading or no longer carrying out relevant activity
- No longer meet IOSS eligibility conditions
- Persistent non-compliance with rules e.g. late filing/payment
For intermediaries:
- Do not act on behalf of IOSS supplier for 2 consecutive quarters
- No longer meet conditions for acting as intermediary
- Persistent non-compliance e.g. late filing/payment
A supplier excluded for persistent non-compliance is barred from all the special schemes for two years following the return period of exclusion; an intermediary deleted for persistent non-compliance cannot act as one for two years following the month of deletion.
Existing MOSS Registrations
Prior to the IOSS, the VAT MOSS scheme applied to cross-border digital services.
MOSS registrations have been automatically migrated over to the new VAT OSS scheme covering digital services.
Suppliers registered under MOSS or the current OSS who also want to use the IOSS must specifically register for it separately. IOSS registration does not happen automatically.
Key Concepts
Some key concepts and terms used in relation to the IOSS are:
- Distance sales of imported goods – goods transported from outside the EU where supplier is responsible for that transportation
- Consignment – goods dispatched simultaneously in same commercial shipment
- Intermediary – EU based taxable person who handles IOSS compliance on behalf of supplier
- Intrinsic value – price of the imported goods excluding transport or insurance costs
- Member State of consumption – where buyer receives imported goods
- Member State of identification – where IOSS registration held
- Taxable person not established in EU – business without fixed establishment in EU
- Third country – non-EU state or territory
Conclusion
The IOSS opens up a simplified, single point VAT compliance regime across the EU for suppliers selling low value goods from outside the bloc. Making registration, reporting and payment easier should increase compliance rates among sellers of imported goods.
For consumers, the upfront collection of VAT through the IOSS prevents unwanted surprises or delays at customs. However, use of the IOSS is optional and normal import VAT rules continue applying for suppliers who decide not to use it.
Recent changes
- 2026-11-09 — The Council of the EU reached a general approach on the draft Directive that would delete the EUR 150 consignment-value limit from the deemed-supplier rule and the IOSS, so both apply to distance sales of imported goods of any value; Member States would apply it from 1 July 2028. Status proposed: the European Parliament must be re-consulted before formal adoption. (Council of the European Union) — see event · issue
- 2026-09-19 — Regulation (EU) 2026/2108, the new Union Customs Code, was published in the Official Journal. Article 5, point (14) defines the "importer for distance sales" as the person supplying, or the person facilitating, distance sales of imported goods; the Regulation applies from 21 September 2027. (EUR-Lex) — see issue
- 2026-09-12 — Malta's Budget Measures Implementation Act, 2026 (Act III of 2026) transposes the recast Art 14a(2), extending the deemed-supplier rule to facilitated supplies to taxable persons and non-taxable legal persons whose intra-Community acquisitions are not subject to VAT under Art 3(1), in force 1 January 2027. (Malta Tax and Customs Administration) — see issue
- 2026-09-02 — Poland's Council of Ministers backed a draft VAT Act amendment clarifying which supplies count as facilitated by electronic interfaces for deemed-supplier purposes; status remains proposed, planned for 1 January 2027. (Ministerstwo Finansów) — see issue
Frequently asked questions
Does ViDA change which imports qualify as deemed-supplier sales under IOSS?
The EUR 150 consignment ceiling for IOSS imports is unchanged. Deemed-supplier treatment of a non-established seller's intra-EU goods supplies is not new: Article 14a(2) has applied it since 1 July 2021 for sales to non-taxable persons. What ViDA's Article 2 changes from 1 January 2027 is the customer group: the recast Article 14a(2) also covers taxable persons and non-taxable legal persons whose intra-Community acquisitions of goods are not subject to VAT under Article 3(1). Malta has already enacted this (Act III of 2026); Poland's equivalent is still a draft as of September 2026. (Malta Tax and Customs Administration; Ministerstwo Finansów, gov.pl, checked 2026-09-20)
Is the ViDA deemed-supplier extension already in force?
Not yet anywhere — the EU-wide date is 1 January 2027. But "in force" and "enacted" are different questions from "law": Malta's transposing Act (Act III of 2026, Government Gazette No. 21,599) is already gazetted and only awaiting its 1 January 2027 commencement date, while Poland's is a draft the Council of Ministers backed on 2 September 2026 and has not yet passed into law. (Malta Tax and Customs Administration; Ministerstwo Finansów, gov.pl, checked 2026-09-20)
Will the EUR 150 IOSS limit be removed?
Not yet — it has only been proposed. On 9 November 2026 the Council of the EU reached a general approach on a draft Directive (Council doc 15179/26) that deletes the EUR 150 limit from the IOSS and from the deemed-supplier rule for imported goods, so both would cover distance sales of imported goods of any value. Member States would apply the new rules from 1 July 2028, later if the IOSS functionality of the new customs system is not operational by 1 June 2028. The European Parliament must give its opinion again before the Council can formally adopt the Directive, so until then the EUR 150 limit still applies. (Council of the European Union, doc 15179/26, checked 2026-11-11)
Related resources
- ViDA — VAT in the Digital Age — the full Article 2 national-transposition picture, Malta vs Poland
- Guide to the VAT One Stop Shop (OSS) — the companion EUR 10,000 threshold clarification and call-off-stock phase-out