South Dakota v. Wayfair
South Dakota v. Wayfair, Inc., 585 U.S. 162, decided on 21 June 2018 by a 5–4 vote, is the US Supreme Court case that overruled Quill Corp. v. North Dakota (1992) and National Bellas Hess (1967). Since Wayfair, a state may require an out-of-state seller with no physical presence to collect its sales tax once the seller's business in the state passes an economic threshold. This is called economic nexus.
The Court decided the case; it did not set a national threshold. Each state's legislature sets its own test, and the figures have kept moving. South Dakota, the state whose law the Court upheld, has used a USD 100,000-only test since 1 July 2023. At least 13 states have now dropped the "200 transactions" alternative that the 2016 South Dakota law made famous (see current status, as at 2026-11-03).
The official text is in the Court's bound volume: 585 U.S. 162 (docket No. 17-494). Justice Kennedy wrote for the Court, joined by Justices Thomas, Ginsburg, Alito and Gorsuch. Chief Justice Roberts dissented, joined by Justices Breyer, Sotomayor and Kagan. The docket entry for 21 June 2018 reads: "Judgment VACATED and case REMANDED."
Before Wayfair: the physical presence rule
The physical presence rule came from National Bellas Hess, Inc. v. Department of Revenue of Ill., 386 U.S. 753 (1967). Quill Corp. v. North Dakota, 504 U.S. 298 (1992) then kept it under the Commerce Clause. The Wayfair syllabus summarises the history: the Court in Bellas Hess held that a seller whose only connection with customers in the State was by common carrier or mail lacked the contacts that both the Due Process Clause and the Commerce Clause required, and "In Quill, the Court overruled the due process holding, but not the Commerce Clause holding" (585 U.S. 162, Syllabus).
Under those two cases, as the syllabus puts it, "South Dakota may not require a business that has no physical presence in the State to collect its sales tax." The tax was still owed. Sellers collect and remit it, "but if they do not then in-state consumers are responsible for paying a use tax at the same rate". Consumer compliance was low. The Court recorded the estimate that "Bellas Hess and Quill cause South Dakota to lose between $48 and $58 million annually" (same source).
Physical presence meant things a seller has in the state, such as stores, offices, warehouses or employees. The Court's example shows how thin the line was: "a business that maintains a few items of inventory in a small warehouse in a State is required to collect and remit a tax on all of its sales in the State, while a seller with a pervasive Internet presence cannot be subject to the same tax for the sales of the same items" (585 U.S. 162, Syllabus).
How it works
What South Dakota's 2016 Act required
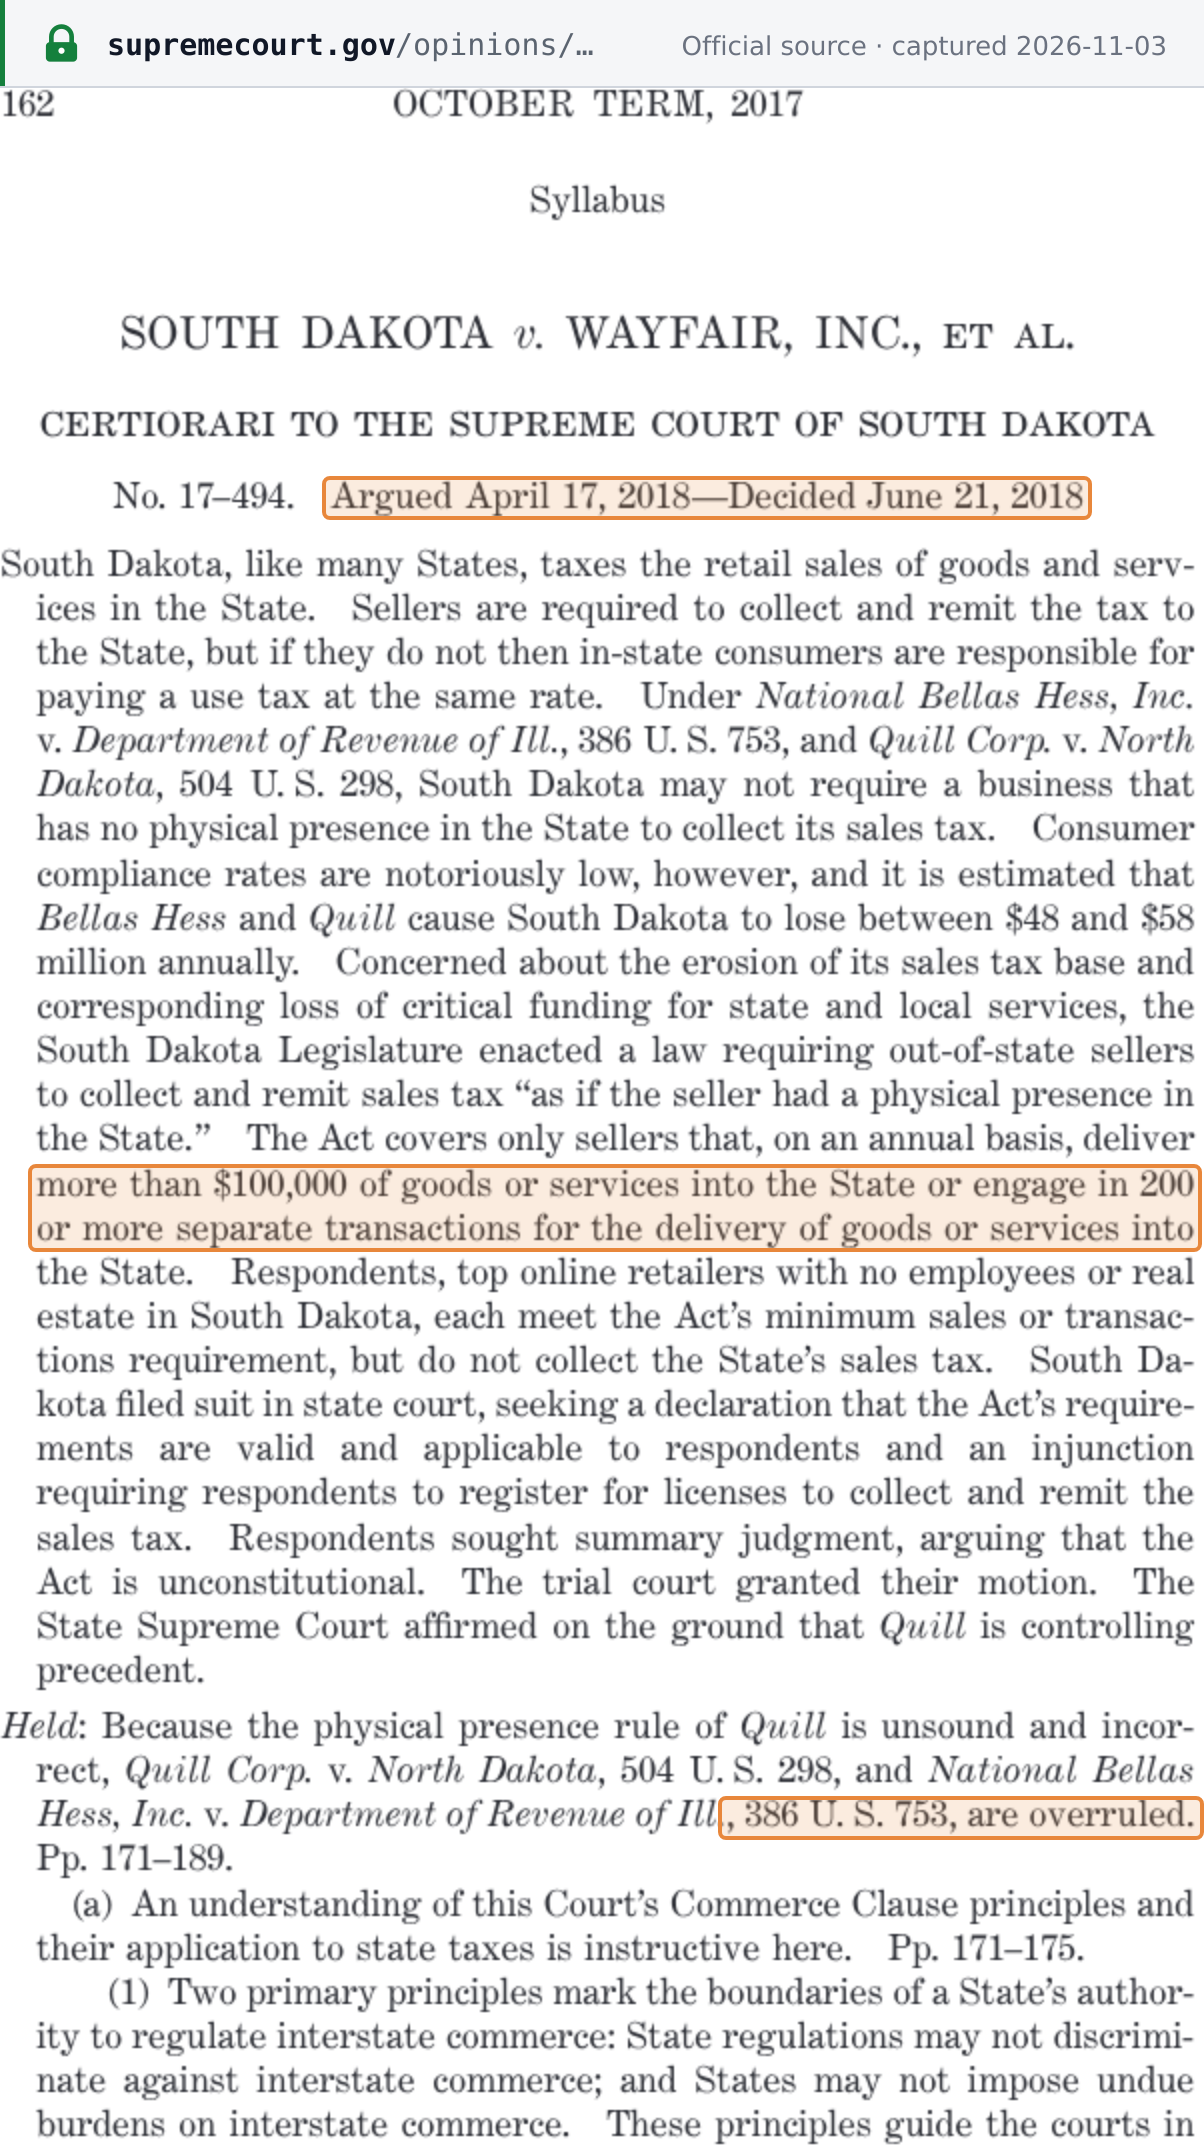
South Dakota passed S.B. 106 in 2016 (SL 2016, ch 70, effective 1 May 2016) to test the rule. The Court described its scope: "The Act applies only to sellers that, on an annual basis, deliver more than $100,000 of goods or services into the State or engage in 200 or more separate transactions for the delivery of goods or services into the State." The Act also "forecloses the retroactive application of this requirement" (585 U.S., at 170).
The case came to the Court because South Dakota sued the sellers, not the other way round. "South Dakota filed suit in state court, seeking a declaration that the Act's requirements are valid and applicable to respondents and an injunction requiring respondents to register for licenses to collect and remit the sales tax." The respondents were "Wayfair, Inc., Overstock.com, Inc., and Newegg, Inc.", "merchants with no employees or real estate in South Dakota". They won summary judgment, and the South Dakota Supreme Court affirmed because Quill was binding precedent.
 Source snapshot captured 2026-11-03 — original
What the Court held
The holding is one sentence: "Because the physical presence rule of Quill is unsound and incorrect, Quill Corp. v. North Dakota, 504 U. S. 298, and National Bellas Hess, Inc. v. Department of Revenue of Ill., 386 U. S. 753, are overruled." (585 U.S. 162, Syllabus)
Two passages carry the reasoning:
- "Physical presence is not necessary to create a substantial nexus." (585 U.S., at 178)
- "Here, the nexus is clearly sufficient based on both the economic and virtual contacts respondents have with the State. … This quantity of business could not have occurred unless the seller availed itself of the substantial privilege of carrying on business in South Dakota." (585 U.S., at 188)
What the Court did not decide
The Court held that this nexus was sufficient. It did not approve USD 100,000 or 200 transactions for every state, and it did not rule on whether South Dakota's law placed an undue burden on interstate commerce. It noted three features of the Act that "appear designed to prevent discrimination against or undue burdens upon interstate commerce":
- "the Act applies a safe harbor to those who transact only limited business in South Dakota";
- "the Act ensures that no obligation to remit the sales tax may be applied retroactively";
- "South Dakota is one of more than 20 States that have adopted the Streamlined Sales and Use Tax Agreement" (see the Streamlined Sales Tax explainer).
It then left the rest open: "Any remaining claims regarding the application of the Commerce Clause in the absence of Quill and Bellas Hess may be addressed in the first instance on remand." (585 U.S., at 188–189) A state's threshold, look-back period and other features can still be challenged under the Commerce Clause.
South Dakota's test today (SDCL 10-64-2)
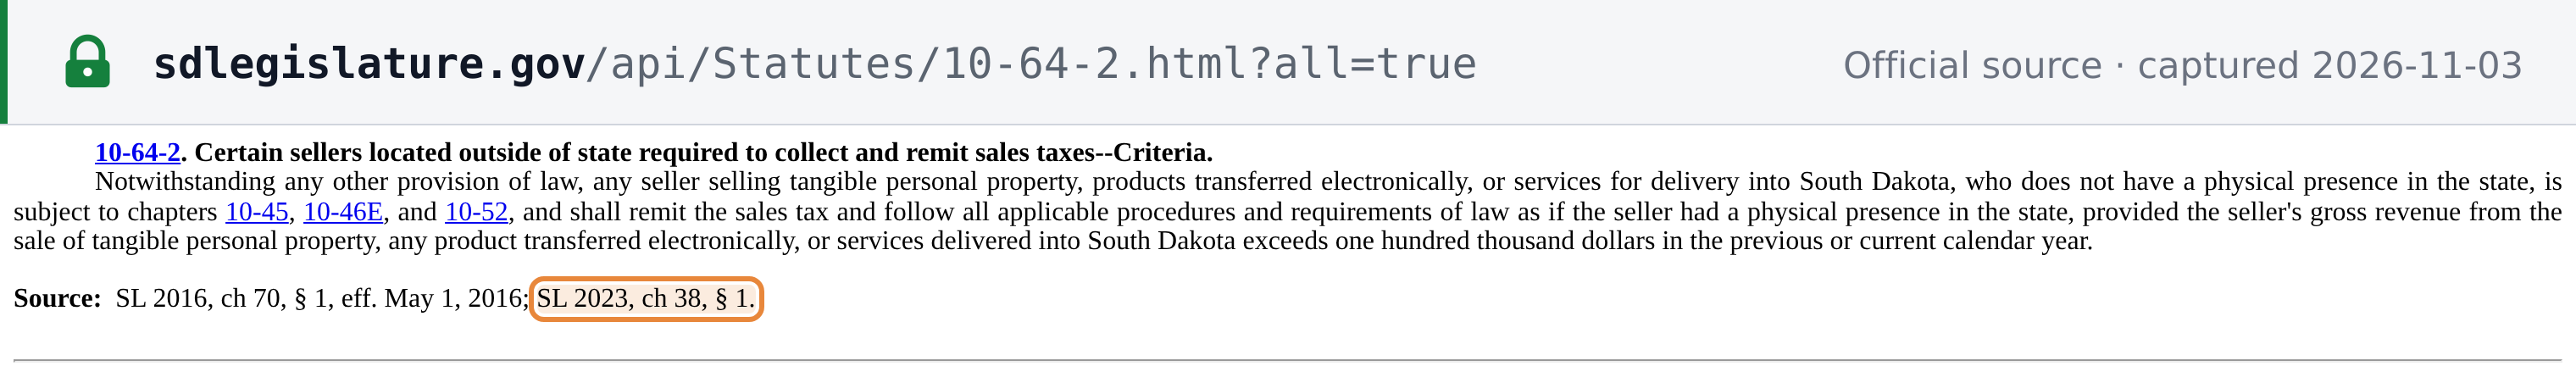
The present-tense South Dakota rule is no longer the 2016 one. SDCL 10-64-2, as amended by SL 2023, ch 38, reads in full:
"Notwithstanding any other provision of law, any seller selling tangible personal property, products transferred electronically, or services for delivery into South Dakota, who does not have a physical presence in the state, is subject to chapters 10-45, 10-46E, and 10-52, and shall remit the sales tax and follow all applicable procedures and requirements of law as if the seller had a physical presence in the state, provided the seller's gross revenue from the sale of tangible personal property, any product transferred electronically, or services delivered into South Dakota exceeds one hundred thousand dollars in the previous or current calendar year."
(SDCL 10-64-2, South Dakota Legislature, text as at 2026-11-03; source note "SL 2016, ch 70, § 1, eff. May 1, 2016; SL 2023, ch 38, § 1.")
 Source snapshot captured 2026-11-03 — original
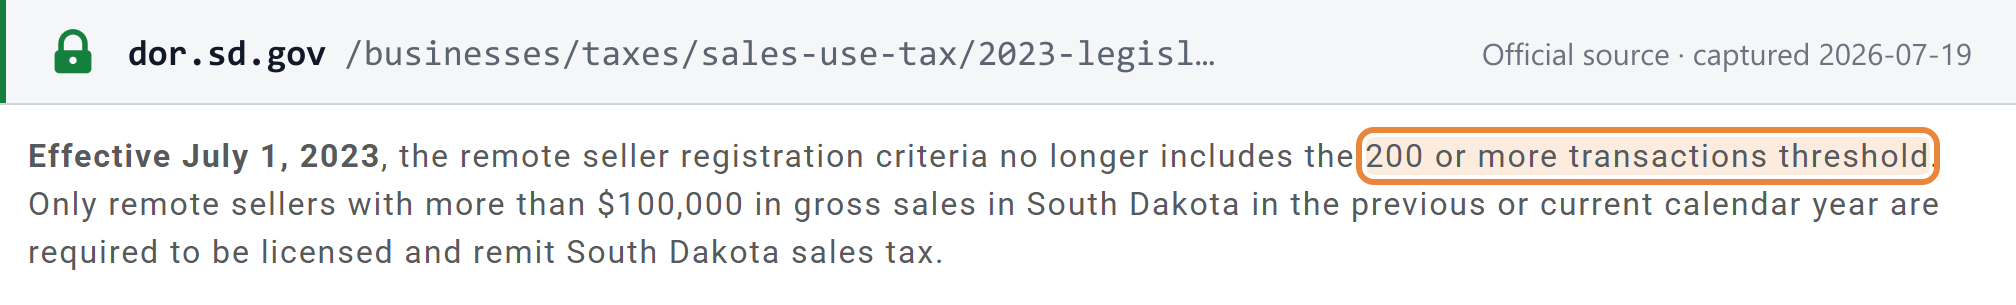
There is no transaction count. The South Dakota Department of Revenue explains the 2023 change (SB 30): "Effective July 1, 2023, the remote seller registration criteria no longer includes the 200 or more transactions threshold. Only remote sellers with more than $100,000 in gross sales in South Dakota in the previous or current calendar year are required to be licensed and remit South Dakota sales tax." From 1 November 2018 to 30 June 2023 the test was gross sales over USD 100,000 or 200 or more separate transactions (SD DOR, 2023 legislative updates).
A 2025 amendment added a start window. SDCL 10-64-2.1 (SL 2025, ch 55): "A seller who meets the criteria of § 10-64-2 is not required to register and remit the tax under the provisions of chapters 10-45, 10-46E, and 10-52, prior to the first day of the first month that begins at least thirty days after meeting the criteria." (SDCL 10-64-2.1)
Worked example
A furniture retailer in Oregon has no property or staff in South Dakota. Its South Dakota sales were USD 80,000 in 2025, in 600 orders.
- Under the 2016 Act it would have been required to collect for 2025: 600 orders is more than 200 separate transactions.
- Under SDCL 10-64-2 today, 2025 alone does not trigger the duty, because USD 80,000 does not exceed USD 100,000.
- In 2026 its South Dakota sales pass USD 100,000 on 10 March. The current calendar year now meets the test. Under SDCL 10-64-2.1 it need not register and remit before the first day of the first month that begins at least thirty days after that date. 1 April is only 22 days later, so the answer is 1 May 2026.
- It stays in scope for all of 2027, because the test looks at the previous or current calendar year.
North Carolina's start date works differently. There, a seller engaged in business only through the threshold starts on the first day of the first calendar month at least 60 days after crossing it (G.S. 105-164.8(b)(9)). That rule "became effective July 2, 2026" and "applies only to retailers that exceed the Sales Thresholds on or after that date" (NCDOR), so it does not cover a March 2026 crossing. Had the same seller crossed North Carolina's threshold on 10 March 2027, the 60th day would be 9 May 2027 and it would start on 1 June 2027; under South Dakota's rule the same crossing gives 1 May 2027. Start-date rules are state law, and they differ.
Who it affects
- Remote sellers. Wayfair matters to a business that sells into a state where it has no store, office, warehouse or staff. Once its sales pass that state's threshold, it must register, collect and file there. In South Dakota the test covers tangible personal property, products transferred electronically and services (SDCL 10-64-2).
- Marketplace providers. States extended the same idea to platforms. South Dakota: "As of March 1, 2019, marketplace providers have been required to license their business and remit applicable sales tax on all sales it facilitates into South Dakota if: The marketplace provider is a remote seller; or The marketplace provider facilitates the sales of at least one marketplace seller that meets the remote seller criteria; or The marketplace provider facilitates the sales of two or more marketplace sellers that, when the sales are combined, meets the remote seller criteria." (SD DOR). See marketplace deemed-supplier rules for how platform liability works in the US and abroad.
- Sellers with a physical presence. For them the threshold changes nothing. "All sellers with a physical presence in South Dakota continue to be required to hold a sales tax license and remit sales tax regardless of the amount of sales or number of transactions." (same source). That is state law. The Court's holding is that physical presence is not necessary.
Most of the states sourced in the jurisdiction table use USD 100,000. The outliers are California, New York and Texas at USD 500,000, and Alabama and Mississippi at USD 250,000. What is measured also differs:
- gross, taxable or retail sales;
- calendar year, a rolling 12 months or four quarters;
- whether related companies count. California counts "the retailer and all persons related to the retailer".
Several states frame the remote seller's duty as use tax collection. California's AB 147 requires out-of-state retailers to "collect California use tax" (CDTFA). Texas remote sellers under the safe-harbor amount need not "collect, report and remit state and local use tax" (Texas Comptroller).
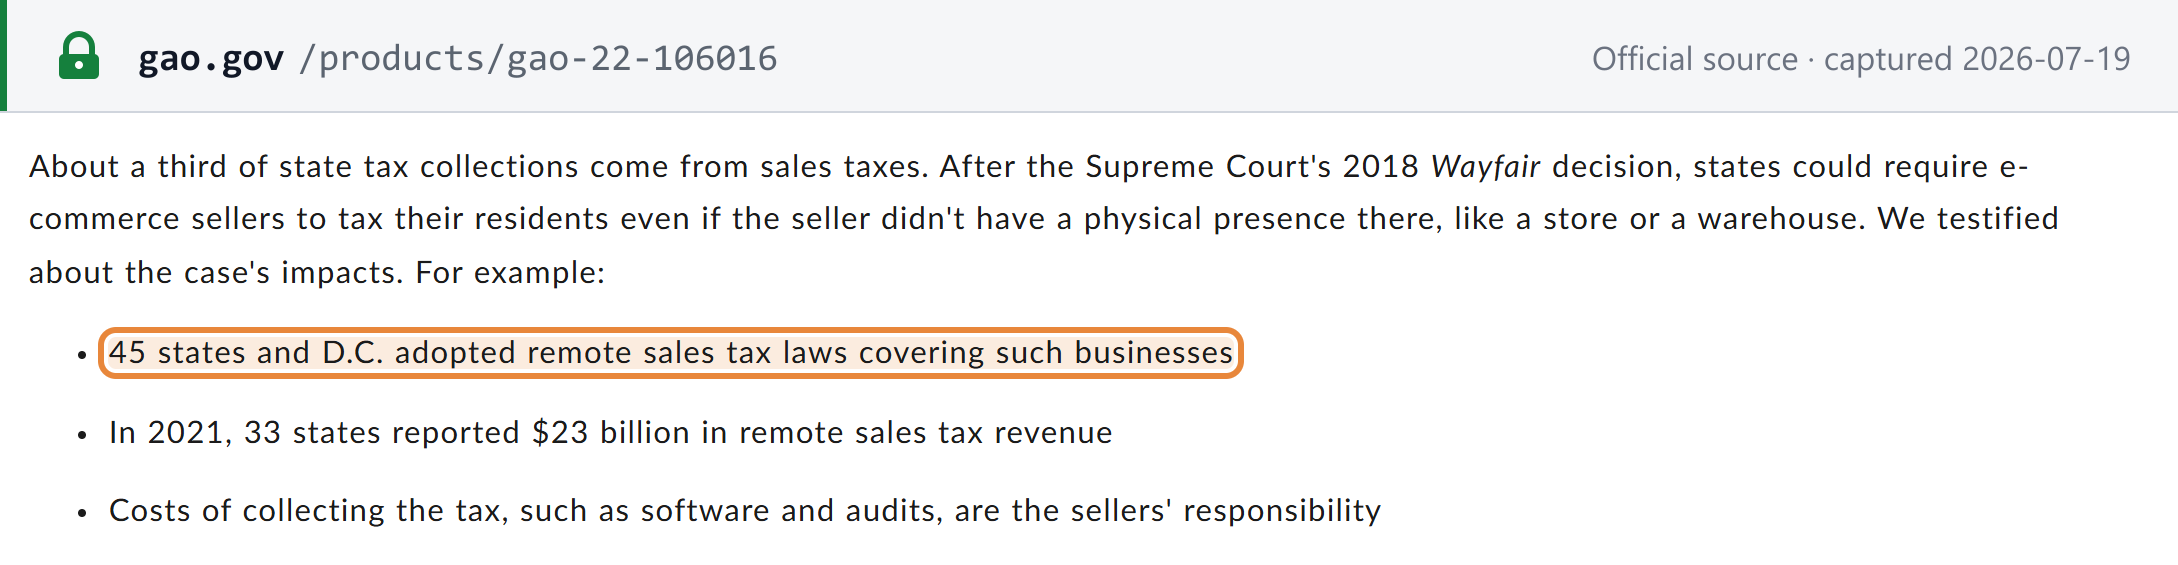
By June 2021, every state with a statewide sales tax, and DC, had a remote-seller law. The US Government Accountability Office reports that "45 states and D.C. adopted remote sales tax laws covering such businesses" and that "As of June 2021, all 45 states with a statewide sales tax and the District of Columbia had adopted requirements" (GAO-22-106016).
 Source snapshot captured 2026-07-19 — original
Current status and dates
As at 2026-11-03. The trend since Wayfair has been to remove the transaction count, not to add one. A count of 200 orders can catch a seller with only a few thousand dollars of sales. The table below lists the states checked for this page whose own revenue department or legislature confirms that the transaction test has been dropped: at least 13 states, plus Alaska's local-government commission. Other states may also have dropped a transaction count. States that never had a transaction test are not on it.
| Effective | Jurisdiction | What changed | Instrument | Source |
|---|---|---|---|---|
| 14 Mar 2019 | Washington | "200 transaction threshold and click-through nexus eliminated" | — | WA DOR |
| 1 Jul 2019 | Iowa | 200-sale threshold removed; USD 100,000 only | HF 779, 2019 Iowa Acts ch. 152 §25 (approved 16 May 2019) | 2019 Iowa Acts ch. 152; Iowa DOR |
| Taxable years beginning after 31 Dec 2018 | North Dakota | 200 taxable-transaction test repealed; USD 100,000 taxable sales only | SB 2191 (2019), signed 14 Mar 2019, §3 | SB 2191 enrolled; bill actions; ND Office of State Tax Commissioner |
| 20 Feb 2021 | Wisconsin | 200-transaction threshold eliminated | 2021 Wis. Act 1 | WI DOR |
| — | Maine | Sub-§1-A of 36 M.R.S. §1754-B repealed; §1-B ¶B replaced with a USD 100,000-only test | PL 2021, c. 181, Pt. B, §§4, 5, 7 | Maine Legislature |
| 1 Jul 2023 | South Dakota | 200-transaction test removed | SB 30 (SL 2023, ch 38) | SD DOR; SDCL 10-64-2 |
| 1 Aug 2023 | Louisiana | 200-transaction test removed | HB 171, Act 15 of 2023 | R.S. 47:301; bill history |
| 1 Jan 2024 (retroactive) | Indiana | 200-transaction threshold removed | SEA 228 (2024), Sec. 4 | Indiana DOR 2024 Legislative Synopsis; Indiana DOR FAQ |
| 1 Jul 2024 | North Carolina | Transaction thresholds repealed | S.L. 2024-28, s. 2.1 | NCDOR Directive SD-24-1 |
| 1 Jul 2024 | Wyoming | Transaction test repealed | HB0197 (HEA 38), 2024 Sess. Laws ch. 67, signed 8 Mar 2024 | Wyoming Legislature |
| 1 Jan 2025 | Alaska (ARSSTC, local) | Transaction thresholds repealed | Alaska Remote Seller Uniform Code, Section 040(A), amendments adopted July 2024 | ARSSTC notice |
| 1 Jul 2025 | Utah | 200-transaction test removed | S.B. 47 (2025) | Utah State Tax Commission; S.B. 47 |
| 1 Jan 2026 | Illinois | "The 200-transaction threshold no longer applies" | P.A. 104-0006 | IDOR Bulletin FY 2026-12 |
| 1 Aug 2026 | Kentucky | 200-transaction test removed; services added to the USD 100,000 test | HB 757, Acts 2026 ch. 161 §§1, 16, 135 | Acts ch. 161; bill record |
 Source snapshot captured 2026-07-19 — original
Alaska has no statewide sales tax. The Alaska Remote Seller Sales Tax Commission (ARSSTC) is the commission of local governments that runs remote-seller collection for its members. Its notice says "the transaction thresholds were repealed. The effective date of the repeal is January 1, 2025."
The two most recent changes:
-
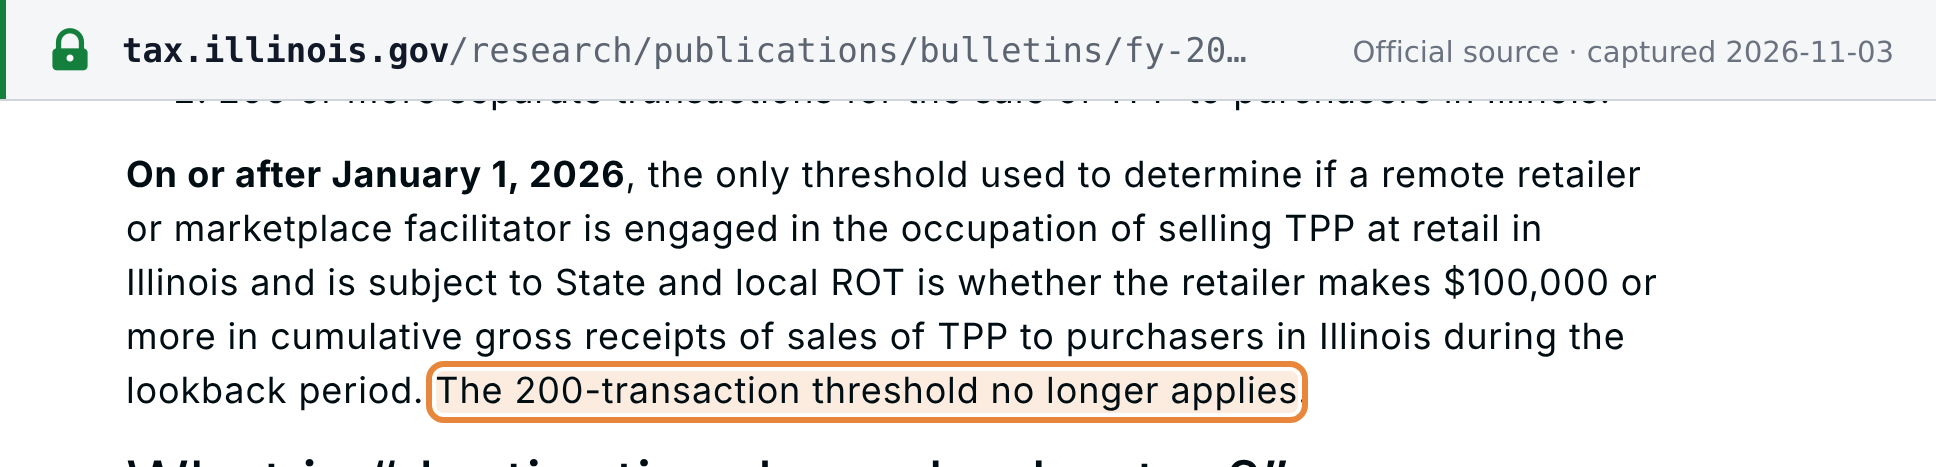
Illinois, 1 January 2026. The Illinois Department of Revenue: "On or after January 1, 2026, the only threshold used to determine if a remote retailer or marketplace facilitator is engaged in the occupation of selling TPP at retail in Illinois and is subject to State and local ROT is whether the retailer makes $100,000 or more in cumulative gross receipts of sales of TPP to purchasers in Illinois during the lookback period. The 200-transaction threshold no longer applies." Illinois measures over a 12-month lookback period, not a calendar year (IDOR Informational Bulletin FY 2026-12).
 Source snapshot captured 2026-11-03 — original
-
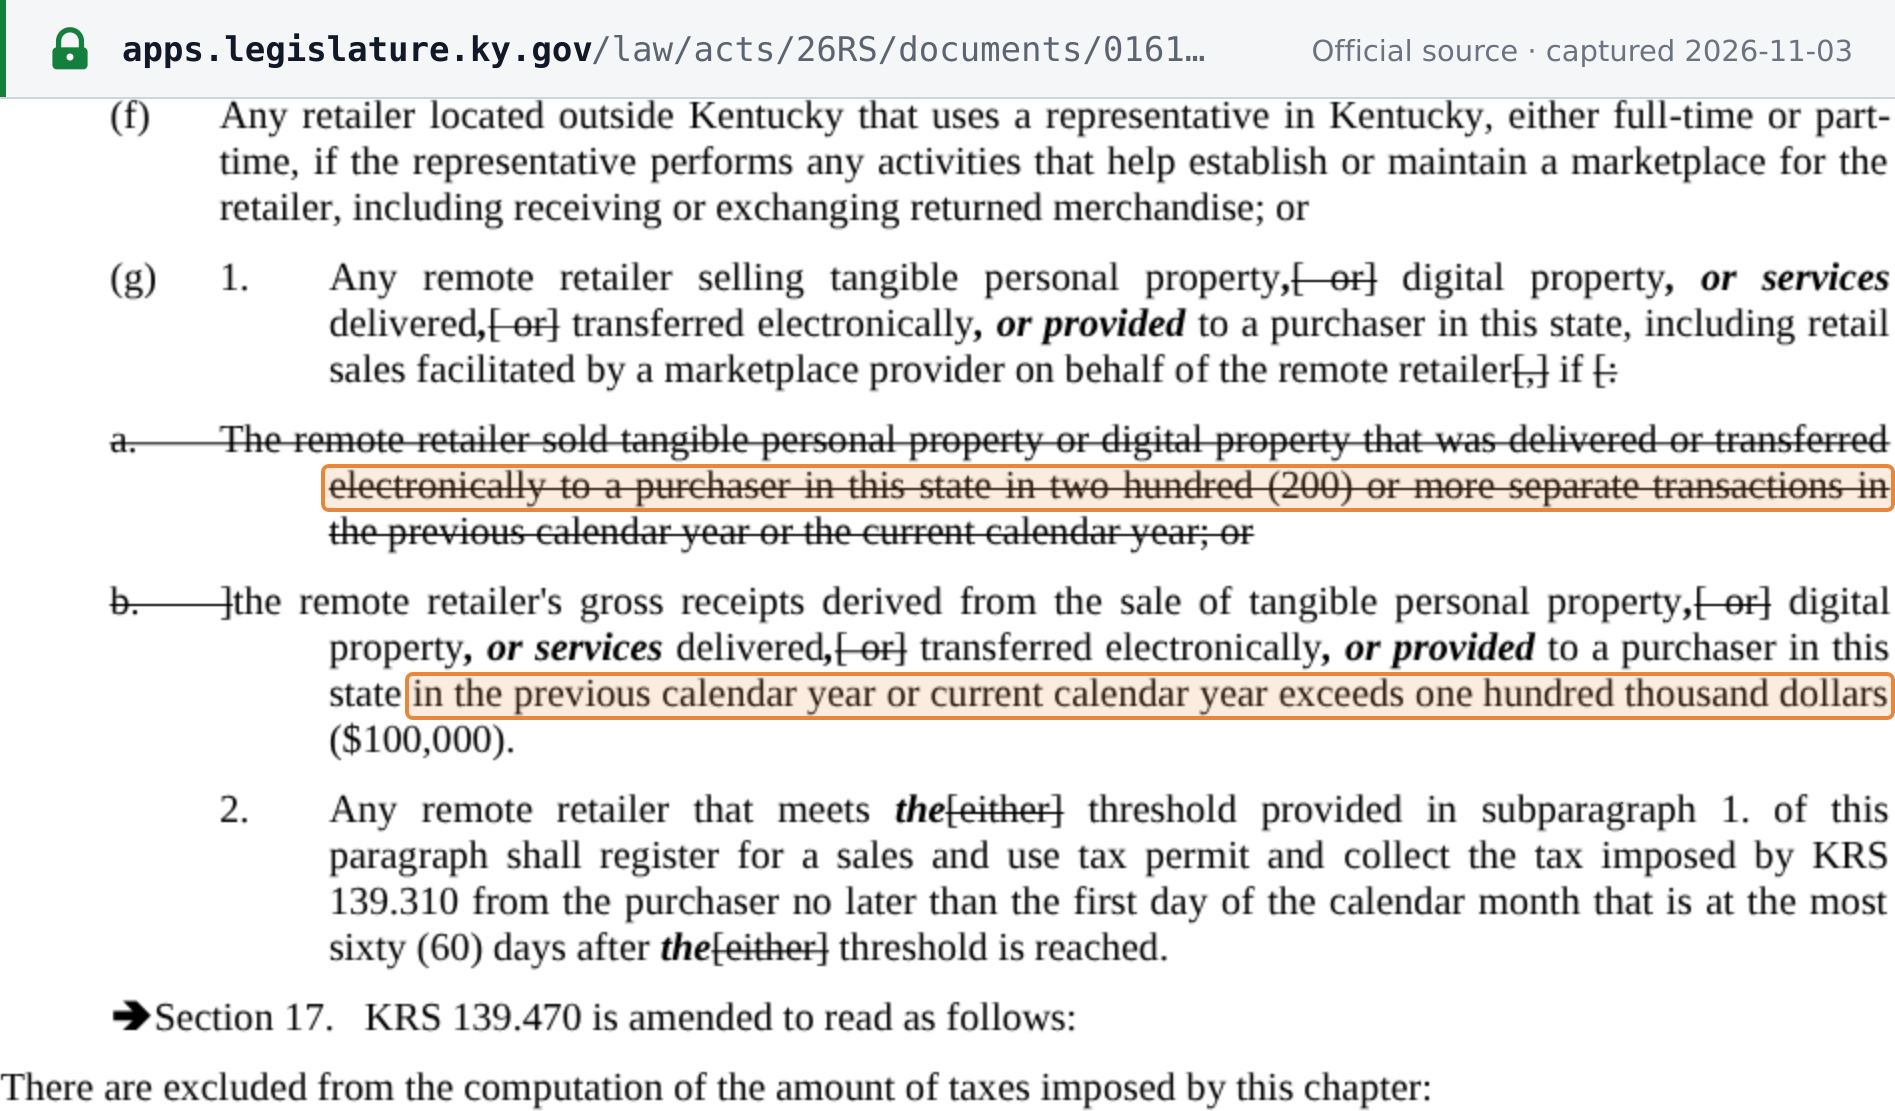
Kentucky, 1 August 2026. House Bill 757 (Acts 2026, ch. 161) drops the 200-transaction alternative for both remote retailers and marketplace providers:
- Remote retailers (KRS 139.340(2)(g)1, amended by §16): gross receipts over USD 100,000 from tangible personal property, digital property or services delivered, transferred electronically or provided to a purchaser in Kentucky in the previous or current calendar year.
- Marketplace providers (KRS 139.450(2)(a), amended by §1): retail sales made or facilitated for one or more marketplace retailers that "in any sales combination exceeds one hundred thousand dollars ($100,000)". The words on the calendar-year period were struck along with the 200-transaction test.
The Act states: "Sections 1, 11 to 17, 45, 95 to 97, and 116 of this Act take effect August 1, 2026." The General Assembly overrode the Governor's line-item vetoes on 14 April 2026 (the Act reads "Vetoed in Part and Overridden April 14, 2026"); the bill record shows "04/14/26: delivered to Secretary of State (Acts Ch. 161)" (Kentucky Acts 2026 ch. 161).
 Source snapshot captured 2026-11-03 — original
Other post-Wayfair adjustments
-
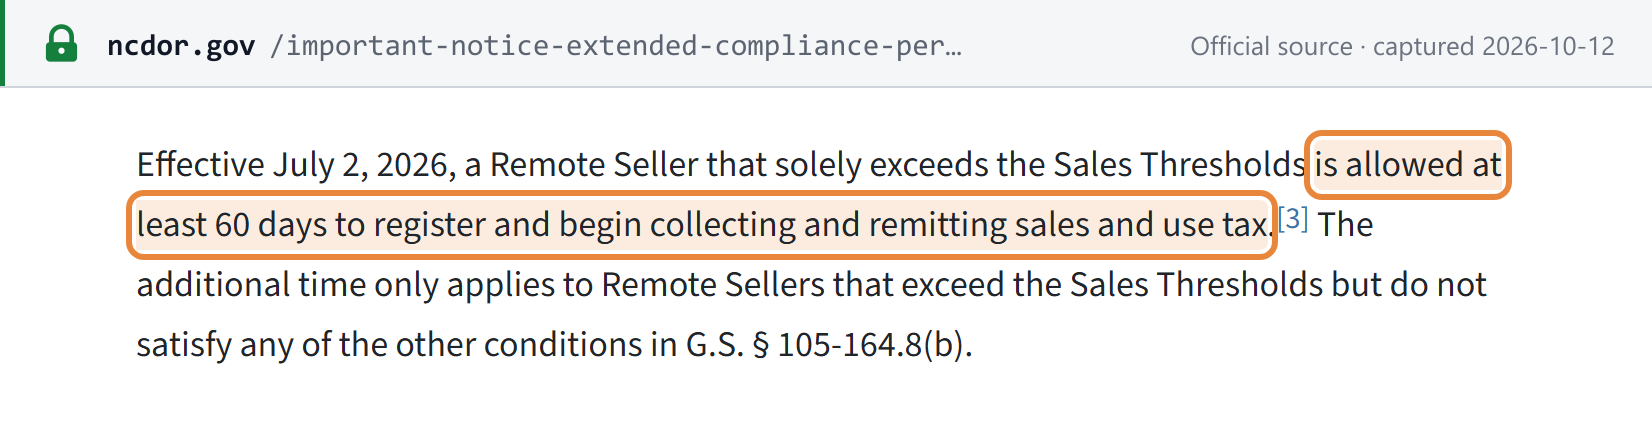
Start windows. Some states now give a newly qualifying seller time before collection starts. South Dakota allows until the first day of the first month that begins at least thirty days after the seller meets the criteria (SDCL 10-64-2.1, SL 2025, ch 55). North Carolina: "Effective July 2, 2026, a Remote Seller that solely exceeds the Sales Thresholds is allowed at least 60 days to register and begin collecting and remitting sales and use tax." (S.L. 2026-31, s. 3.1; NCDOR)
 Source snapshot captured 2026-10-12 — original
-
Use-tax notice and reporting. In Washington, use-tax notice and reporting came before Wayfair, and the state has since dropped it. The Washington Department of Revenue's nexus history lists "Election and use tax notice and reporting" for January to September 2018, before the entry "Wayfair" for October to December 2018, and "Election and use tax notice and reporting eliminated" for July to December 2019 (WA DOR).
Jurisdiction table
This table covers selected states only: 22 states plus Alaska's local-government commission, each read from the state's own revenue department or legislature on the date shown. It is not a list of all 45 sales-tax states and DC; per the GAO, all of them have remote-seller laws (see Who it affects). States not listed here have not been checked for this page. "More than" and "or more" follow each source's wording.
| Jurisdiction | Dollar test | Transaction test | Measurement period | Last confirmed | Source |
|---|---|---|---|---|---|
| Alabama | Retail sales over USD 250,000 | None | Previous calendar year | 2026-11-03 | ADOR Rule 810-6-2-.90.03 |
| Alaska (ARSSTC, local) | USD 100,000 or more ("meets or exceeds") | None (removed 1 Jan 2025) | Current or previous calendar year | 2026-11-03 | ARSSTC notice; ARSSTC |
| Arkansas | Over USD 100,000 | OR 200 taxable transactions | Current or previous year | 2026-11-03 | Arkansas DFA |
| California | Over USD 500,000, including related persons | None | Preceding or current calendar year | 2026-11-03 | CDTFA |
| Connecticut | At least USD 100,000 | AND 200 or more retail sales | 12 months ending 30 September | 2026-11-03 | CT DRS |
| Florida | Taxable remote sales over USD 100,000 | None | Previous calendar year | 2026-11-03 | Florida DOR TIP 21A01-03 |
| Illinois | USD 100,000 or more | None (removed 1 Jan 2026) | 12-month lookback period | 2026-11-03 | IDOR FY 2026-12 |
| Indiana | Over USD 100,000 | None (removed 1 Jan 2024) | Current or preceding calendar year | 2026-11-03 | Indiana DOR |
| Iowa | USD 100,000 or more | None (removed 1 Jul 2019) | Current or prior calendar year | 2026-11-03 | Iowa DOR |
| Kentucky | Remote retailers: over USD 100,000 (tangible personal property, digital property, services); marketplace providers: facilitated sales over USD 100,000 | None (removed 1 Aug 2026) | Remote retailers: previous or current calendar year | 2026-11-03 | Acts 2026 ch. 161, §16 |
| Louisiana | Over USD 100,000 | None (removed 1 Aug 2023) | Previous or current calendar year | 2026-11-03 | R.S. 47:301(4)(k) |
| Maine | Over USD 100,000 | None (repealed by PL 2021, c. 181) | Previous or current calendar year | 2026-11-03 | 36 M.R.S. §1754-B |
| Mississippi | Over USD 250,000 | None | Any twelve-month period | 2026-11-03 | Mississippi DOR |
| New Jersey | Over USD 100,000 | OR 200 or more transactions | Current or prior calendar year | 2026-11-03 | NJ Division of Taxation |
| New York | Over USD 500,000 | AND more than 100 sales | Immediately preceding four sales tax quarters | 2026-11-03 | NYS Tax Department |
| North Carolina | Over USD 100,000 | None (removed 1 Jul 2024) | Previous or current calendar year; 60-day start from 2 Jul 2026 | 2026-11-03 | G.S. 105-164.8 |
| North Dakota | USD 100,000 taxable sales | None (repealed 2019) | Previous or current calendar year | 2026-11-03 | ND Office of State Tax Commissioner |
| South Dakota | Over USD 100,000 gross revenue | None (removed 1 Jul 2023) | Previous or current calendar year; 30-day start (SDCL 10-64-2.1) | 2026-11-03 | SDCL 10-64-2 |
| Texas | USD 500,000 total Texas revenue (no permit needed below it) | None | Preceding twelve calendar months | 2026-11-03 | Texas Comptroller |
| Utah | Over USD 100,000 | None (removed 1 Jul 2025) | Previous or current calendar year | 2026-11-03 | Utah State Tax Commission |
| Washington | Over USD 100,000 combined gross receipts | None (removed 14 Mar 2019) | Current or prior year | 2026-11-03 | WA DOR |
| Wisconsin | Gross sales over USD 100,000 | None (removed 20 Feb 2021) | Previous or current calendar year | 2026-11-03 | WI DOR |
| Wyoming | Gross revenue over USD 100,000 | None (removed 1 Jul 2024) | Current or immediately preceding calendar year | 2026-11-03 | HB0197 (2024) |
Notes:
- Washington counts all gross receipts sourced or attributed to the state, not only retail sales. North Dakota and Florida count taxable sales. Texas counts taxable and nontaxable sales.
- Louisiana's remote-seller commission FAQ (remotesellers.louisiana.gov, read 2026-11-03) still mentions 200 transactions. The statute, R.S. 47:301(4)(k)(i) as amended by Acts 2023, No. 15, does not, and the statute governs.
- Wyoming's 2026 act SF0079 (effective 1 July 2026) changes only the introductory wording of W.S. 39-15-501(a). The USD 100,000 test is unchanged (SF0079).
Related changes from the feed
- 2026-08-01 — Kentucky: remote retailers and marketplace providers move to a USD 100,000-only economic nexus test, removing the 200-transaction alternative (House Bill 757, Acts Chapter 161; the General Assembly overrode the Governor's line-item vetoes on 14 April 2026). (Kentucky Legislature) — see event
- 2026-08-01 — Illinois: Remote Retailer Tax Amnesty for Retailers' Occupation Tax periods 1 January 2021 to 30 June 2026; applications ran 1 August to 31 October 2026 and the window has closed. (Illinois DOR) — see event
- 2026-07-02 — North Carolina: a remote seller engaged in business only because it exceeds the USD 100,000 sales threshold has at least 60 days to register and begin collecting (Session Law 2026-31, s. 3.1). (North Carolina Department of Revenue) — see event
- 2026-01-01 — Illinois: the 200-transaction threshold for remote retailers and marketplace facilitators no longer applies; the test is USD 100,000 or more in cumulative gross receipts in the lookback period (P.A. 104-0006). (Illinois Department of Revenue)
For every US change, see the United States tax-change chronology.
Frequently asked questions
Does South Dakota still use the 200-transaction test from the Wayfair case?
No. South Dakota removed the 200 or more transactions test effective 1 July 2023 (SB 30, SL 2023, ch 38). Under SDCL 10-64-2 a seller with no physical presence must remit South Dakota sales tax if its gross revenue from sales of tangible personal property, products transferred electronically or services delivered into South Dakota exceeds USD 100,000 in the previous or current calendar year. The 200-transaction test was part of the 2016 Act that the Supreme Court reviewed in 2018.
Source: SDCL 10-64-2; SD DOR.
Did Wayfair set a national USD 100,000 or 200-transaction threshold?
No. The Court held that South Dakota's nexus was clearly sufficient and overruled the physical presence rule of Quill and Bellas Hess. It did not set a threshold for other states, and it left any remaining Commerce Clause claims to be addressed on remand. Each state sets its own test. Among the states in the table on this page the dollar tests run from USD 100,000 to USD 500,000 (California, New York and Texas).
Source: 585 U.S. 162.
Which states still count transactions?
Of the 22 states in the table on this page (as at 3 November 2026), four still count transactions. Arkansas and New Jersey use more than USD 100,000 or 200 transactions, either one being enough. Connecticut requires both 200 or more retail sales and at least USD 100,000 in the 12 months ending 30 September. New York requires both more than USD 500,000 and more than 100 sales in the preceding four sales tax quarters. At least 13 states have dropped a transaction test, most recently Illinois (1 January 2026) and Kentucky (1 August 2026).
Source: state sources in the jurisdiction table.
Is the USD 100,000 threshold "more than" or "at least" USD 100,000?
It depends on the state. South Dakota, Utah and Indiana use more than (exceeds) USD 100,000. Illinois and Iowa use USD 100,000 or more, and Connecticut uses at least USD 100,000. A seller with exactly USD 100,000 of sales is in scope in Illinois, Iowa and Connecticut but not in South Dakota.
Source: SDCL 10-64-2; Utah; Indiana DOR; IDOR; Iowa DOR; CT DRS.
I crossed a state's threshold mid-year. When do I have to start collecting?
It depends on the state. In South Dakota a seller need not register and remit before the first day of the first month that begins at least thirty days after meeting the criteria (SDCL 10-64-2.1). In North Carolina, from 2 July 2026, a remote seller engaged in business only through the USD 100,000 threshold starts on the first day of the first calendar month at least 60 days after its sales exceed the threshold. Because most tests look at the previous or current calendar year, a seller that crosses the threshold stays in scope for the following year as well.
Source: SDCL 10-64-2.1; NCDOR.
I have a warehouse or employees in a state but low sales there. Does the threshold protect me?
No. Economic nexus thresholds apply to sellers without a physical presence. The South Dakota Department of Revenue states that all sellers with a physical presence in South Dakota must hold a sales tax license and remit sales tax regardless of the amount of sales or number of transactions.
Source: SD DOR.
Related resources
- Streamlined Sales Tax (SST) — the Agreement the Court cited as one of South Dakota's safeguards
- Marketplace deemed-supplier rules — when the platform, not the seller, collects the tax
- United States sales tax guide — state rates, registration and recent changes
- US tax ID (EIN) guide — the federal EIN, which is not a state sales tax registration
- VAT and GST registration thresholds — the global threshold table
- VAT on digital services by non-resident suppliers — the non-US counterpart: foreign sellers registering where their customers are
- United States tax-change chronology
Reference links
- South Dakota v. Wayfair, Inc., 585 U.S. 162 (2018) — Supreme Court of the United States, United States Reports
- Docket No. 17-494 — Supreme Court of the United States
- SDCL 10-64-2 and SDCL 10-64-2.1 — South Dakota Legislature
- 2023 legislative updates (SB 30) — South Dakota Department of Revenue
- GAO-22-106016 — US Government Accountability Office