DAC7 — EU reporting by digital platform operators
DAC7 is the EU rule, set by Council Directive (EU) 2021/514, that makes digital platform operators collect and verify identity and income data on the sellers who use them — for property rentals, personal services, sales of goods and transport rental — and report it every year by 31 January to one EU tax authority, which shares it with the sellers' member states. It creates no new tax. It has applied since 1 January 2023; the first exchange between tax authorities, for calendar year 2023, took place at the end of February 2024 (European Commission, checked 2026-09-24). As at 2026-09-24, three reporting cycles (2023, 2024 and 2025 data) are complete, and the next report — for 2026 — is due by 31 January 2027.
 Source snapshot captured 2026-09-24 — original
What DAC7 is — and what it is not
- Official name. Council Directive (EU) 2021/514 of 22 March 2021 amending Directive 2011/16/EU on administrative cooperation in the field of taxation, OJ L 104, 25.3.2021, p. 1 (EUR-Lex, checked 2026-09-24). The Council adopted it under Articles 113 and 115 TFEU — the special legislative procedure, which requires unanimity.
- Who owns it. The EU Council adopts amendments; the European Commission (DG TAXUD) runs the exchange framework; each member state's tax authority receives the reports and sets penalties.
- "DAC" is a family. Directive 2011/16/EU (the Directive on Administrative Cooperation) has been amended in numbered steps. The Commission lists them as: DAC1 income and assets, DAC2 financial accounts (the EU version of the OECD Common Reporting Standard), DAC3 tax rulings, DAC4 country-by-country reports, DAC6 cross-border arrangements, DAC7 "income generated by online platform sellers", DAC8 crypto-assets and DAC9 Pillar Two returns (Commission DAC page, checked 2026-09-24). DAC7 also added royalties to the income categories exchanged under DAC1, and its provisions on joint audits between member states apply from 1 January 2024.
- Not a tax. In the Commission's words, "DAC7 does not impose any new tax or in any way regulate the taxation of income earned by sellers on digital platforms." Sellers remain taxable under their own national income-tax and VAT rules.
- Not a VAT liability rule. DAC7 is information reporting. The separate ViDA rules that make some accommodation and transport platforms liable for VAT as deemed suppliers are explained in ViDA.
- International counterpart. DAC7 is the EU implementation of the OECD Model Rules for Reporting by Platform Operators with respect to Sellers in the Sharing and Gig Economy (MRDP), published 3 July 2020 for accommodation, transport and personal services. An optional module of 22 June 2021 extends them to sales of goods and rental of means of transport — scope DAC7 includes by default. The OECD's DPI XML Schema (29 March 2022) serves both the OECD exchange agreement (DPI MCAA) and DAC7 (OECD, checked 2026-09-24).
How it works
What counts as a platform
A Platform is "any software, including a website or a part thereof and applications, including mobile applications, accessible by users and allowing Sellers to be connected to other users for the purpose of carrying out a Relevant Activity, directly or indirectly, to such users" (Annex V, Section I, A(1)). Software that, without any further intervention in the activity, exclusively processes payments, lets users list or advertise an activity, or redirects users to a platform is not a Platform.
The four Relevant Activities, each carried out for Consideration (Annex V, Section I, A(8)):
- rental of immovable property — residential, commercial, any other immovable property, and parking spaces;
- a Personal Service;
- the sale of Goods;
- the rental of any mode of transport.
Activity by a seller acting as an employee of the platform operator (or a related entity) is out of scope.
The annual cycle
- Due diligence during the year. The operator collects each seller's data and checks it for reliability — including TINs and VAT numbers, through any free electronic interface a member state or the EU provides. It must finish by 31 December of the reportable period. For sellers already on the platform on 1 January 2023 (or when the operator first came into scope), the deadline was 31 December of the operator's second reportable period (Annex V, Section II C(1), F).
- Report by 31 January. The operator reports to its member state's competent authority "no later than 31 January of the year following the calendar year in which the Seller is identified as a Reportable Seller" (Annex V, Section III A). Reporting is annual; the amounts inside the report are broken down by quarter.
- Seller copy by the same date. The operator gives each reportable seller the information reported about them, also by 31 January.
- Exchange by end-February. The receiving member state passes the data to the seller's member state of residence — and, for property rentals, always to the member state where the property is — within two months of the end of the reportable period (Article 8ac(3)).
 Source snapshot captured 2026-09-24 — original
Where an operator reports
- EU operators report where they have their nexus (tax residence, or — if not resident in any member state — incorporation, place of management or a permanent establishment). An operator with nexus in several member states elects one and notifies the others.
- Non-EU operators register with any one member state when they start operating as a platform operator. That state allocates an individual identification number and notifies all the others; the Commission keeps a central register (Article 8ac(4), (6)). The Commission describes this as registering in "one Member State serving as a one-stop shop for DAC7 purposes".
- Where several operators run the same platform, one operator's report relieves the others if they hold proof that it was filed.
What is reported
For every reportable seller (Article 8ac(2); Annex V, Section II):
| Individual sellers | Entity sellers |
|---|---|
| First and last name; primary address | Legal name; primary address |
| Every TIN and its member state of issuance — or, with no TIN, place of birth | Every TIN and its member state of issuance |
| VAT identification number, where available | VAT identification number, where available |
| Date of birth | Business registration number; any permanent establishment in the EU |
For both kinds of seller, the report also carries:
- the Financial Account Identifier (where available, and unless the seller's member state of residence has said it will not use it) and the account holder's name if different;
- each member state where the seller is resident;
- the total Consideration paid or credited in each quarter and the number of Relevant Activities it relates to;
- the fees, commissions or taxes withheld or charged by the platform in each quarter.
Consideration is reported net, not gross. The directive defines it as compensation "net of any fees, commissions or taxes withheld or charged by the Reporting Platform Operator" (Annex V, Section I, A(10)). Property rentals add the address of each Property Listing, its land-registration number where issued, the quarterly Consideration per listing, and — where available — the number of days rented and the type of property.
DAC7 has always let operators rely on an identification service provided by a member state or the EU to confirm a seller's identity and tax residence. Since 1 January 2026, DAC8 defines this Identification Service — "an electronic process made available free of charge by a Member State or the Union" for that purpose — and, where the operator's competent authority uses one, the operator reports the seller's name, the service identifier and the issuing member state instead of the identity items (Directive (EU) 2023/2226, Annex II, checked 2026-09-24).
Format. The exchange format has been fixed since the start: Commission Implementing Regulation (EU) 2022/1467 of 5 September 2022 sets the computerised format (built on the OECD DPI schema), the central-register form and the individual identification number, and has applied since 1 January 2023 (EUR-Lex, checked 2026-09-24). Implementing Regulation (EU) 2025/648 of 2 April 2025 left the reporting format unchanged: it requires member states to send the Commission their annual DAC7 exchange statistics before 1 April each year and adds joint-audit statistics (EUR-Lex). Member states publish their own filing channels — Spain's is Modelo 238, for example.
When a seller will not cooperate
If a seller still has not supplied the required information after the initial request and two reminders, and not before 60 days have passed, the operator must either:
- close the seller's account and prevent re-registration, or
- withhold the seller's Consideration until the information is provided
(Annex V, Section IV A(2)).
When a non-EU operator does not report
If a non-EU operator fails to report after two reminders from its member state of registration, that state revokes its registration — no earlier than 30 days and no later than 90 days after the second reminder. Member states then endeavour to coordinate further action, which as a last resort can include stopping the operator from operating in the Union (Annex V, Section IV F(6)–(7)).
Worked example — which sellers get reported
The goods de minimis needs both conditions: fewer than 30 sales and total Consideration of no more than EUR 2,000 in the year.
| Seller on a marketplace (calendar year) | Activity | Consideration (net of fees) | Reported? |
|---|---|---|---|
| Individual selling second-hand clothes | 12 sales | EUR 1,500 | No — both conditions met |
| Individual selling a few pieces of furniture | 25 sales | EUR 2,400 | Yes — over EUR 2,000 |
| Individual selling cheap accessories | 40 sales | EUR 900 | Yes — 30 or more sales |
| Company letting a hotel-type Property Listing | 2,300 rentals of one listing | any | No — an entity with more than 2,000 rentals of one listing |
| Individual letting a parking space by the hour | 2,300 rentals of one listing | any | Yes — the 2,000-rental exclusion applies to entities only |
For each reported seller, the Consideration line is what the platform paid or credited to the seller after its own fees: a sale where the buyer pays EUR 100 and the platform keeps a EUR 12 commission is reported as EUR 88 of Consideration, with the EUR 12 reported separately as a fee.
Who it affects
Reporting platform operators
- EU operators — tax resident in a member state, or (if resident nowhere in the EU) incorporated in, managed from, or with a permanent establishment in a member state (Annex V, Section I, A(4)(a)).
- Non-EU operators — none of those links, but they facilitate Relevant Activities by Reportable Sellers, or the rental of immovable property located in a member state (A(4)(b)).
- Out of scope:
- Excluded Platform Operators — operators that show the competent authority in advance, each year, that the platform's entire business model has no Reportable Sellers;
- Qualified Non-Union Platform Operators — non-EU operators whose home jurisdiction exchanges equivalent information with the EU (see equivalence below). They are relieved of DAC7 reporting; they are not an extra category that must report.
Reportable sellers
A Reportable Seller is any active seller, other than an Excluded Seller, "that is resident in a Member State or that rented out immovable property located in a Member State" (Annex V, Section I, B(3)). Two consequences practitioners miss:
- A non-EU host letting property in the EU is in scope. Location of the property is enough.
- Domestic activity counts. The Commission: "the reporting obligation covers both cross-border and non-cross-border activities." A French platform reporting a French seller's French sales is squarely within DAC7.
Excluded sellers
Four kinds of seller are excluded (Annex V, Section I, B(4)):
- a Governmental Entity;
- an Entity whose stock is regularly traded on an established securities market, or a related Entity of one;
- an Entity for which the platform facilitated more than 2,000 rentals of immovable property for one Property Listing in the period — a hotel-type exclusion that does not apply to individuals;
- a seller of goods for which the platform facilitated fewer than 30 sales AND total Consideration that did not exceed EUR 2,000 in the period. Both conditions must hold: 29 sales totalling EUR 2,500 are reportable, and so are 30 sales totalling EUR 300.
 Source snapshot captured 2026-09-24 — original
National wording can differ at the boundary. Germany's PStTG (§ 4) excludes a seller with "weniger als 2 000 Euro" — less than EUR 2,000 — so a seller with exactly EUR 2,000 is excluded under the directive's text but not under the German one (gesetze-im-internet.de, checked 2026-09-24). The Belastingdienst's own pages differ: its seller page states the directive rule ("30 keer of meer verkopen of voor meer dan € 2000" — 30 or more sales, or more than EUR 2,000), while its guidance for platform operators excludes sellers who receive "minder dan € 2.000" (less than EUR 2,000) — the German wording (both checked 2026-09-24).
Current status and dates
In force and running (as at 2026-09-24). Directive (EU) 2021/514 entered into force on the twentieth day after its publication of 25 March 2021 — i.e. 14 April 2021 — and member states had to apply it from 1 January 2023 (Articles 2–3). The calendar below is derived from the directive's 31 January reporting date and two-month exchange window.
| Date | What | Status |
|---|---|---|
| 22 Mar 2021 | Council adopts Directive (EU) 2021/514 | Adopted |
| 31 Dec 2022 | Member states' deadline to adopt and publish national law | Passed |
| 1 Jan 2023 | DAC7 applies; first reportable period starts; IR (EU) 2022/1467 format applies | In force |
| 1 Jan 2024 | Joint-audit provisions apply | In force |
| 31 Jan 2024 | First operator reports (2023 data); exchange at end-February 2024 | Done |
| 31 Dec 2024 | Due diligence deadline for sellers already on a platform on 1 Jan 2023 | Passed |
| 31 Jan 2025 | Second reports (2024 data) | Done |
| 1 Jan 2026 | DAC8 applies, including its Identification Service reporting rule for DAC7 | In force |
| 31 Jan 2026 | Third reports (2025 data) | Done |
| 31 Dec 2026 | Due diligence complete for the 2026 period | Upcoming |
| 31 Jan 2027 | Next reports and seller copies (2026 data); exchange by end-February 2027 | Upcoming |
Late transposers set their own transitional dates. Poland's law entered into force on 1 July 2024 but reaches back to 1 January 2023: operators had until 31 December 2024 to complete due diligence and until 31 January 2025 to file the first Polish reports, covering 2023 and 2024 (Dz.U. 2024 poz. 879, Art. 9 and Art. 22, checked 2026-09-24).
Equivalence: UK, New Zealand and Canada
Article 8ac(7) lets the Commission find a non-EU jurisdiction's platform reporting equivalent, which relieves that jurisdiction's operators as Qualified Non-Union Platform Operators. Determinations have been adopted for the United Kingdom (Implementing Regulation (EU) 2023/2389, first for the Finland–UK agreement), New Zealand (2023/2693) and Canada (2024/432). Relief applies only once the member state concerned has activated the exchange under Section 7 of the OECD DPI MCAA. As at 2026-09-24, the Commission's table shows, for example, Ireland, Poland, Spain and Sweden activated with first exchanges in 2025, while Germany, France and Italy had not activated (European Commission, checked 2026-09-24).
Since DAC7: DAC8 and DAC9 (adopted)
- DAC8 — Council Directive (EU) 2023/2226 of 17 October 2023 — adds reporting by crypto-asset service providers, based on the OECD Crypto-Asset Reporting Framework. Member states had to transpose it by 31 December 2025 and apply it from 1 January 2026; exchanges for the first reporting year (2026) take place by 30 September 2027 (European Commission, checked 2026-09-24). It is a separate regime with different reporting entities, but it also amended DAC7 (the Identification Service reporting rule above) and re-worded the penalty article to cover Articles 8aa to 8ad.
- DAC9 — Council Directive (EU) 2025/872 of 14 April 2025 — covers the exchange of the Pillar Two top-up tax information return, applying from 1 January 2026 (EUR-Lex, checked 2026-09-24). It does not touch platforms.
Commission evaluation (19 November 2025)
The Commission's second DAC evaluation, covering 2018–2023, was published on 19 November 2025. It found the directive "robust, flexible and well-functioning", and called for consolidation and simplification, more consistent application across member states, and "a more robust penalty framework in all Member States" (European Commission, checked 2026-09-24).
 Source snapshot captured 2026-09-24 — original
Proposed, not yet law: the DAC recast of 24 June 2026
On 24 June 2026 the Commission proposed a Council directive recasting the whole DAC — COM(2026) 308 final. It is a proposal: it needs unanimous agreement in the Council (after consulting the European Parliament) and, as at 2026-09-24, has not been adopted. Until it is, the 30-sale / EUR 2,000 rule above remains the law. For platforms, the proposal would:
-
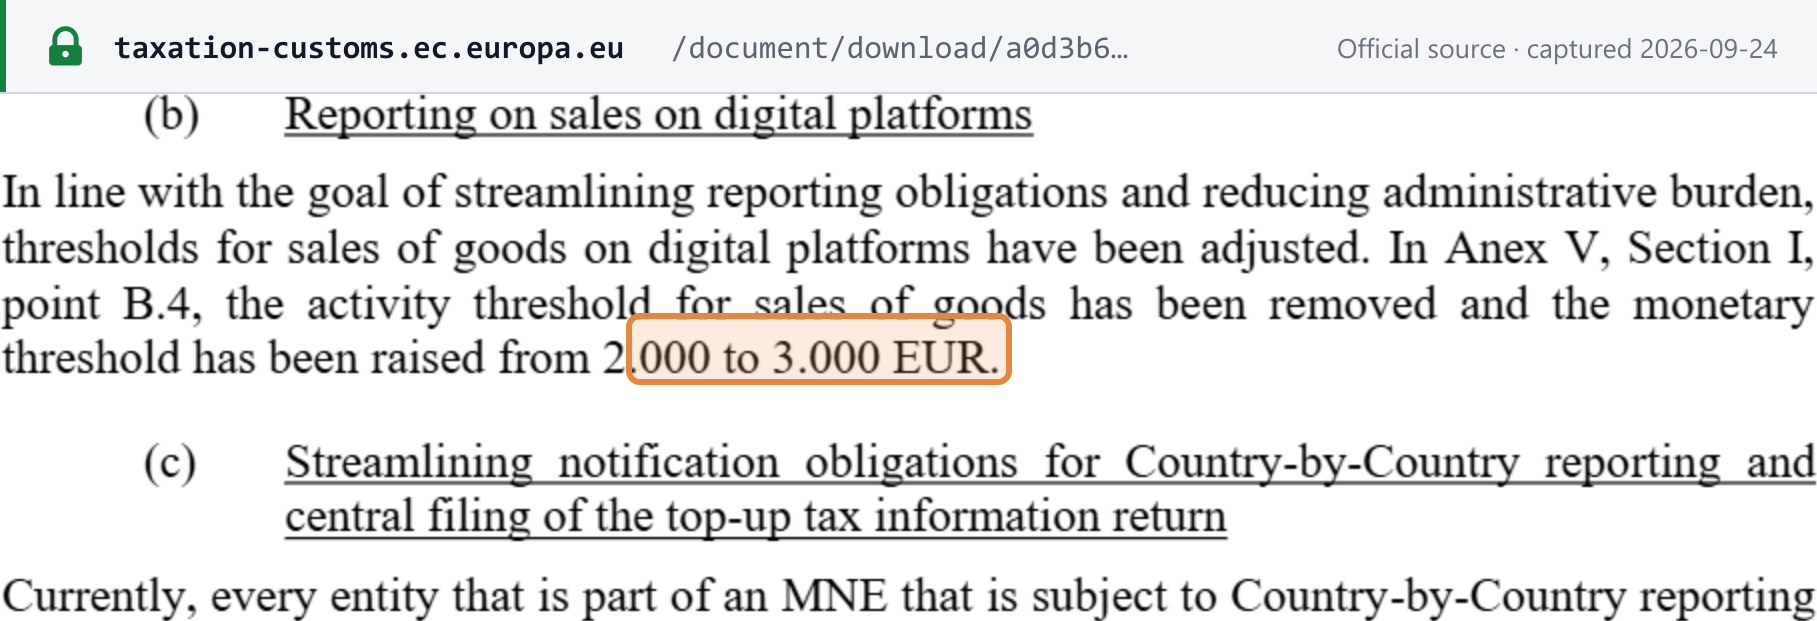
remove the 30-sale test for sales of goods and raise the monetary threshold from EUR 2,000 to EUR 3,000 — the Explanatory Memorandum: "the activity threshold for sales of goods has been removed and the monetary threshold has been raised from 2.000 to 3.000 EUR";
 Source snapshot captured 2026-09-24 — original
-
add a carve-out for smaller platform operators, lighter rules where the seller is itself a reporting platform operator, and an exemption for transactions between related entities, aligned with parallel OECD work;
-
clarify sanctions against non-compliant non-EU platforms.
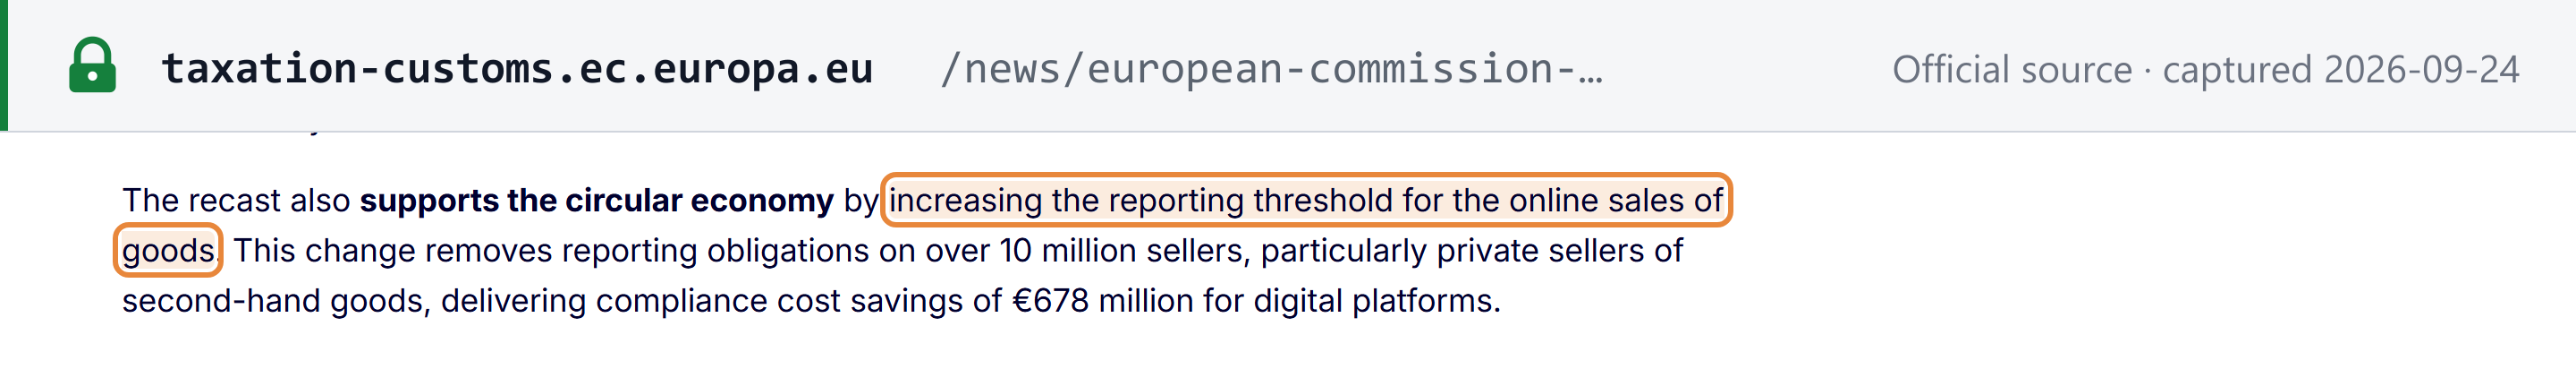
The Commission says the higher goods threshold "removes reporting obligations on over 10 million sellers, particularly private sellers of second-hand goods" (European Commission, 24 June 2026, checked 2026-09-24). The draft's application dates are still placeholders in square brackets — the definitions changes, which include the threshold, are pencilled in for "[1 January 2028]" — and can change before adoption (Explanatory Memorandum, COM(2026) 308, checked 2026-09-24).
 Source snapshot captured 2026-09-24 — original
 Source snapshot captured 2026-09-24 — original
The OECD track (consultation, no adopted change)
The OECD consulted from 15 June to 14 August 2026 on targeted amendments to its Model Rules: lighter thresholds for sellers of low-value goods, clearer definitions of "Platform" and "Platform Operator", less transactional reporting where the seller is itself a reporting platform operator, and a related-entity exclusion. Comments were published on 4 September 2026; no amendment has been adopted as at 2026-09-24 (OECD, checked 2026-09-24).
Penalties by member state
The directive sets no EU amount. Article 25a requires member states to lay down penalties that are "effective, proportionate and dissuasive" (EUR-Lex). Each row below cites the national source for that row.
| Country | National law | Filed with / deadline | Headline penalty (maximum) | Last confirmed | Source |
|---|---|---|---|---|---|
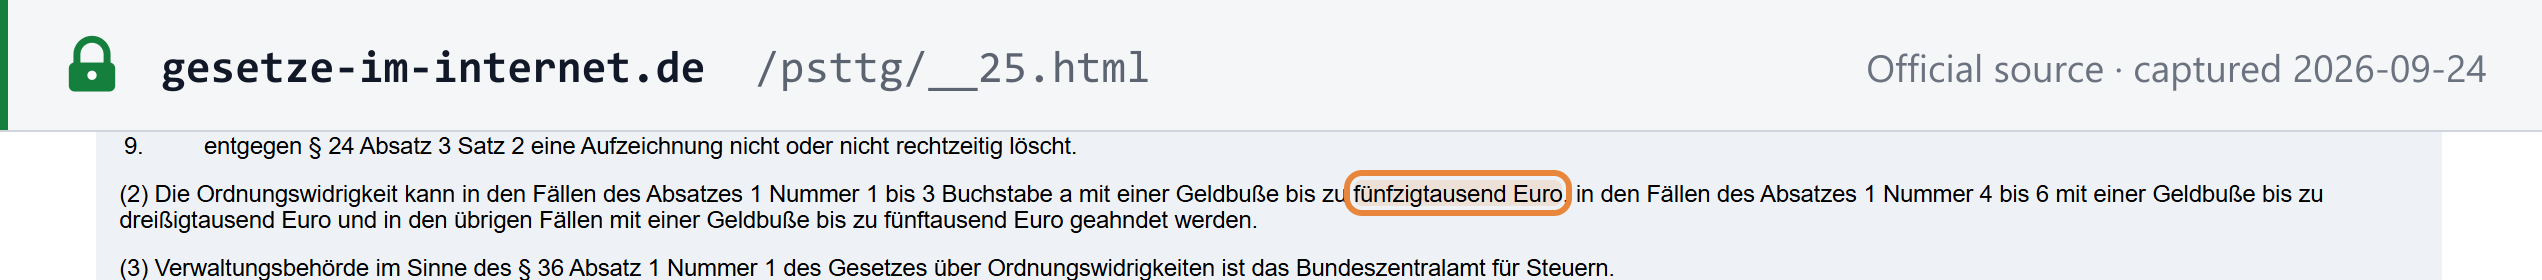
| Germany | Plattformen-Steuertransparenzgesetz (PStTG) of 20 Dec 2022, BGBl. I S. 2730 | Bundeszentralamt für Steuern (BZSt), 31 January | Up to EUR 50,000 (registration failures and incorrect registration notices); up to EUR 30,000 (reporting and correction failures, or failing to block or withhold payouts for a non-cooperating seller under § 23); up to EUR 5,000 (other cases, including seller copies and record-keeping) — § 25(2) | 2026-09-24 | gesetze-im-internet.de § 25, § 13 |
| France | CGI art. 1649 ter A to 1649 ter E | Annual return to the DGFiP | Up to EUR 50,000 (CGI art. 1736 XI), scaled by repeat offence over the year and the three before: no return — EUR 10,000 / 25,000 / 50,000; due-diligence or seller-information failures — EUR 10,000 / 20,000 / 50,000; a first late filing made spontaneously is not penalised. A non-EU operator's registration number can be withdrawn instead (CGI art. 1740 E) | 2026-09-24 | BOFiP BOI-INT-AEA-30-50-20231213 |
| Italy | D.Lgs. 1 marzo 2023, n. 32 | Agenzia delle Entrate, 31 January | EUR 10,000 for breaching the registration obligation (art. 12(4)); omitted reporting draws the penalty of art. 10(1) D.Lgs. 471/1997 (EUR 1,500–15,000 for violations from 1 September 2024) increased by half, i.e. EUR 2,250–22,500; incomplete or inaccurate reporting draws that penalty reduced by half, i.e. EUR 750–7,500 (art. 12(3)). From 1 January 2027, D.Lgs. 471/1997 is repealed and replaced by the testo unico on tax penalties (D.Lgs. 173/2024) | 2026-09-24 | Normattiva art. 12; D.Lgs. 471/1997 art. 10; Agenzia delle Entrate |
| Spain | Ley 13/2023 (adds disposición adicional 25ª to Ley 58/2003 General Tributaria) | AEAT, Modelo 238 | EUR 200 per seller for platform due-diligence failures; EUR 300 fixed fine for a seller who fails to give the platform correct information; where a non-EU operator registers nowhere in the EU and Spain therefore does not receive the data, three times the ordinary information-failure fine | 2026-09-24 | BOE, consolidated Ley 58/2003 |
| Poland | Ustawa z 23 maja 2024 r. (Dz.U. 2024 poz. 879), in force 1 July 2024 | Szef KAS; first reports by 31 January 2025 | Up to PLN 1,000,000, imposed by decision of the Szef KAS | 2026-09-24 | Dz.U. 2024 poz. 879 |
| Netherlands | National DAC7 rules (Belastingdienst) | Belastingdienst, 31 January | Not stated¹ | 2026-09-24 | Belastingdienst (threshold and deadlines only) |
 Source snapshot captured 2026-09-24 — original
¹ The Belastingdienst pages cited state no penalty amount; they carry the threshold and deadlines only.
Italy — change from 1 January 2027. Normattiva shows D.Lgs. 5 agosto 2026, n. 141 (the testo unico on tax compliance and assessment) repealing art. 12, commi 1, 2 and 5, of D.Lgs. 32/2023 with effect from 1 January 2027 — the clauses on seller contracts, five-year record retention and implementing measures. The penalty clauses, commi 3 and 4, are not repealed (Normattiva, checked 2026-09-24). Check the testo unico (D.Lgs. 141/2026) for any replacement provisions.
Other member states publish their own DAC7 guidance; the Commission's DAC7 page links most of them.
Getting ready for the 2026 report
- Scope check — do you facilitate any of the four Relevant Activities for Consideration, and do you have an EU nexus, EU-resident sellers or EU property listings?
- Registration — a non-EU operator registers in one member state before it starts operating; an EU operator with nexus in several states elects one.
- Seller data — collect the identity items in the table above, validate TINs and VAT numbers (for example through the national VAT-number databases), and finish due diligence by 31 December 2026.
- Figures — record Consideration net of your fees, per quarter, with activity counts and fees withheld; per listing for property rentals.
- Non-responsive sellers — initial request, two reminders, at least 60 days, then close the account or withhold payouts.
- Seller notice — tell each individual seller, before reporting, that their data will be collected and exchanged under DAC7 (Directive 2011/16/EU, Art. 25(4) as amended by DAC7).
- File by 31 January 2027 and send each seller their copy by the same date.
Related changes from the feed
EU-level changes are listed in the EU tax-change chronology.
Frequently asked questions
A seller made 25 sales totalling EUR 2,400 on our marketplace. Do we report them?
Yes. A goods seller is excluded only if the platform facilitated fewer than 30 sales AND total Consideration did not exceed EUR 2,000 in the year; EUR 2,400 is over the limit. (Directive (EU) 2021/514, Annex V, Section I, B(4)(d).) The June 2026 recast proposal would drop the 30-sale test and raise the limit to EUR 3,000, but it is only a proposal and has not been adopted.
When is our next DAC7 report due?
By 31 January 2027, for calendar year 2026. Each reportable seller must receive their copy by the same date, and due diligence for 2026 must be complete by 31 December 2026. (Annex V, Sections II and III.)
We are a platform based outside the EU with EU sellers. Where do we file?
Register with one member state of your choice when you start operating; it gives you an individual identification number, and you report there once a year by 31 January. Operators in the UK, Canada and New Zealand can be relieved as Qualified Non-Union Platform Operators for the activities the equivalence decision covers, and only where the member state concerned has activated the exchange with that jurisdiction. (Article 8ac(4) and (7); European Commission, checked 2026-09-24.)
What if a seller will not give us their TIN?
Send the initial request and two reminders, and wait at least 60 days. Then either close the seller's account and prevent re-registration, or withhold payment of the Consideration until the seller provides the information. (Annex V, Section IV A(2).)
Do we report gross sales?
No. You report the Consideration paid or credited to the seller net of your fees, commissions and taxes, for each quarter, with the number of Relevant Activities; the fees, commissions and taxes you withheld or charged are reported separately. (Article 8ac(2); Annex V, Section I, A(10).)
Does DAC8 change anything for marketplaces?
DAC8 is a separate crypto-asset reporting regime that applies from 1 January 2026, with the first exchanges by 30 September 2027. It also amended DAC7: from 1 January 2026 a platform reporting to an authority that uses one can report a free Identification Service identifier instead of the seller's identity details. (Directive (EU) 2023/2226.)
Related resources
- ViDA — VAT in the Digital Age — platform deemed-supplier VAT rules, a liability regime distinct from DAC7 reporting
- One Stop Shop (OSS) and Import One Stop Shop (IOSS) — marketplace VAT schemes that sit alongside DAC7
- VIES and Intrastat and check a VAT number — validating the VAT numbers DAC7 due diligence collects
- Tax identification numbers sellers report: Germany, France, Italy, Poland, Netherlands
- Country guides for the penalty table: Germany, Italy, Spain, Poland
- EU tax-change chronology — every tracked EU-level change
Reference links
- Council Directive (EU) 2021/514 (DAC7) — EUR-Lex
- Commission Implementing Regulation (EU) 2022/1467 — exchange format and register
- Council Directive (EU) 2023/2226 (DAC8)
- European Commission — DAC7 — status, equivalence table, national guidance links
- European Commission — Directive on Administrative Cooperation — the DAC family, evaluation and recast proposal
- OECD — Model Reporting Rules for Digital Platforms