SAF-T — Standard Audit File for Tax
SAF-T (Standard Audit File for Tax) is an OECD standard, defined as an XML schema, for exporting a business's accounting data — general ledger, customers, suppliers, invoices, payments, fixed assets and inventory — in a structured format that tax auditors can test with software. Each country decides whether businesses file it on a schedule, hand it over only when an auditor asks, or only need software that can export it.
The standard belongs to the OECD Forum on Tax Administration. The OECD Committee on Fiscal
Affairs published the first version in May 2005. The current guidance note, version 2.0 of April
2010, extended it to Inventory and Fixed Assets, and its schema is published as version 2.00
(namespace urn:OECD:StandardAuditFile-Taxation/2.00). In the note's own words, "SAF-T advances efficient and effective
audits by internal and external auditors and by revenue bodies."
(OECD guidance note v2.0,
p. 3 and para 10; Appendix B, schema v2.00,
p. 1; checked 2026-09-24)
Periodic filing or a file on request: the distinction that matters
The OECD standard defines what goes in the file. It does not say when a business has to produce it. The guidance note leaves that to each revenue body and its software developers: "They should also establish a common understanding of how and when SAF-T should be produced" (para 33), and "It is entirely a matter for revenue bodies to develop their policies for implementation of SAF-T, including its representation in XML" (para 27). (OECD guidance note v2.0, pp. 10–11, checked 2026-09-24)
So "we have to do SAF-T" means one of three different things, depending on the country:
| Model | What the business must do | Confirmed examples (as at 2026-09-24) |
|---|---|---|
| Periodic submission | File the SAF-T (or SAF-T-based) file on a fixed schedule, whether or not it is being audited | Romania D406; Poland JPK_V7M/K and JPK_CIT; Portugal invoice-data communication; Lithuania i.SAF (invoice level) |
| On request | Be able to export the file at any time, and hand it over when the tax authority asks, typically during an audit | Norway; Lithuania i.SAF-T; Luxembourg FAIA; Austria (optional format); Poland JPK on demand; Portugal (export capability) |
| Export capability only | Use bookkeeping software that can generate, export and import the authorities' standard file | Denmark (digital standard bookkeeping systems — cloud and hybrid systems offered to businesses generally) |
Several countries run more than one model side by side. Poland, Portugal and Lithuania each appear in more than one row of the jurisdiction tables below.
How it works
What the file contains
The guidance note designs SAF-T "to capture data from a number of areas found in a typical business accounting system" (para 24):
- General Ledger: journals
- Accounts Receivable: customer master files, invoices, payments
- Accounts Payable: supplier master files, invoices, payments
- Fixed Assets: asset master files, depreciation and revaluation
- Inventory: product master files, movements
In schema v2.00 the root AuditFile element has four children: Header, MasterFiles,
GeneralLedgerEntries and SourceDocuments. MasterFiles holds, among others, the account,
customer, supplier, tax, product, stock, owner and asset tables; SourceDocuments holds sales invoices, purchase invoices,
payments, movements of goods and asset transactions.
(Appendix B, schema v2.00,
checked 2026-09-24)
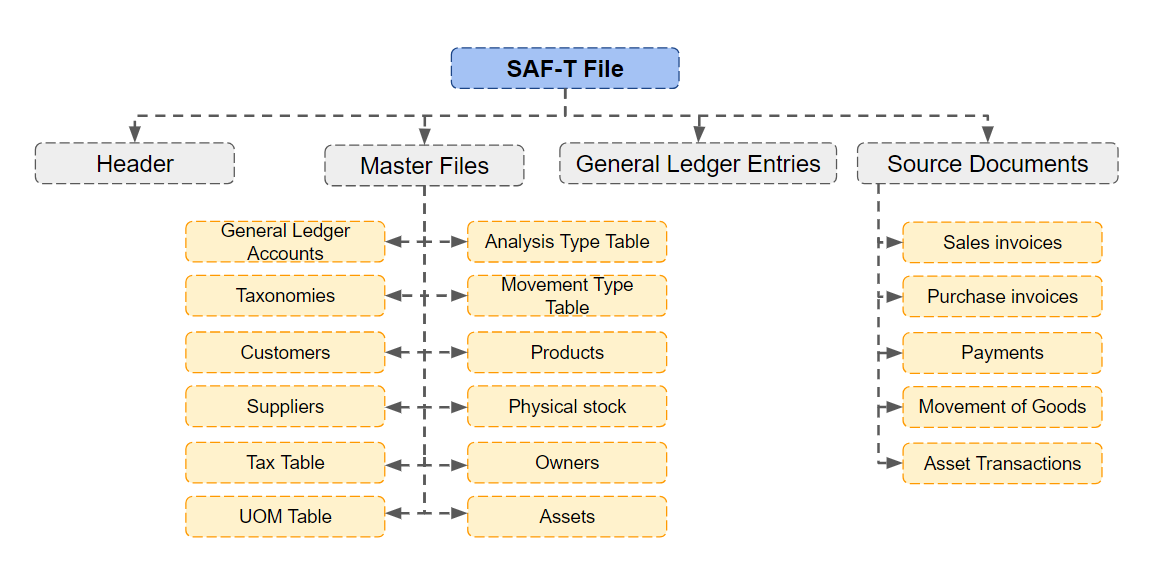 The top-level structure of the OECD SAF-T schema v2.00.
Payroll is not in SAF-T. The design "does not encompass taxes such as payroll", apart from summarised information from such subsystems. Payroll data belongs to a separate companion standard, the Standard Audit File – Payroll (SAF-P). (para 37; para 12)
Format
The OECD schema is XML. The note does not prescribe a format for every country. Format policy is "entirely a matter for revenue bodies", which "should be aware of the on-going development of XBRL, which may offer a more holistic approach to audit" (para 27). Revenue bodies should also choose formats that permit audit automation today while keeping down the cost of a later move to open standards such as XBRL-GL (para 28).
National versions must stay compatible with the OECD model
Countries build their own SAF-T versions (SAF-T (PT), Romania's D406, Norway's SAF-T Financial, Luxembourg's FAIA, Austria's SAF-T AT). The note sets the limits in para 41 and Annex A:
- "The OECD specification is considered to be the minimum necessary to extract meaningful information from a business accounting system therefore any implementation of the SAF-T should be compatible with this specification."
- Revenue bodies may add their own elements only at the schema's extension points; adding them anywhere else breaks compatibility with the OECD model (Annex A). Para 41 warns that removing elements breaks compatibility; Annex A narrows this to elements the OECD marks as mandatory. In the note's words: "Any deviations from the OECD Schema will place a corresponding burden on international software developers."
- Each element is designated mandatory or optional. A mandatory element missing from a software package must still appear in the file with a valid value (para 40), and a national version that omits an element the OECD model marks as mandatory is incompatible with the OECD specification (Annex A).
Who the standard is designed for
The note intends SAF-T to suit businesses of every size, from multinational enterprises to small and medium enterprises (para 13). For large multinationals with complex data, a bespoke or customised file may be the best approach; for SMEs, the SAF-T structure is expected to cover all the data their systems hold (para 14).
What auditors do with it
SAF-T lets auditors run computer-assisted audit techniques on transaction data "down to line level", identify and quantify errors early, and target resources at errors with a material impact (paras 19–20). Auditors can also run all or part of an audit remotely, away from the business's premises (para 19). Businesses can use the same file for self-audit before filing a return (para 21). Two limits: the tax liability may need more information than the file contains (para 22), and SAF-T "will not remove the requirement for businesses to keep and archive records" (para 15). Auditors may still ask for original records.
Benefits, as the OECD lists them
Para 23 lists: lower compliance costs for businesses that would otherwise produce data in custom formats, and for multinationals facing many jurisdictions; data exchange between business systems and between businesses, accountants and government bodies; more efficient self-audit and external audit; better archival data; easier discussions between revenue bodies and businesses; less duplicated effort for software developers building multi-jurisdiction files; and lower administrative costs for tax administrations. (OECD guidance note v2.0, pp. 7–12, checked 2026-09-24)
The OECD recommendations: five for revenue bodies, four for software developers
Revenue bodies are encouraged to (para 43):
- Incorporate SAF-T into their audit and verification methodologies.
- Keep abreast of the development of XBRL and take it into account in their strategy.
- Work with software developers on how to implement the SAF-T schema.
- Work with software developers on how and when a SAF-T file should be produced.
- "Ensure that implementation of the SAF-T in their jurisdiction is compatible with the OECD specification."
Software developers are encouraged to (para 44):
- Incorporate the SAF-T specification into their business and accounting software.
- Work with revenue bodies on how to implement the schema.
- Work with revenue bodies on how and when a SAF-T file should be produced.
- "Provide an easy export facility of the SAF-T to enable testing and analysis."
(OECD guidance note v2.0, pp. 5–6 and 12–13, checked 2026-09-24)
Who it affects
Scope is national. Where a country publishes thresholds or exclusions, they are these (as at 2026-09-24):
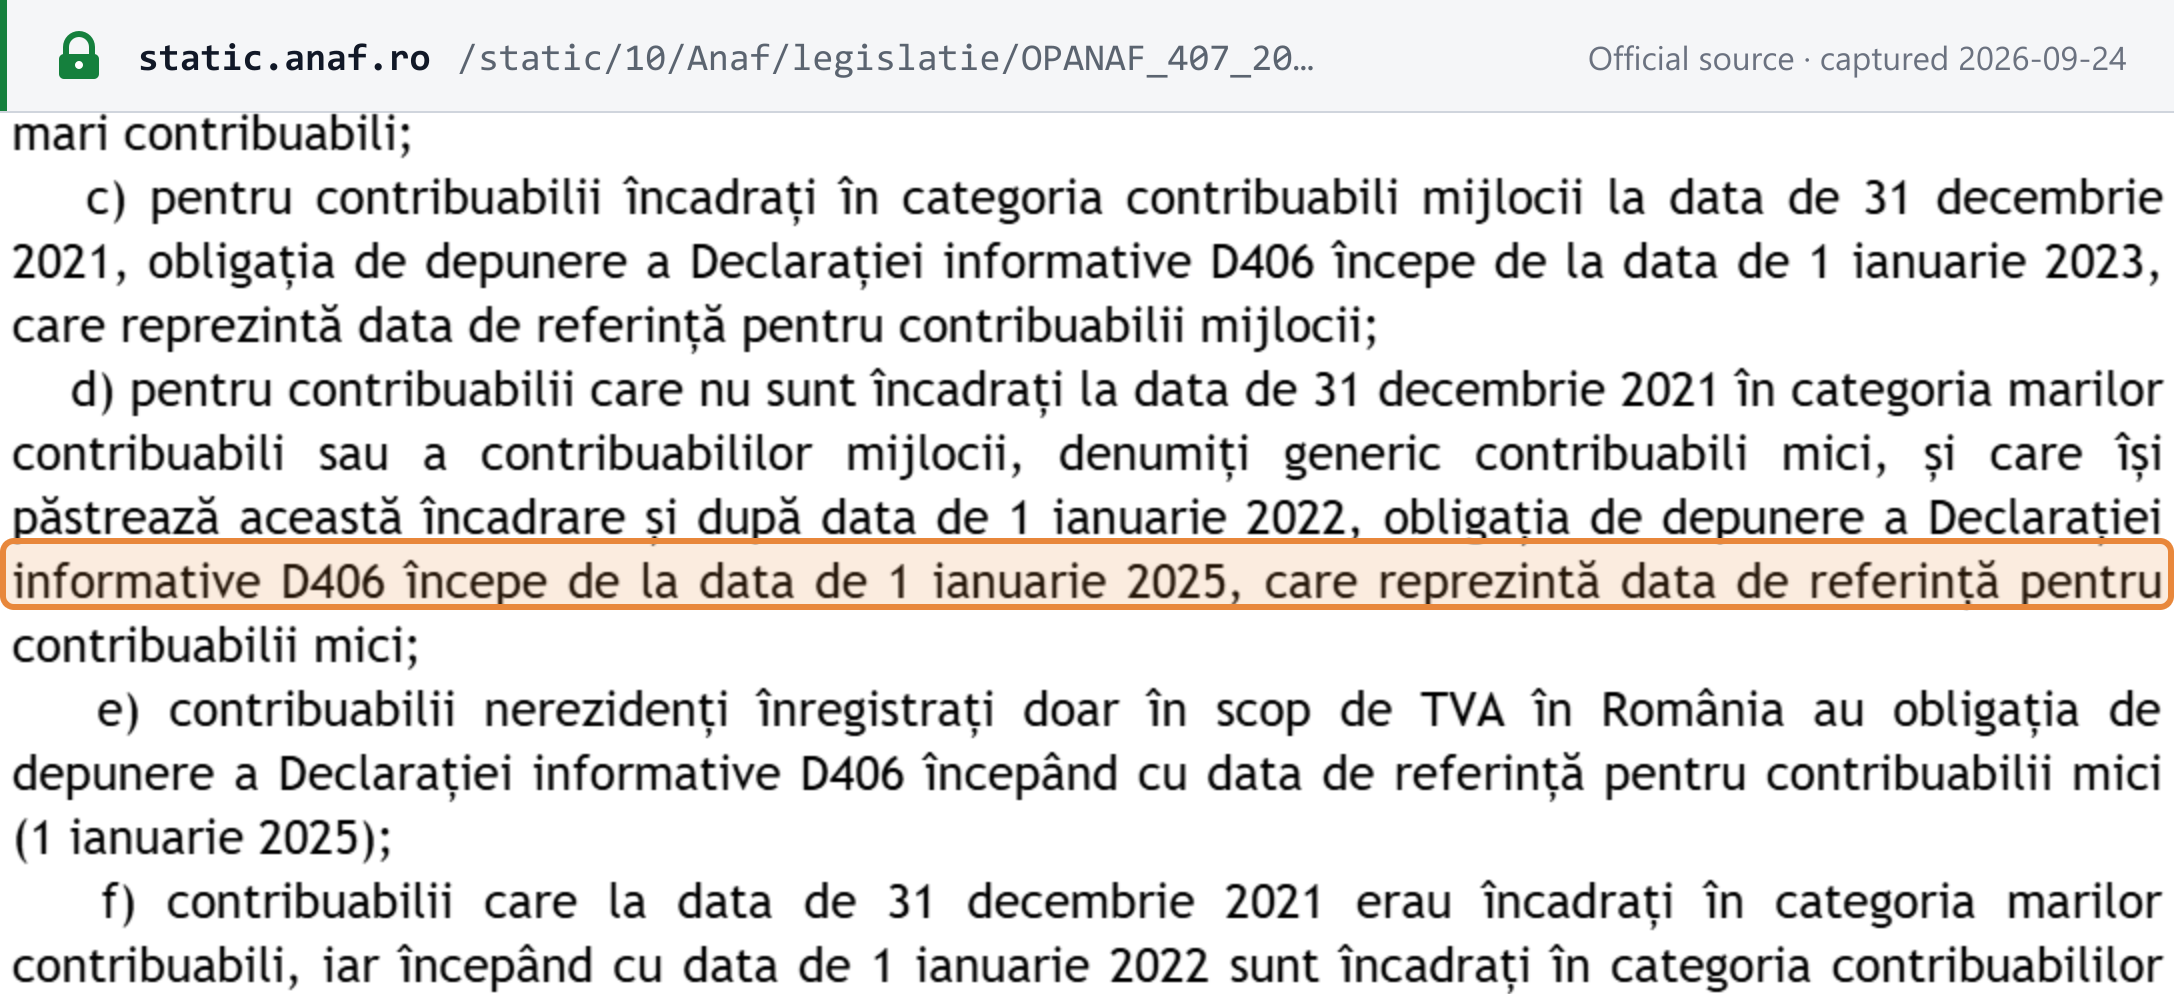
- Romania (D406). Large taxpayers since 1 January 2022, medium since 1 January 2023, and small taxpayers — plus non-residents registered only for VAT in Romania — since 1 January 2025. Excluded: individual traders and family businesses (PFA, II, IF), lawyers' and notaries' offices, individual medical practices, insolvency practitioners' firms, public institutions and a few other listed categories. (OPANAF 407/2025, annex pts 1.1 and 4)
- Poland (JPK_CIT). Phased by taxpayer type over tax years starting in 2025, 2026 and 2027 (see Current status).
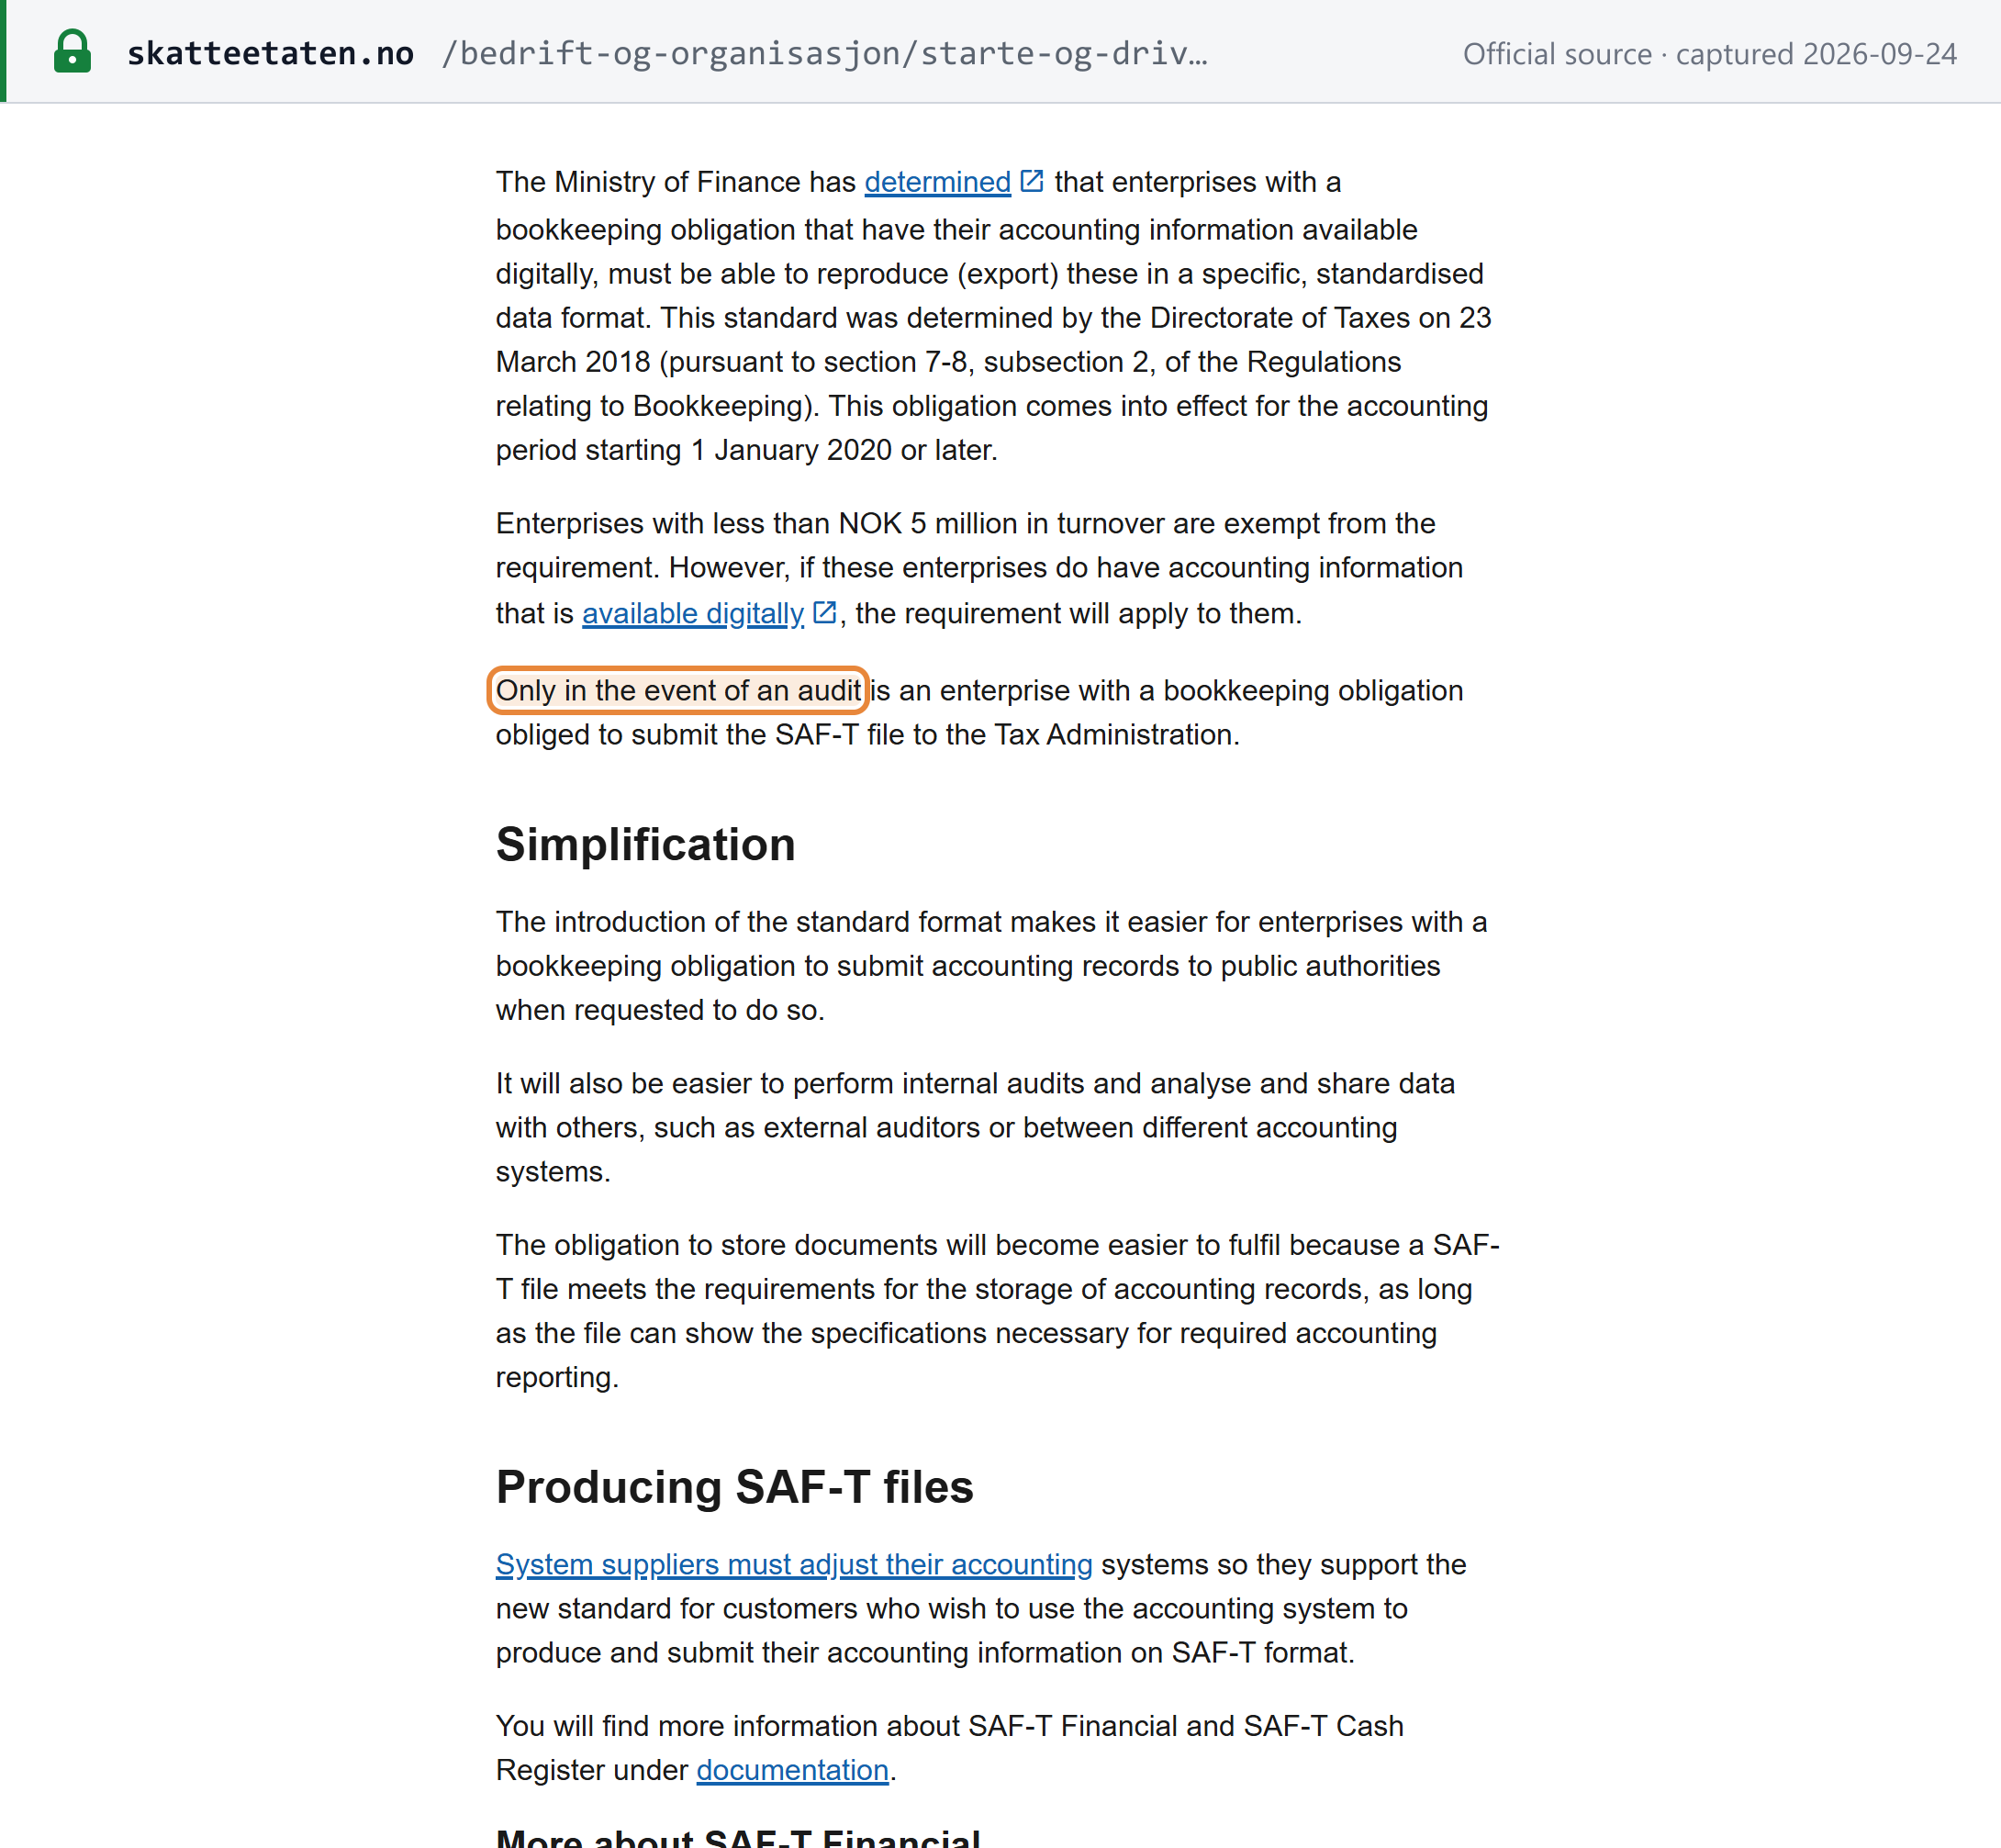
- Norway. Businesses with electronically available accounting records. Those with turnover under NOK 5 million are exempt, unless they keep their records electronically available anyway. (Skatteetaten)
- Lithuania (i.SAF-T on request). For-profit entities keeping accounts by technical means, phased in by net sales income. Foreign VAT-registered companies, branches and permanent establishments are not required. (VMI)
- Luxembourg (FAIA). Any taxable person with a computerised accounting system. The AED's FAQ (version March 2013) excludes, among others, taxable persons with annual turnover not above EUR 112,000. (AED FAIA FAQ)
A non-resident registered only for VAT is caught by periodic filing in Romania (D406, since 1 January 2025), and by transaction-level VAT filings in Poland (JPK_V7M/K with every VAT return — VAT Act art. 109 ust. 3b binds all taxpayers under art. 99 ust. 1; Dz.U. 2025 poz. 775) and Lithuania (i.SAF invoice registers, required of taxable persons registered as VAT payers in Lithuania; VMI). (checked 2026-09-24)
Current status and dates
As at 2026-09-24. Each row is cited in the paragraphs and tables below.
| Date | What changes | Status |
|---|---|---|
| 1 Jan 2022 | Romania D406 starts for large taxpayers (newly large taxpayers from 1 Jul 2022) | In force |
| 1 Jan 2023 | Romania D406 extends to medium taxpayers, and to large-taxpayer banks, financial institutions and insurers | In force |
| 1 Jan 2025 | Romania D406 extends to small taxpayers and to non-residents registered only for VAT | In force |
| Tax years starting after 31 Dec 2024 | Poland JPK_CIT, tier 1: tax capital groups, and taxpayers whose prior-year revenue exceeded EUR 50 million | In force; calendar-year 2025 files were due by 31 Jul 2026 |
| Tax years starting after 31 Dec 2025 | Poland JPK_CIT, tier 2: taxpayers filing JPK_V7 records under VAT Act art. 109 ust. 3b | In force since 1 Jan 2026 (tax years begun in 2026); calendar-year 2026 files due by 31 Jul 2027 |
| 1 Feb 2026 | Poland JPK_V7M(3) structure replaces JPK_V7M(2) | In force |
| 1 Jul 2026 | Poland: JPK_CIT deadline becomes the end of the 7th month after the tax year | In force |
| 1 Jan 2027 | Norway: SAF-T Financial schema v1.40 becomes mandatory | Announced by Skatteetaten |
| Tax years starting after 31 Dec 2026 | Poland JPK_CIT, tier 3: all remaining taxpayers and non-legal-person partnerships | Enacted |
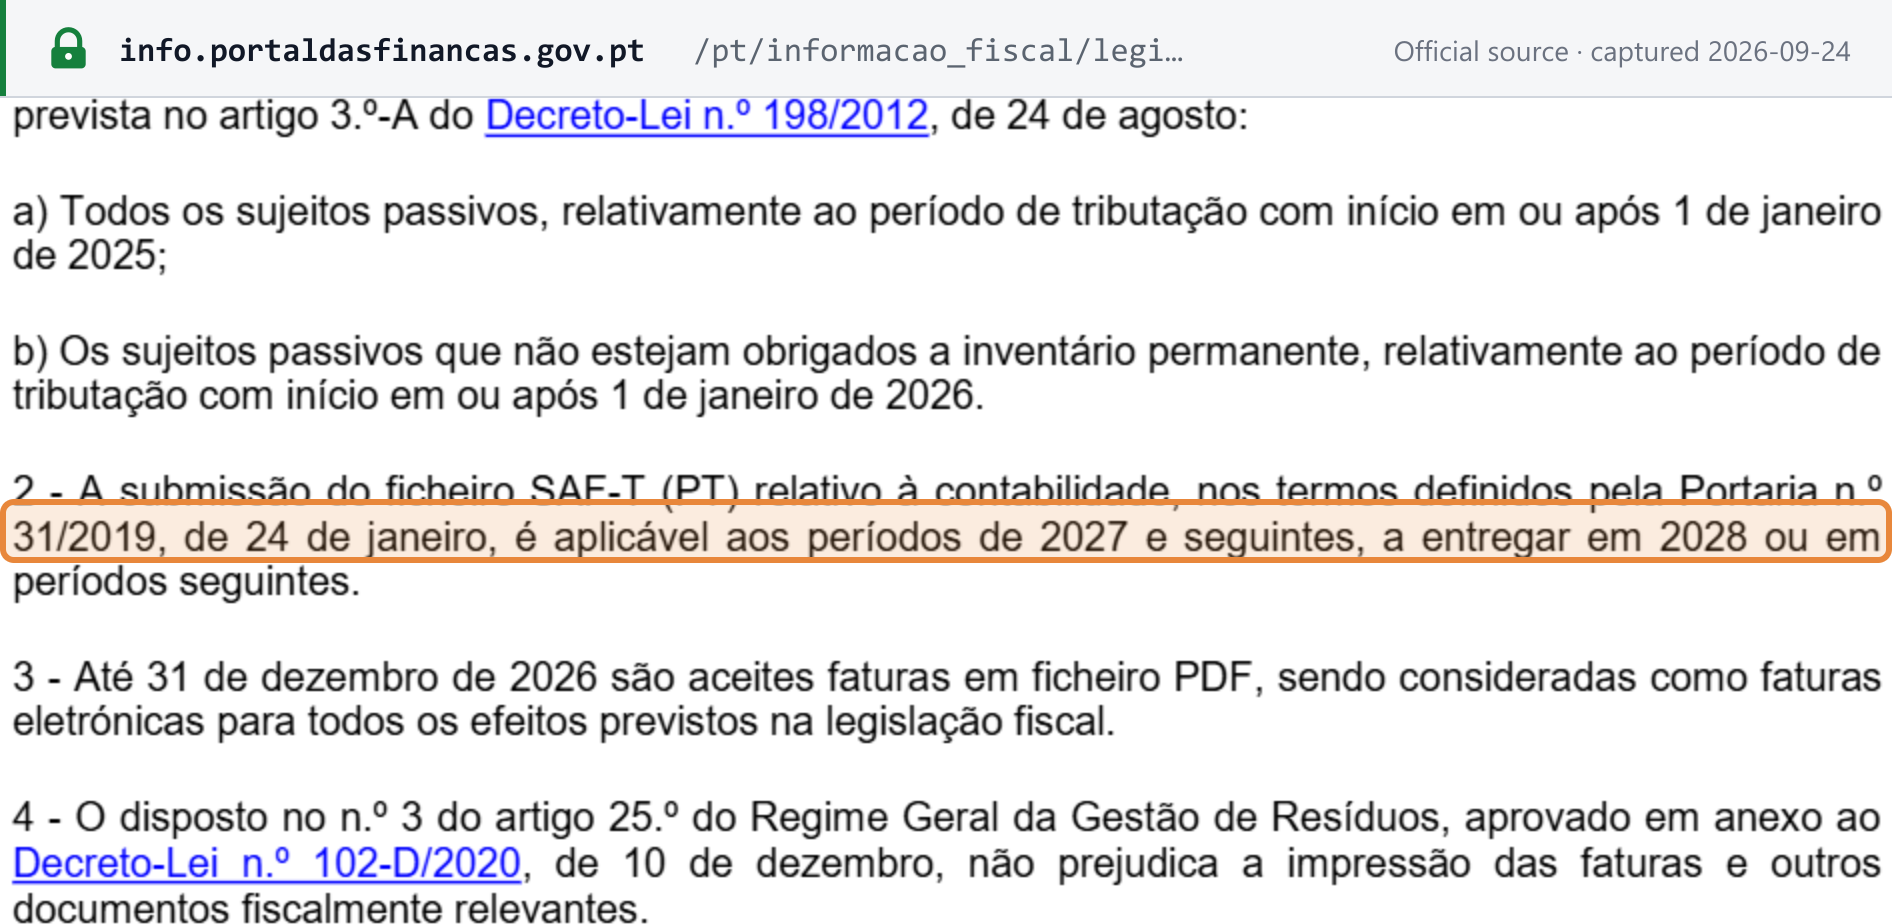
| Periods 2027 onward, filed 2028 or later | Portugal: annual submission of the accounting SAF-T (PT) | Enacted in the 2026 budget law; applies from 2027 periods, first filing in 2028 |
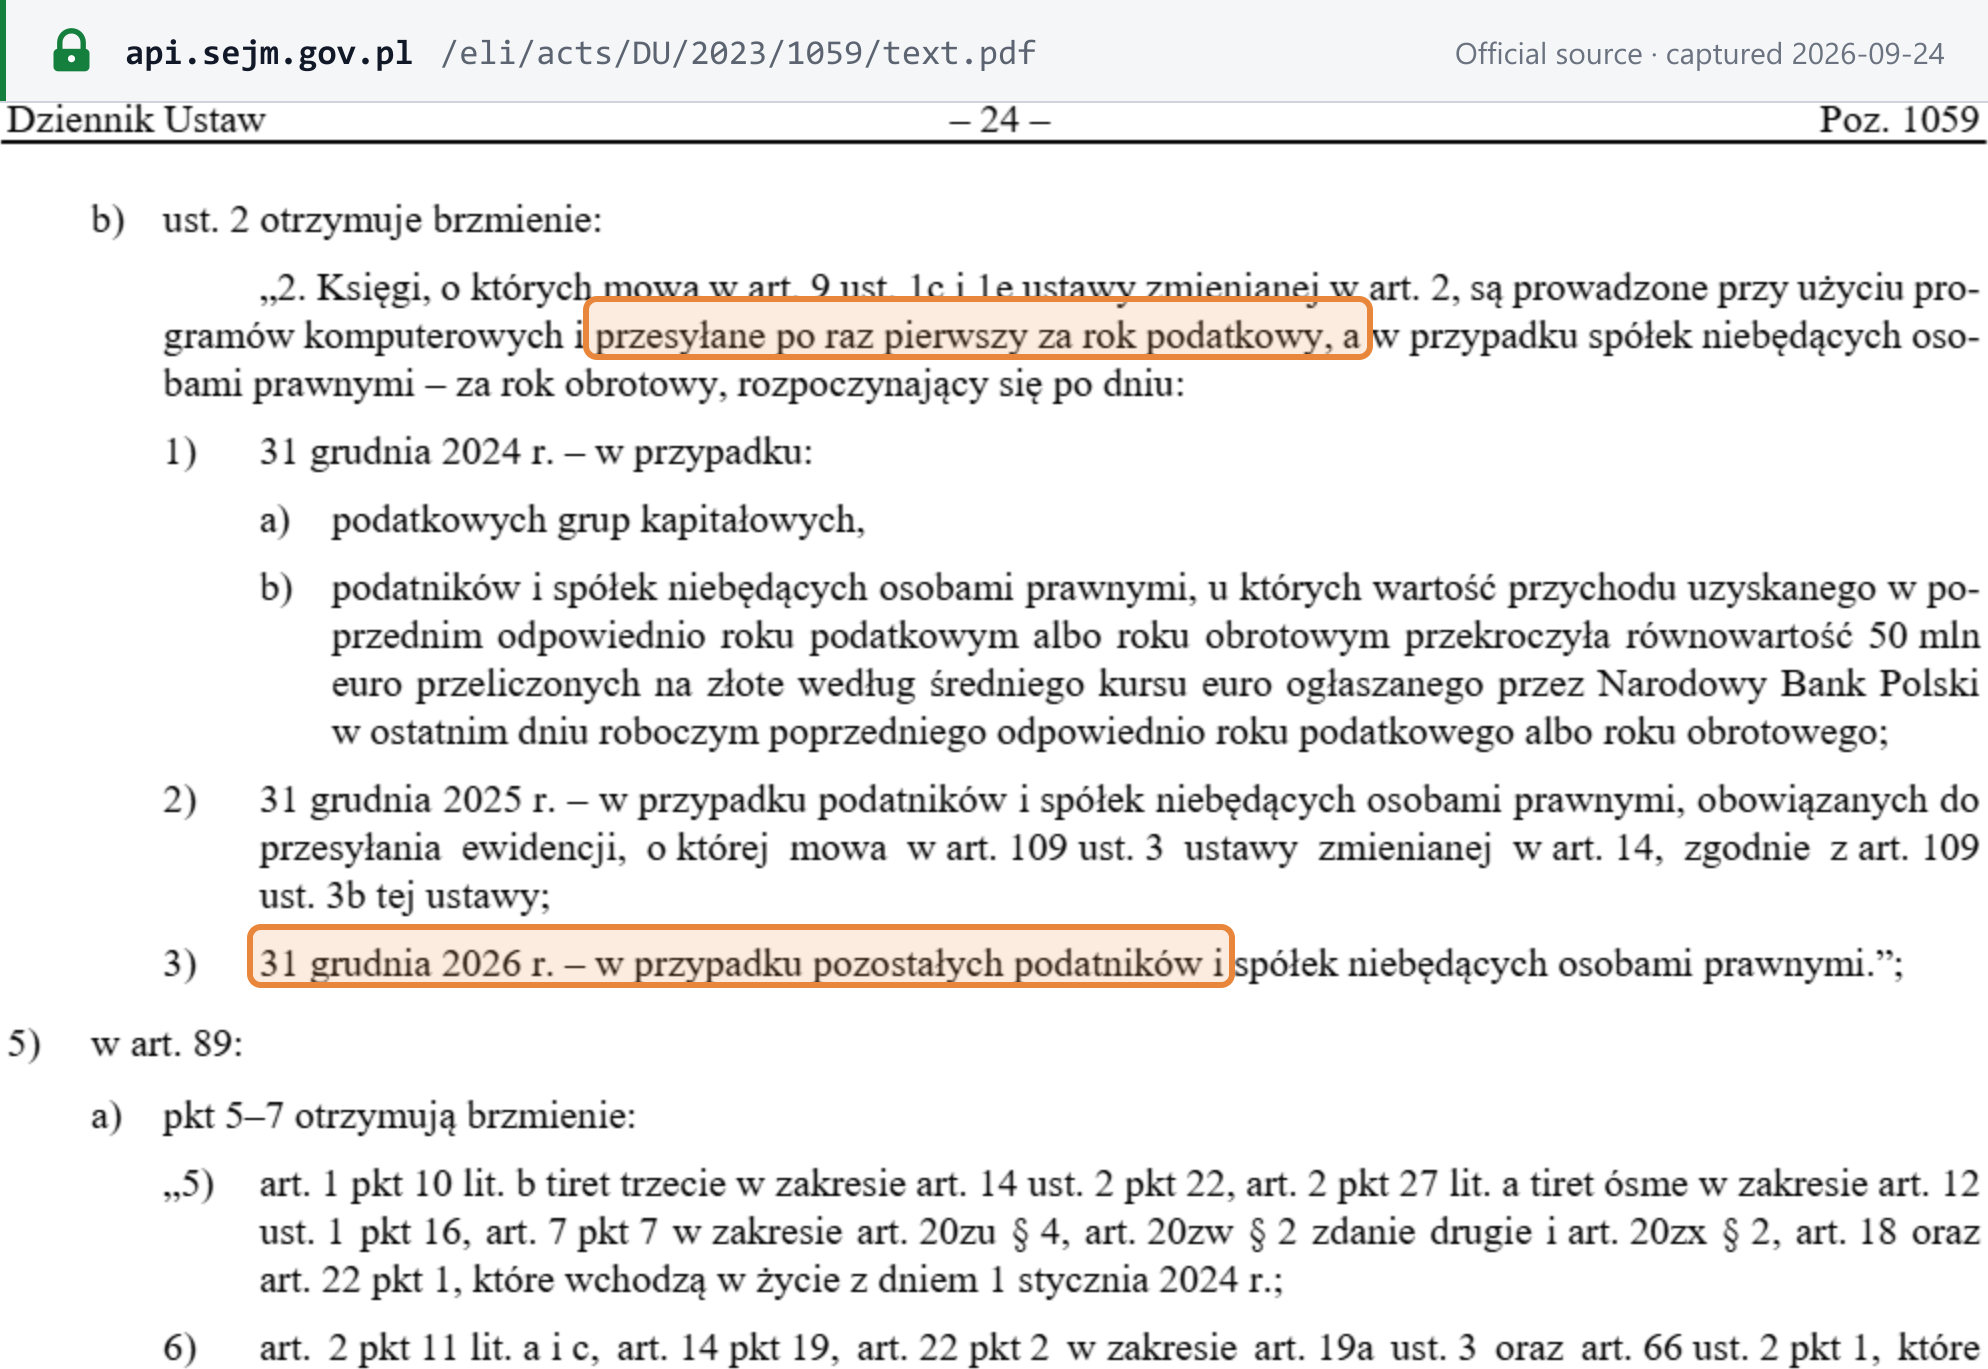
Poland — JPK_CIT. CIT taxpayers that keep accounting books must keep them electronically and send them to the tax authority after the year ends, in three tiers set by art. 66 ust. 2 of the Act of 29 October 2021 as rewritten in 2023. The provision opens: "Księgi, o których mowa w art. 9 ust. 1c i 1e ustawy zmienianej w art. 2, są prowadzone przy użyciu programów komputerowych i przesyłane po raz pierwszy za rok podatkowy" — the books are kept by computer and sent for the first time for the tax year starting after the tier date. (Dz.U. 2023 poz. 1059, art. 13 pkt 4, checked 2026-09-24)
 Source snapshot captured 2026-09-24 — original
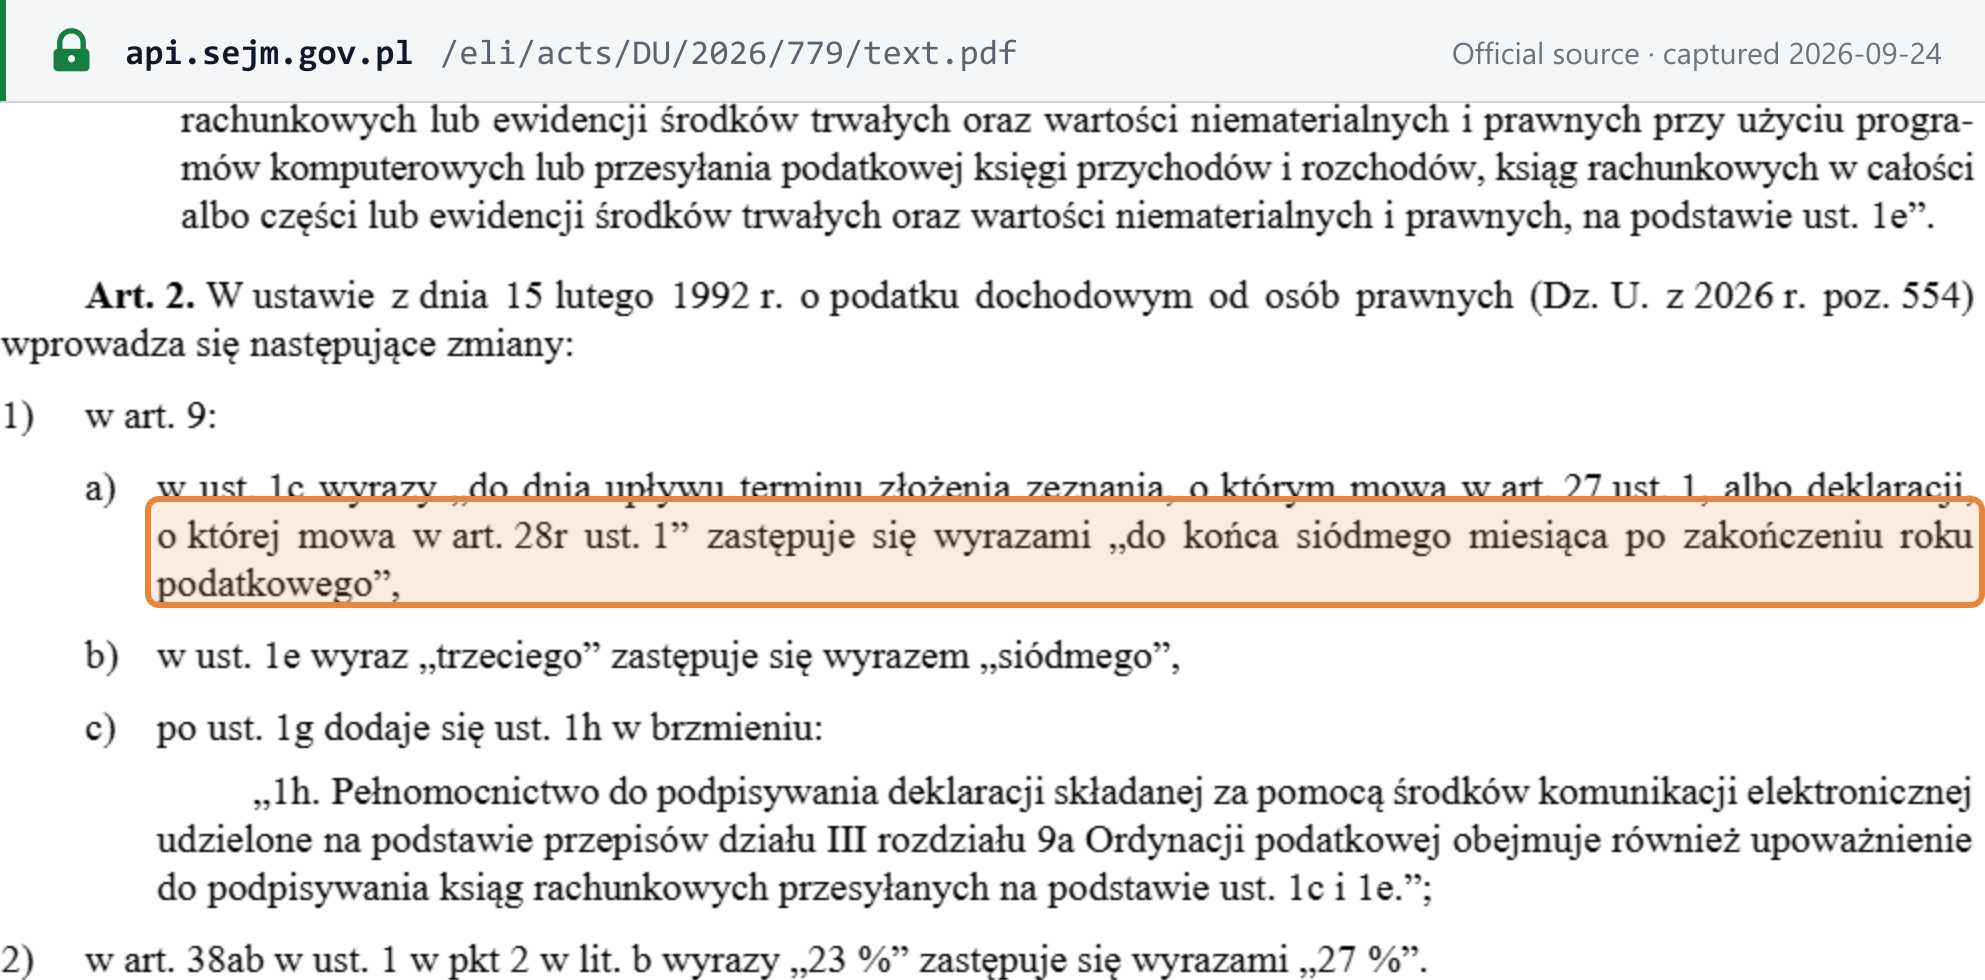
The deadline changed twice in 2026. A regulation of 16 February 2026 (in force 20 February 2026) extended the deadline to the end of the seventh month after year-end for tax years that started after 31 December 2024 and ended before 1 April 2026 (§ 1), which moved calendar-year 2025 books to 31 July 2026. It also extended the transitional end-of-March-2026 deadline for earlier-ending years to the end of July 2026 (§ 2). (Dz.U. 2026 poz. 188) The Act of 15 May 2026 then wrote the rule into the CIT Act permanently: from 1 July 2026, art. 9 ust. 1c requires the books "do końca siódmego miesiąca po zakończeniu roku podatkowego" — by the end of the seventh month after the tax year ends. (Dz.U. 2026 poz. 779, art. 2 pkt 1 lit. a and art. 5, checked 2026-09-24)
 Source snapshot captured 2026-09-24 — original
The same 2023 act sets a parallel timetable for personal-income-tax books and asset registers: first files for tax years starting after 31 December 2025 for JPK_V7 filers, and after 31 December 2026 for everyone else.
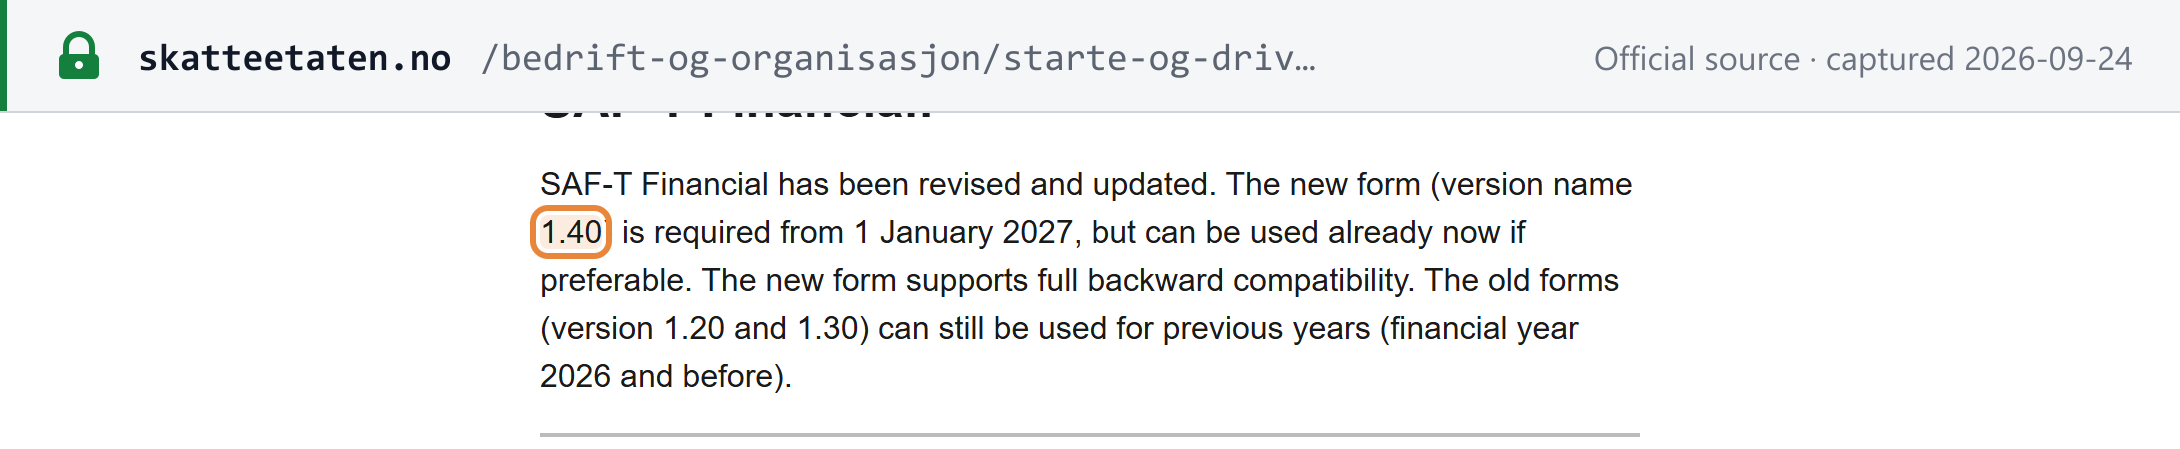
Norway — schema v1.40. "Nytt skjema (versjonsnavn 1.40) er pliktig fra 1. januar 2027, men kan tas i bruk umiddelbart om ønskelig." — the new schema (version 1.40) is mandatory from 1 January 2027 and may be used now. Versions 1.20 and 1.30 remain usable for financial years 2026 and earlier. (Skatteetaten, SAF-T Regnskap documentation, checked 2026-09-24)
 Source snapshot captured 2026-09-24 — original
Portugal — accounting SAF-T (PT). The 2026 State Budget law sets the start: "A submissão do ficheiro SAF-T (PT) relativo à contabilidade, nos termos definidos pela Portaria n.º 31/2019, de 24 de janeiro, é aplicável aos períodos de 2027 e seguintes, a entregar em 2028 ou em períodos seguintes." — the accounting SAF-T (PT) applies to periods of 2027 onward, to be submitted in 2028 or later. (Lei n.º 73-A/2025, art. 95.º n.º 2, checked 2026-09-24) The start date sits in annual budget law, so treat 2028 as the current legal position and check each new State Budget.
 Source snapshot captured 2026-09-24 — original
Jurisdiction table
Every row below is dated and sourced; rows marked (partial) are only partly confirmed. The list is not exhaustive: a country missing from it (Angola, for example, is not covered) is not a statement that the country has no SAF-T obligation.
Periodic submission
| Jurisdiction | Obligation | Cadence and deadline | Since / status | Last confirmed | Source |
|---|---|---|---|---|---|
| Romania | D406 informative return (SAF-T) | Monthly or quarterly, following the VAT period; taxpayers not registered for VAT report quarterly. Due by the last calendar day of the month after the period. The Assets section is filed annually; the Stocks section only on request, with at least 30 days to comply¹ | Large taxpayers 1 Jan 2022 · medium taxpayers, and large-taxpayer banks, financial institutions and insurers 1 Jan 2023 · small taxpayers and VAT-only non-residents 1 Jan 2025 | 2026-09-24 | OPANAF 1783/2021 art. 4 and Annex 4; OPANAF 407/2025 |
| Poland | JPK_V7M / JPK_V7K (VAT records sent with the return) | Monthly filers: with the return, by the 25th of the following month. Quarterly filers: months 1 and 2 by the 25th of the following month, month 3 with the quarterly return | In force; structure JPK_V7M(3) since 1 Feb 2026 | 2026-09-24 | VAT Act art. 99 and art. 109 ust. 3b–3c (Dz.U. 2025 poz. 775); Ministry of Finance — new JPK_VAT structures |
| Poland | JPK_CIT (JPK_KR_PD and JPK_ST_KR) | Annual, by the end of the 7th month after the tax year | Tiered: tax years starting after 31 Dec 2024 / 2025 / 2026 | 2026-09-24 | Dz.U. 2023 poz. 1059; Dz.U. 2026 poz. 779 |
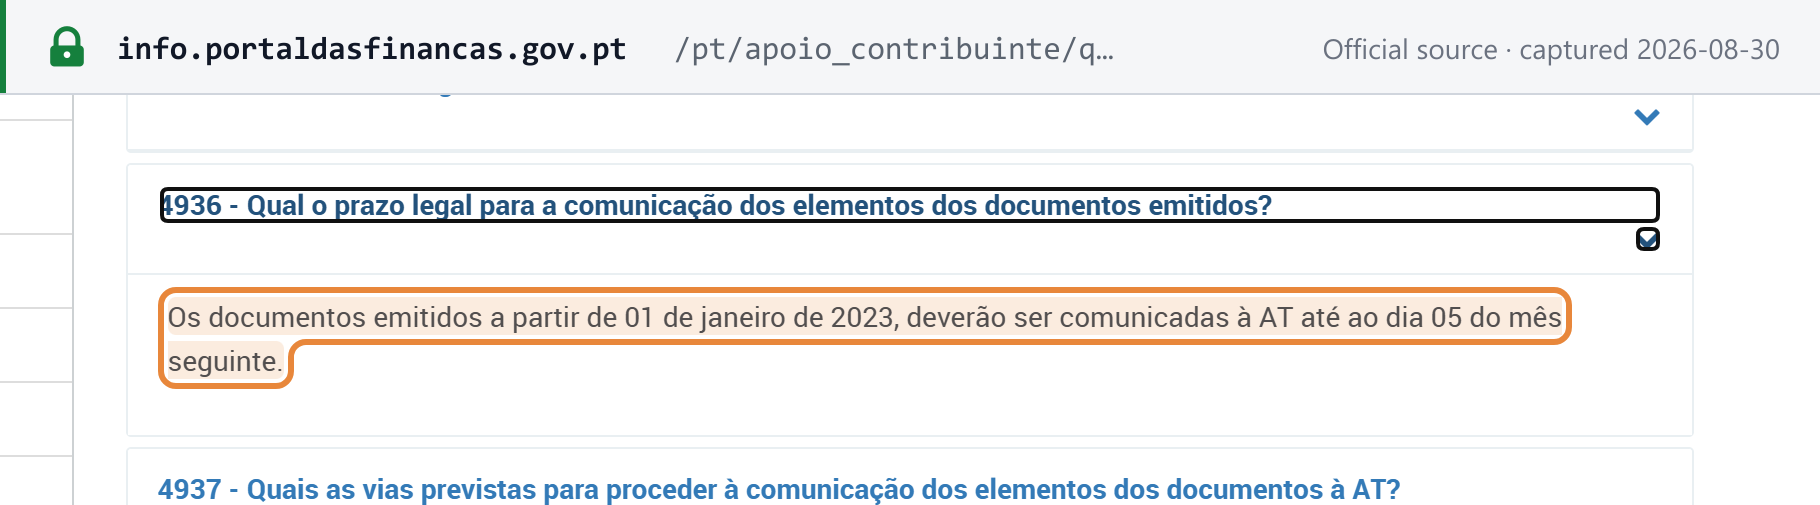
| Portugal | Communication of invoice data to the AT; upload of the SAF-T (PT)-based file is one of three channels, alongside a webservice and direct entry on the Portal das Finanças | Monthly, by day 5 of the following month | For documents issued from 1 Jan 2023; file format v1.04_01 for invoices from 1 Jul 2017 | 2026-09-24 | AT e-Fatura FAQ 4936–4946 |
| Portugal | Accounting SAF-T (PT) | Annual | Not yet applicable: periods 2027 onward, filed 2028 or later | 2026-09-24 | Lei n.º 73-A/2025 art. 95.º n.º 2 |
| Lithuania | i.SAF: issued and received VAT invoice registers (SAF-based invoice reporting, not a full accounting SAF-T) | Monthly, by the 20th of the following month (legal persons) | In force; all VAT payers except users of the SVS small-business scheme | 2026-09-24 | VMI |
¹ Cadence and the Stocks rule as set by Annex 4 to OPANAF 1783/2021 in its November 2021 text.
 Source snapshot captured 2026-09-24 — original
 Source snapshot captured 2026-08-30 — original
On request (and export capability)
| Jurisdiction | Obligation | When the file is handed over | Since / status | Last confirmed | Source |
|---|---|---|---|---|---|
| Norway | SAF-T Financial (SAF-T Regnskap) | Only on request during a control | Accounting periods starting on or after 1 Jan 2020; turnover under NOK 5 million exempt unless records are kept electronically available; schema v1.40 mandatory from 1 Jan 2027 | 2026-09-24 | Skatteetaten; bokføringsforskriften § 7-8 |
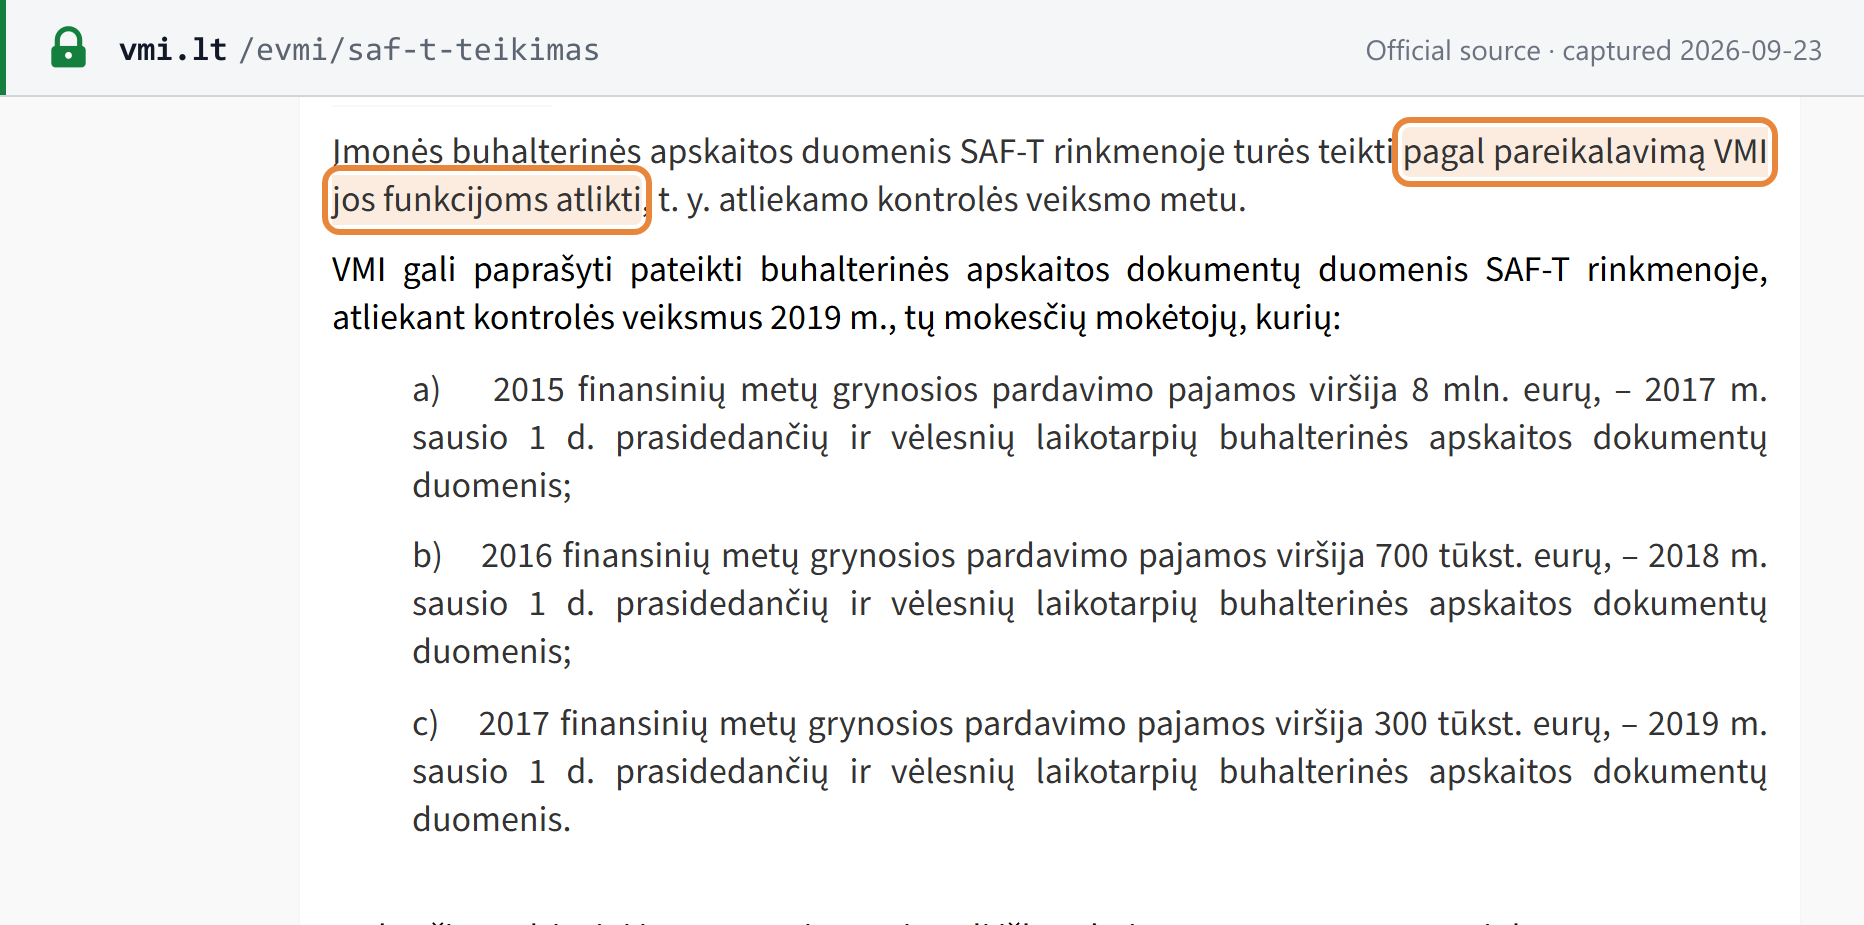
| Lithuania | i.SAF-T (full accounting SAF-T) | On VMI's demand during a control action | Accounting data from 1 Jan 2017 (net sales above EUR 8 million in 2015), 1 Jan 2018 (above EUR 700,000 in 2016), 1 Jan 2019 (above EUR 300,000 in 2017) | 2026-09-24 | VMI |
| Poland | JPK on demand (books and accounting evidence in the published JPK structures, such as JPK_KR, JPK_FA, JPK_MAG) | When the tax authority demands all or part of the books | In force; the power does not apply to structured KSeF invoices, or to outage/offline invoices once sent to KSeF | 2026-09-24 | Ordynacja podatkowa art. 193a § 1–1a (Dz.U. 2026 poz. 622) |
| Portugal | SAF-T (PT) export capability | IRC taxpayers keeping computerised accounts must be able to export files in the format set by portaria | In force | 2026-09-24 | Código do IRC art. 123.º n.º 8 |
| Luxembourg | FAIA (Fichier d'Audit Informatisé AED), version 2.01 | When the AED asks (art. 70(3) LTVA) | Supplied on request since the close of FY2011; the AED FAQ (March 2013) excludes, among others, turnover up to EUR 112,000 | 2026-09-24 | AED — FAIA; FAIA 2.01 |
| Austria | SAF-T AT (schema v1.01), one permitted format for handing over data | When data is requested under §§ 131 and 132 BAO; SAF-T is optional | Permitted format since the BMF decree of 20 Mar 2009 | 2026-09-24 | BMF |
| Denmark | Standard file from digital standard bookkeeping systems (cloud and hybrid systems offered to businesses generally) | No filing: the system must be able to generate, export and import a standard file defined by the authorities | Executive Order 97/2023, in force 1 Feb 2023 (§§ 5–12 from 1 Nov 2023 for systems already on the market). The order points to erst.dk for the file specification; its version and any later steps are not confirmed here | 2026-09-24 (partial) | Retsinformation, BEK nr. 97/2023 |
"Det er kun på forespørsel ved en kontroll at de bokføringspliktige plikter å sende SAF-T filen til Skatteetaten." — only on request during a control are businesses with a bookkeeping obligation required to send the SAF-T file to the Tax Administration. (Skatteetaten, checked 2026-09-24)
 Source snapshot captured 2026-09-24 — original
 Source snapshot captured 2026-09-23 — original
Austria. The BMF's SAF-T page describes SAF-T as an additional permitted format for providing data, and publishes no periodic SAF-T filing obligation (checked 2026-09-24).
France's FEC is comparable, but it is not SAF-T. The fichier des écritures comptables is a French national format with its own standard (LPF art. A. 47 A-1), not the OECD schema. A business with computerised accounts hands it over at a tax audit. BOFiP states: "Cette disposition est obligatoire pour les contrôles pour lesquels l'avis de vérification est adressé depuis le 1 er janvier 2014" — this is mandatory for audits whose notice was sent from 1 January 2014. (BOFiP, BOI-CF-IOR-60-40-10, para 20, checked 2026-09-24)
Germany's rules on tax-auditor access to accounting data are covered in the GoBD explainer.
Related changes from the feed
No SAF-T change has been recorded in the weekly updates yet (as at 2026-09-24); see the country chronologies: Poland · Portugal · Romania · Norway · Lithuania
Frequently asked questions
Is SAF-T a return I have to file every month?
It depends on the country. The OECD standard leaves how and when the file is produced to each revenue body. Romania (D406, monthly or quarterly), Poland (JPK_V7M/K with each VAT return, and JPK_CIT annually) and Portugal (invoice data by day 5 of the following month) require periodic filing. Norway, Lithuania (i.SAF-T) and Luxembourg (FAIA) require the file only when the tax authority asks, typically during an audit. In Austria, SAF-T is one optional format for data handed over on request. (OECD guidance note v2.0, para 33; national sources in the tables above, checked 2026-09-24)
We invoice through KSeF in Poland. Do we still file JPK_V7M, and can the tax office still demand JPK_FA?
JPK_V7M: yes. The VAT records are still sent with the return by its deadline (VAT Act art. 109 ust. 3b). On-demand JPK: the tax authority's power to demand books in JPK form does not apply to structured (KSeF) invoices, or to invoices issued outside KSeF during outages or in offline mode once they have been sent to KSeF (Ordynacja podatkowa art. 193a § 1a, Dz.U. 2026 poz. 622). The power still covers other books and accounting evidence. (checked 2026-09-24)
When is our first JPK_CIT due?
It depends on your tier. Tax capital groups, and taxpayers whose prior-year revenue exceeded EUR 50 million, send books for tax years starting after 31 December 2024. Taxpayers filing JPK_V7 records under VAT Act art. 109 ust. 3b follow for tax years starting after 31 December 2025, and all remaining taxpayers and non-legal-person partnerships for tax years starting after 31 December 2026. The deadline is the end of the seventh month after the tax year ends (CIT Act art. 9 ust. 1c as amended by Dz.U. 2026 poz. 779, in force 1 July 2026). For calendar-year 2025 the first tier's files were due by 31 July 2026; calendar-year 2026 files from the second tier are due by 31 July 2027. (Dz.U. 2023 poz. 1059; checked 2026-09-24)
We are a non-resident registered only for VAT in Romania. Do we have to file D406?
Yes. Non-residents registered only for VAT purposes in Romania must file D406 from the small-taxpayer reference date, 1 January 2025. (OPANAF 407/2025, annex pt. 1.1 lit. e; checked 2026-09-24)
Does a Norwegian business have to send SAF-T files to Skatteetaten?
Only on request during a control. Businesses with electronically available accounting records must be able to export them in the SAF-T Financial format for accounting periods starting on or after 1 January 2020. Businesses with turnover under NOK 5 million are exempt, unless they keep their records electronically available anyway. Schema version 1.40 is mandatory from 1 January 2027. (Skatteetaten, checked 2026-09-24)
When does Portugal's annual accounting SAF-T start?
Under the 2026 State Budget law (Lei n.º 73-A/2025, art. 95.º n.º 2), the accounting SAF-T (PT) under Portaria n.º 31/2019 applies to periods of 2027 onward, to be submitted in 2028 or later. It is separate from the monthly communication of invoice data, which has been due by day 5 of the following month for documents issued since 1 January 2023. (checked 2026-09-24)
Related resources
- Poland VAT guide and KSeF e-invoicing in Poland — how JPK_V7 sits alongside KSeF
- Portugal VAT guide and e-invoicing in Portugal — the SAF-T (PT) day-5 rule
- Lithuania VAT guide — i.SAF and i.SAF-T
- Luxembourg VAT guide — FAIA
- Austria VAT guide
- Denmark VAT guide
- E-invoicing in Norway
- Romania tax ID guide
- GoBD explainer — Germany's rules for digital records and auditor data access
- ViDA — VAT in the Digital Age — the EU's move to transaction-level digital reporting
- VAT listings explained
- E-invoicing status worldwide — every national mandate, dated and sourced
Reference documents
- Guidance for the Standard Audit File – Tax, Version 2.0 — OECD Forum on Tax Administration, April 2010
- Appendix B: SAF-T Schema version 2.00 — OECD
- ANAF — SAF-T (D406) project page — schemas, validator and orders
- Skatteetaten — SAF-T Regnskap
- VMI — SAF-T teikimas
- AED — FAIA
- BMF — Standard Audit File-Tax