How to Register a Business in Brazil (CNPJ, ICMS, ISS)
Brazil has no single "register for tax" step
Unlike a VAT-threshold country, Brazil does not have one registration that unlocks trading. A business climbs a ladder of separate registrations, run by separate authorities, each depending on the one before it:
Junta Comercial (NIRE) → CNPJ (Receita Federal) → Inscrição Estadual (state SEFAZ, for ICMS on goods) → Inscrição Municipal / CCM (city prefeitura, for ISS on services)
REDESIM — the Rede Nacional para a Simplificação do Registro e da Legalização de Empresas e Negócios — is the shared front door across most of this ladder, integrating the Juntas Comerciais, DREI, Receita Federal, the states and the municipalities into one flow.[1] It is not, however, a single automatic pipeline: the state and municipal legs are independently reviewed and can be refused, as the sections below show. This page walks the ladder in the order a registrant actually hits it, not in the order a generic VAT-registration checklist would suggest.
For the tax rates, invoice rules and the CBS/IBS reform this registration ladder feeds into, see the Brazil VAT (CBS/IBS) guidelines. For CNPJ/CPF formats, checksums and status values, see the Brazil Tax ID Guide. To look up an existing CNPJ, see How to verify a CNPJ number in Brazil.
Who must register
The CNPJ trigger has no turnover floor
The obligation to register for a CNPJ is set out in Chapter II (articles 3 and 4) of Instrução Normativa RFB nº 2.119, of 6 December 2022: "A obrigação de se inscrever no CNPJ está definida pelo Capítulo II (art. 3º ao art. 4º) da IN RFB 2.119, de 06 de dezembro de 2022" ("The obligation to register in the CNPJ is defined by Chapter II, articles 3 to 4, of IN RFB 2,119, of 6 December 2022").[2] That test turns on what the entity IS — a legal entity carrying on an activity — not on a revenue amount. There is no minimum-turnover floor to cross before ordinary CNPJ registration becomes mandatory, unlike a VAT-registration-threshold country.
From 1 January 2027, this obligation extends to individuals (pessoas físicas) who are CBS and/or IBS taxpayers — postponed from an original 1 July 2026 start date by Decreto nº 13.075/2026. This is fully sourced on the Brazil VAT (CBS/IBS) guidelines page; it does not convert the individual into a legal entity, and exists solely to facilitate CBS/IBS assessment.
Voluntary or early registration — not applicable in the usual sense
In a VAT-threshold country, "can I register before I cross the threshold" is a meaningful question. In Brazil it is not, because there is no threshold to register ahead of — Receita Federal's own "quem está obrigado" guidance is silent on any turnover test (checked 2026-09-20). The closest analogue is a newly incorporated business choosing its tax regime — MEI, Simples Nacional, Lucro Presumido or Lucro Real — at the moment of CNPJ registration; see Simples Nacional election below.
Where to register: the ladder, in order
| Rung | Authority | Registers | Required for |
|---|---|---|---|
| 1. Junta Comercial (or Cartório / OAB seccional) | State commercial registry | The constitutive act; issues the NIRE | Every commercial entity, before CNPJ can be generated |
| 2. CNPJ | Receita Federal do Brasil | National taxpayer number | Every legal entity — no turnover floor |
| 3. Inscrição Estadual | State SEFAZ | State ICMS registration | Businesses trading in ICMS-taxed goods |
| 4. Inscrição Municipal / CCM | City prefeitura | Municipal ISS registration | Businesses supplying ISS-taxed services |
A goods business typically needs rungs 1–3; a services business typically needs rungs 1, 2 and 4; many businesses need both 3 and 4.
REDESIM is the front door, not the whole building
REDESIM's own scope statement is that it brings the Juntas Comerciais, DREI, Receita Federal, the states and the municipalities together in one registration flow, with the CNPJ leg itself running through the Coletor Nacional (redesimservicos.rfb.gov.br).[1] That is real integration for rungs 1 and 2. It is only partial for rung 3: São Paulo's Secretaria da Fazenda states that "O pedido de Inscrição Estadual é efetuado pela internet no Portal da REDESIM" ("The Inscrição Estadual application is made online through the REDESIM Portal") — but the same page adds that "Demais documentos (e/ou declarações/informações) exigidos pela unidade da SEFAZ competente" ("Further documents, declarations or information may be required by the competent SEFAZ unit") apply.[3] In other words, REDESIM routes the Inscrição Estadual request — it does not decide it. SEFAZ São Paulo independently reviews it and can reject the application or demand more paperwork (exigência) before granting it.
Rung 4, Inscrição Municipal/CCM, integrates with REDESIM unevenly by city — no single official source enumerates which municipalities are and are not integrated. Treat São Paulo (used as the worked example above) as illustrative rather than universal, and check your own prefeitura's REDESIM or Cadastro Mobiliário page before assuming the municipal step is automatic.
Prerequisites and documents
The constitutive act sits upstream of the CNPJ
DREI (Departamento Nacional de Registro Empresarial e Integração) states the order plainly: after the DBE (Documento Básico de Entrada) is approved, "o empreendedor registra-se na junta comercial de seu estado" ("the entrepreneur registers at the Junta Comercial of their state") and "o CNPJ será gerado ao final desse procedimento" ("the CNPJ will be generated at the end of that procedure").[4] The NIRE (Número de Identificação do Registro de Empresas) from the Junta Comercial is therefore issued before the CNPJ, not after — the reverse of what a reader coming from a single-registration country might expect. Civil-society entities and law firms register their constitutive act at a Cartório de Registro Civil de Pessoas Jurídicas or an OAB seccional instead of a Junta Comercial.
Foreign-owned entities: a Brazil-resident procurador is mandatory
A foreign entity or foreign individual becoming a partner in, or directly registering, a Brazilian legal entity must appoint a Brazil-resident procurador (attorney-in-fact) who holds a CPF and powers to manage the entity's Brazilian assets and to receive legal citations on its behalf. This rule, and its statutory basis in article 6 of Instrução Normativa RFB 2.119/2022, is fully sourced on the Brazil Tax ID Guide — see that page for the exact statutory text rather than re-deriving it here.
The process, step by step
The official CNPJ process map
Receita Federal's own service listing for "Inscrever Entidade no Cadastro Nacional de Pessoas Jurídicas" lays out the flow in six stages:[5]
- Consult viability — check the proposed name, activity and address against municipal rules.
- Inform the constitutive-act data — submit the DBE with the proposed entity's founding details.
- Register the constitutive act at the competent body — the Junta Comercial for commercial entities, or a Cartório de Registro Civil de Pessoas Jurídicas / OAB seccional for others.
- Send documents to Receita Federal, where the registering office is not REDESIM-integrated or an exemption applies.
- Track the protocol, confirm the tax regime and accountant data, then sign and receive the CNPJ.
- Obtain operating licenses — sanitary, environmental or other licenses, as applicable to the activity.
Receita Federal states an average processing time of about 24 hours for this service — "Em média 24 hora(s) é o tempo estimado para a prestação deste serviço" — and that Junta Comercial, Cartório and OAB fees are "valor variável" (variable amount), to be checked with each state's own registry: "Consulte, no seu Estado/DF, as taxas das Juntas Comerciais, dos Cartórios de PJ e das Seccionais da OAB."[5] Receita Federal itself charges no fee for the CNPJ registration service.
Non-resident individuals: the CPF route has no online path for foreigners
This is the most-asked question about registering in Brazil, and one of the more commonly mis-answered: a foreigner residing outside Brazil cannot apply for a first-time CPF online. Receita Federal's own service description draws the line explicitly: "Para brasileiros residentes no exterior, não é necessário comparecer à Repartição Consular" ("For Brazilians residing abroad, it is not necessary to attend the Consular Office") — self-enrollment online is reserved for Brazilian citizens abroad. For everyone else: "Para estrangeiros residentes no exterior, a solicitação deve ser feita presencialmente" ("For foreigners residing abroad, the application must be made in person").[6] A non-resident foreign individual must therefore apply in person at a Brazilian consulate — there is no self-service channel for that case. For the annual re-registration deadline that applies once a non-resident CPF is issued, see the Brazil Tax ID Guide.
Junta Comercial's decision clock
Brazil's "Lei da Liberdade Econômica" campaign page states the automatic-approval principle plainly: "O registro deve acontecer num prazo preestabelecido. Em caso de atraso, a concessão na junta comercial será automática" ("Registration must happen within a pre-established deadline. In case of delay, approval at the Junta Comercial becomes automatic").[7] The specific day-counts behind that principle — commonly described as 5 business days for filings requiring a collegiate decision and 2 business days for others, under Lei 8.934/1994 as amended by Lei 13.874/2019 — could not be independently fetched from the statutory text ; treat the numeric day-counts as reported rather than confirmed, while the automatic-approval principle itself is sourced directly to the gov.br campaign page above.
Fees at each rung
| Rung | Fee |
|---|---|
| Junta Comercial / Cartório de Registro Civil de Pessoas Jurídicas / OAB seccional | "Valor variável" — check your own state/DF[5] |
| CNPJ (Receita Federal) | No fee[5] |
| Inscrição Estadual (São Paulo) | "Não há taxa" — no fee[3] |
| Inscrição Municipal / CCM | Varies by municipality — not centrally published |
The MEI fast lane
MEI (Microempreendedor Individual) is a separate, faster registration lane through the Portal do Empreendedor, bypassing REDESIM's general flow. It has its own ceiling: annual gross revenue up to R$81,000, or up to R$251,600 for an autonomous freight carrier — "Ter um faturamento anual de até R$ 81.000,00 ou até R$ 251.600,00 para o transportador autônomo de cargas" ("Have an annual turnover of up to R$81,000.00, or up to R$251,600.00 for the autonomous freight carrier").[8] MEI registration is often described elsewhere as free and near-instant, but an official page stating that turnaround verbatim was not found — only the revenue ceiling above is confirmed against an official source; treat the speed and cost claim as unconfirmed until verified.
Simples Nacional election — and the 2026 window that moved
In a normal year, an existing business elects Simples Nacional in January, with the option taking retroactive effect from 1 January; a newly incorporated business formalizes its Simples Nacional intent at the moment of CNPJ registration through the Módulo de Administração Tributária (MAT). The specific fallback mechanism sometimes described alongside this — a further window of up to 30 days from the last registration deferral, provided no more than 60 days have passed since CNPJ opening — is reported via secondary sources rather than independently fetched from Receita Federal's own text ; confirm it directly before relying on exact day-counts.
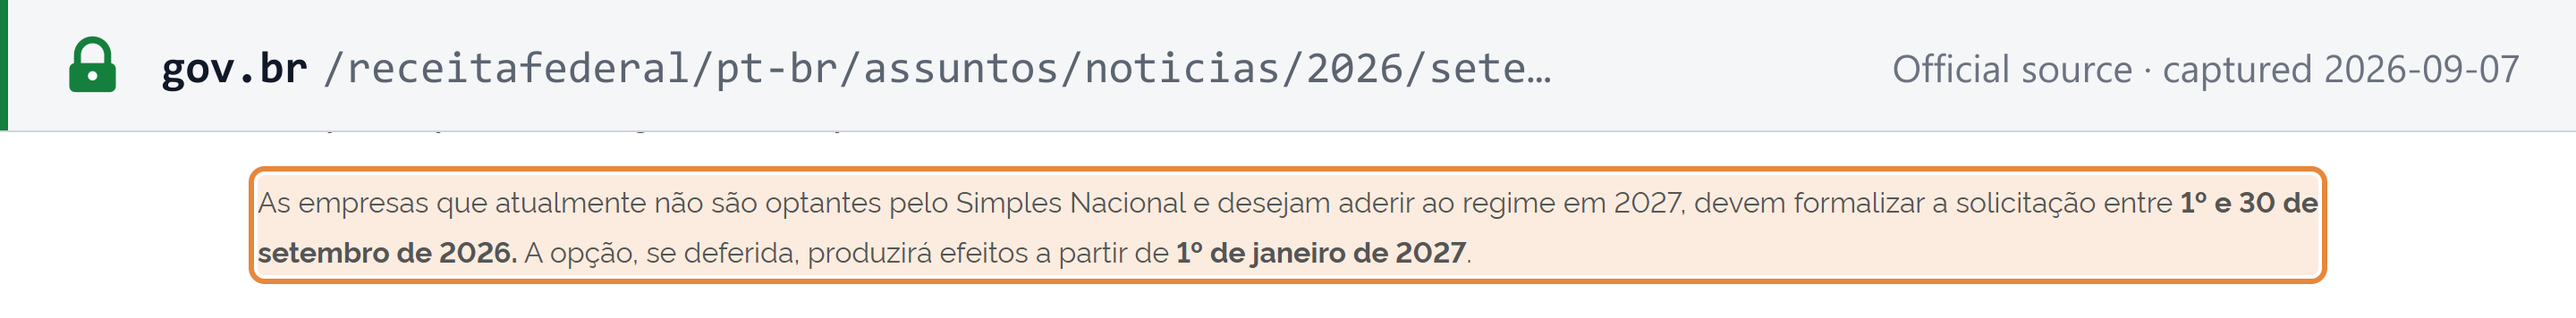
2026 is not a normal year for the 2027 tax year. Receita Federal announced that the election window itself moved out of January to 1–30 September 2026, and described this as a durable calendar change, not a one-off: "a solicitação para ingresso no Simples Nacional não será mais realizada no mês de janeiro" ("the request to join Simples Nacional will no longer be made in the month of January").[9] A business receiving its CNPJ between 1 October and 31 December 2026 gets a distinct carve-out: "a opção pelo Simples Nacional efetuada no momento da abertura da empresa produzirá efeitos tanto para o período remanescente de 2026 quanto para todo o ano de 2027" ("the Simples Nacional election made when the company opens will take effect both for the remainder of 2026 and for all of 2027").[10] Businesses that currently sit outside Simples Nacional and want to join for 2027 had to formalize that request in the same 1–30 September 2026 window: "As empresas que atualmente não são optantes pelo Simples Nacional e desejam aderir ao regime em 2027, devem formalizar a solicitação entre 1º e 30 de setembro de 2026" ("Companies not currently opting for Simples Nacional that wish to join the regime in 2027 must formalize the request between 1 and 30 September 2026").[10]
 Source snapshot captured 2026-09-07 — original
The general Simples Nacional gross-revenue ceiling is commonly cited as R$4,800,000/year under Lei Complementar 123/2006, and the existing R$3,600,000 ICMS/ISS sublimit is separately extended to also govern IBS collection from 1 January 2027 — that sublimit change is already fully sourced on the Brazil VAT (CBS/IBS) guidelines page; link there rather than re-deriving the figure. The R$4.8 million ceiling itself was corroborated via secondary sources but not independently fetched from LC 123/2006 or a Receita Federal manual, so treat it as reported pending direct verification.
Foreign digital platforms: registration, or withholding at the point of exchange
Brazil has no EU-style "non-resident VAT registration" or general fiscal-representative regime. The closest equivalent reported for the CBS/IBS reform is under LC 214/2025 articles 22–23: digital platforms — including those domiciled abroad — that intermediate CBS/IBS-taxable operations are said to face the same registration requirement as domestic operators, with joint or substitutive liability for the tax on those operations; where neither the foreign supplier nor the platform is registered, CBS/IBS is instead reported to be collected by withholding at the point of currency exchange, by the financial institution processing the remittance to the foreign supplier or platform. **This is reported by tax-advisory commentary and was not independently confirmed against the statutory text of LC 214/2025 ** — it is exactly the kind of claim worth getting right before relying on it, so treat it as unconfirmed and check the consolidated LC 214/2025 text (or Receita Federal's own legislação page for the reform) before acting on it.
After registration
e-CNPJ certificate and your first filings
Regularizing an existing CNPJ, filing declarations (DCTF, DIRF, SPED) and using the eCAC portal all require a digital certificate — an e-CNPJ for a legal entity, or an e-CPF for an individual. The How to verify a CNPJ number in Brazil guide covers how this certificate is used to regularize a CNPJ that has already fallen into "inapta" status; the same certificate is what a newly registered entity needs to file its first declarations and access eCAC.
Electronic fiscal documents
Once a CNPJ, and any Inscrição Estadual or Inscrição Municipal, are active, most operations must be documented on Brazil's standardized electronic fiscal documents — NF-e, NFC-e, NFS-e and others, depending on activity. This page does not restate that mandate or the CBS/IBS field-population dates layered onto it — see E-invoicing status and Invoice requirements on the country guide.
What changes under CBS/IBS
Two registration-adjacent changes from the consumption-tax reform are already fully sourced elsewhere and are only linked here: individuals who are CBS/IBS taxpayers must register for a CNPJ from 1 January 2027, postponed from 1 July 2026 by Decreto nº 13.075/2026 — see CNPJ and registration; and the existing R$3.6 million Simples Nacional sublimit is extended to also govern IBS collection from the same date — see Registration thresholds. Neither changes the registration ladder described on this page — they change who must climb it and what a Simples Nacional company collects above the sublimit.
Penalties for late registration
Receita Federal's CNPJ guidance does not itself prescribe a specific monetary fine for late or missing initial registration — general instrumental-obligation penalty provisions are said to apply instead, per secondary legal commentary not independently verified with a specific article or figure. The concrete, sourced consequence is operational, not monetary: without an active CNPJ, a business cannot open a bank account, issue an NF-e, or contract with most counterparties. Separately, for a CNPJ that already exists but goes 90 or more days without filing mandatory declarations, Receita Federal declares it "inapta," which blocks invoicing entirely — that mechanism, and how to check for and clear it, is fully covered on How to verify a CNPJ number in Brazil.
Frequently asked questions
Is there a revenue threshold before I must register for a CNPJ in Brazil?
No. Ordinary CNPJ registration is defined by Chapter II (articles 3-4) of Instrução Normativa RFB 2.119/2022 according to who the entity IS — a legal entity carrying on an activity — not by a turnover test. There is no minimum-revenue floor to cross first. From 1 January 2027, the obligation extends to individuals who are CBS and/or IBS taxpayers, postponed from an original 1 July 2026 start date by Decreto nº 13.075/2026. (gov.br/receitafederal)
Is REDESIM a single portal that completes CNPJ, ICMS and ISS registration in one pass?
Only partly. REDESIM is the shared front door across Juntas Comerciais, DREI, Receita Federal, the states and the municipalities, and it is where the Inscrição Estadual request is submitted. But São Paulo's own tax authority states that the request is then reviewed by the competent SEFAZ unit, which can require further documents before granting it — Inscrição Estadual is not an automatic REDESIM output. Municipal Inscrição Municipal/CCM integration with REDESIM also varies by city. (portal.fazenda.sp.gov.br)
I am a foreigner living outside Brazil. Can I apply for a CPF online?
No. Receita Federal's own service description distinguishes the two cases explicitly: Brazilian citizens living abroad do not need to visit a consular office and can self-enroll online, but foreign nationals residing outside Brazil must apply in person at a Brazilian consulate. There is no online self-service route for a first-time CPF for a non-resident foreigner. (gov.br/pt-br/servicos/inscrever-no-cpf-no-exterior)
How long does CNPJ registration take, and what does it cost?
Receita Federal's own service page states an average processing time of about 24 hours for the CNPJ leg, with no fee charged by Receita Federal itself. Junta Comercial, Cartório and OAB seccional fees for the constitutive-act leg are described as "valor variável" and differ by state — check your own state's Junta Comercial. São Paulo's SEFAZ separately confirms no fee for Inscrição Estadual. Total time-to-CNPJ depends more on how quickly the constitutive act clears the Junta Comercial than on the federal step itself. (gov.br/pt-br/servicos/inscrever-no-cnpj; portal.fazenda.sp.gov.br)
What happens if my business misses the 1-30 September 2026 Simples Nacional election window?
For 2027 effect, Receita Federal moved the annual election window out of January to 1-30 September 2026, described as a durable calendar change rather than a one-off. A business opening its CNPJ between 1 October and 31 December 2026 gets a separate carve-out: the Simples election made at CNPJ opening covers both the remainder of 2026 and all of 2027. Outside that window and carve-out, the ordinary-year fallback rule (commonly described as 30 days from the last registration deferral, within 60 days of CNPJ opening, else January of the following year) is corroborated via secondary sources rather than independently confirmed against the statute — verify it directly for your own state before relying on exact day-counts. (gov.br/receitafederal)
Does a foreign company need a local fiscal representative to register or sell in Brazil?
Brazil has no EU-style fiscal-representative regime for VAT, but two separate rules apply. A foreign entity that becomes a partner in, or directly registers, a Brazilian legal entity must appoint a Brazil-resident procurador holding a CPF, under article 6 of Instrução Normativa RFB 2.119/2022. Separately, digital platforms domiciled abroad that intermediate CBS/IBS-taxable operations are reported to face the same registration duty as domestic operators under LC 214/2025 articles 22-23, with currency-exchange withholding as a fallback where neither the foreign supplier nor the platform is registered — this second rule is reported by tax advisories and has not been independently confirmed against the statutory text, so treat it as unconfirmed pending verification. (gov.br/receitafederal; Brazil Tax ID Guide)
What penalty applies if I operate a business in Brazil without registering for CNPJ?
Receita Federal's CNPJ guidance does not publish a specific monetary fine for late or missing initial registration itself — only for ancillary-obligation failures used later to declare an already-registered CNPJ "inapta". The real, sourced consequence is operational: without an active CNPJ, a business cannot open a bank account, issue an NF-e, or contract with most counterparties. A CNPJ that already exists but goes unfiled for two or more consecutive years is separately declared inapta, which blocks invoicing entirely. (gov.br/receitafederal)
Related resources
- Brazil VAT (CBS/IBS) guidelines — tax rates, the CBS/IBS transition timeline, invoice requirements and e-invoicing status
- Brazil Tax ID Guide — CPF and CNPJ formats, checksums, the July 2026 alphanumeric CNPJ change and the foreign-procurador rule
- How to verify a CNPJ number in Brazil — REDESIM lookup, status values (Ativa/Suspensa/Inapta/Baixada) and how to clear an Inapta status
- How to verify a CPF number in Brazil — CPF status lookup
- Brazil tax changes chronology — the running list of 2026 CBS/IBS registration and threshold changes
Official sources
- Quem está obrigado a se inscrever no CNPJ — Receita Federal do Brasil
- Inscrever no CNPJ (service page, six-stage process map) — Portal gov.br
- Abertura de Empresas e Inscrição Estadual — Secretaria da Fazenda de São Paulo
- Quero registrar minha empresa — DREI
- Inscrever no CPF no exterior — Receita Federal do Brasil
- O que muda com a Lei de Liberdade Econômica — Portal gov.br
- Qual o faturamento anual do MEI — Portal gov.br
- Prazo para solicitação pelo Simples Nacional será em setembro de 2026 — Receita Federal do Brasil
- Receita Federal alerta: começa hoje o prazo para opção pelo Simples Nacional... — Receita Federal do Brasil
- REDESIM — Registro de empresas — Portal gov.br
How Lookuptax can help you?
Lookuptax VAT validation revolutionizes VAT number validation with its robust platform, empowering businesses to seamlessly verify VAT numbers across over 100 countries. Our cutting-edge technology ensures accurate and efficient validation, reducing errors and enhancing compliance.