China VAT guidelines
| FACTSHEET | |
|---|---|
| Country code | CN |
| Tax name | Value Added Tax (VAT) — 增值税 (zēngzhíshuì) |
| Tax Authority | State Taxation Administration (STA) — 国家税务总局; import VAT collected by the General Administration of Customs |
Overview
Mainland China levies Value Added Tax (VAT) — Chinese: 增值税 — under the VAT Law of the People's Republic of China (中华人民共和国增值税法), adopted by the Standing Committee of the National People's Congress on 25 December 2024 and in force since 1 January 2026, when it replaced the Provisional Regulations on VAT (Article 38). [1] The State Council's Implementing Regulations of the VAT Law (State Council Decree No. 826, dated 25 December 2025) took effect on the same date. [2]
VAT is collected by the State Taxation Administration (STA) and its provincial tax services; import VAT is collected by customs on the STA's behalf (VAT Law, Article 32). [1] It is a single national tax with no provincial or municipal VAT layer, although where a domestic unit withholds VAT on payments to individuals under the Announcement No. 28 of 2026 Measures, it withholds the applicable surcharges together with VAT (see Recent changes). [11]
VAT is charged on top of the price: the sales amount excludes VAT, and the VAT amount must be shown separately on the transaction document (Article 7). Sales are computed in renminbi (RMB); amounts settled in foreign currency are converted to RMB (Article 18). [1] Tax periods are set per taxpayer, from 10 days up to a quarter — see Filing and payment.
Scope. This guide covers mainland China only. Hong Kong and Macao are separate tax jurisdictions and are not covered by the VAT Law.
The 2026 transition is being filled in by a series of MOF/STA announcements — No. 10 of 2026 (carrying over exemptions and concessions), No. 25 of 2026 (non-taxable transactions and input-tax deduction), No. 28 of 2026 (VAT withholding on payments to individuals) — and by export-refund changes such as No. 2 of 2026 for batteries. See Recent changes. For the weekly roundup across jurisdictions, see Last Week in Taxes.
Registration
Who is a taxpayer. Units and individuals (including individual businesses) that sell goods, services, intangible assets or immovable property within China, or import goods, are VAT taxpayers (VAT Law, Article 3). [1]
Two classes of taxpayer. China does not use a registration threshold in the EU sense. Every business taxpayer is in the VAT system; the threshold decides which class it belongs to:
- A small-scale taxpayer (小规模纳税人) is a taxpayer whose annual sales subject to VAT do not exceed RMB 5 million (VAT Law, Article 9). It can use the simplified method: sales multiplied by the levy rate, with no input-tax credit (Article 8). [1]
- A general taxpayer (一般纳税人) uses the general method: output tax minus input tax. General taxpayers are subject to a registration system (Implementing Regulations, Article 6). [2]
Threshold. A unit or individual business whose annual taxable sales exceed RMB 5 million must register with its competent tax authority as a general taxpayer, and uses the general method from the period in which it exceeded the line (Implementing Regulations, Article 36). The State Council may adjust the RMB 5 million line and must report the change to the NPC Standing Committee (VAT Law, Article 9). [1] [2]
Voluntary registration. A small-scale taxpayer with sound accounting that can provide accurate tax information may register as a general taxpayer (VAT Law, Article 9). Businesses usually do this so that they can deduct input VAT and issue special VAT fapiao, which their customers can use for input-tax credit. Once registered as a general taxpayer, a business cannot convert back to small-scale status (Implementing Regulations, Article 36). Natural persons are always small-scale taxpayers (Article 7). [1] [2]
Non-resident threshold. Not applicable. The VAT Law has no registration regime for foreign sellers. Where a foreign unit or individual makes a taxable transaction within China, the purchaser withholds the VAT, unless the foreign seller appoints a domestic agent to declare and pay under State Council rules (Article 15). See Cross-border rules. [1]
Tax registration number. Legal persons and other organisations are identified by the 18-character Unified Social Credit Code (USCC, 统一社会信用代码). Under the State Council's 2015 master plan (国发〔2015〕33号), the code has five parts: a 1-character registration-authority code, a 1-character entity-type code, a 6-digit administrative-division code, a 9-character entity identifier (the former organisation code) and a 1-character check code. [7] The tax authorities accept the USCC in the buyer's "taxpayer identification number" field on a fapiao: since 1 July 2017, an enterprise buyer must give the seller its taxpayer identification number or USCC, and the seller must print it on the ordinary VAT fapiao (STA Announcement No. 16 of 2017). [8] For the full format, the check-character algorithm and individual identifiers, see the China TIN guide. To check a counterparty's code, use the China USCI validator.
How to register. A taxpayer engaged in production or business must apply for tax registration within 30 days of receiving its business licence (Tax Collection and Administration Law, Article 15). [6] General-taxpayer registration is filed with the competent tax authority under procedures set by the STA (Implementing Regulations, Article 6). [2]
Deregistration. A taxpayer must apply to cancel its tax registration before it applies to the market-regulation authority to cancel its business registration, and must report changes in registered details within 30 days (Tax Collection and Administration Law, Article 16). There is no route from general-taxpayer back to small-scale status (see above). [6]
Group registration. Not available in the sense of grouping separate legal entities. The nearest provision is consolidated filing by a head office: where a head office and its branches are in different counties or cities, each files locally unless the finance and tax authorities at provincial level or above approve consolidated filing by the head office (VAT Law, Article 29(1)). Approval comes from the MOF and STA for branches in other provinces, and from the provincial authorities for branches within the same province (Implementing Regulations, Article 42). [1] [2]
Rates
Rates under Article 10 of the VAT Law, in force since 1 January 2026: [1]
| Rate | Applies to |
|---|---|
| 13% (standard) | Sales of goods; processing, repair and replacement services; tangible movable property leasing; imports of goods — unless a 9% or 0% item below applies. |
| 9% | Transport, postal, basic telecommunications, construction and immovable-property leasing services; sales of immovable property; transfers of land-use rights; and sales or imports of: agricultural products, edible vegetable oil, edible salt; tap water, heating, cooling, hot water, coal gas, LPG, natural gas, dimethyl ether, biogas, household coal products; books, newspapers, magazines, audio-visual products, electronic publications; feed, chemical fertiliser, pesticides, agricultural machinery and agricultural film. |
| 6% | Other services and intangible assets not at 13%, 9% or 0% — for example financial, IT, consulting and other modern services. |
| 0% | Exported goods, unless the State Council provides otherwise; cross-border sales of services and intangible assets within the State Council's scope. |
Zero-rated cross-border services. The Implementing Regulations list them (Article 9): R&D, energy-performance contracting, design, broadcast/film/TV production and distribution, software, circuit design and testing, information-system, business-process-management and offshore outsourcing services sold to foreign units and consumed entirely outside China; technology transferred to foreign units for use entirely outside China; and international transport, space transport and outbound repair services. [2]
Levy rates under the simplified method. The statutory levy rate is 3% (VAT Law, Article 11). [1] MOF/STA Announcement No. 10 of 2026 carries over the earlier concessions: [3]
- from 1 January 2026 to 31 December 2027, small-scale taxpayers pay a reduced 1% on all taxable transactions except selling or leasing immovable property and transferring land-use rights;
- from 1 January 2026 to 31 December 2027, general taxpayers may elect the simplified method at 3% for listed transactions, or at 5% for listed immovable-property transactions (such as property acquired before 30 April 2016 and old real-estate development projects);
- a 3%-reduced-to-2% treatment for sales of used fixed assets and second-hand goods, and 3%-reduced-to-1.5% for individuals leasing housing.
Once a general taxpayer elects the simplified method, it cannot change for 36 months (Announcement No. 10 of 2026). [3]
Mixed transactions. A taxpayer making supplies at different rates must account for them separately or the highest rate applies (Article 12). A single transaction with a principal and an ancillary element takes the rate of the principal element (Article 13; Implementing Regulations, Article 10). [1] [2]
Announced changes. No change to the 13%, 9% or 6% rates had been published as of 2026-10-05. The 1% small-scale concession and the RMB 100,000 monthly exemption threshold both run until 31 December 2027 under Announcement No. 10 of 2026.
Cross-border rules
Imports. Imported goods are taxed at the applicable rate on the composite taxable price: the customs value plus customs duty and consumption tax (VAT Law, Article 14). The tax point is the date of the import declaration (Article 28), and the VAT is collected by customs within customs time limits (Articles 30 and 32). [1] A general taxpayer deducts import VAT using the customs import VAT special payment certificate (Implementing Regulations, Articles 11–12). [2]
Cross-border e-commerce retail imports. Goods bought by consumers through cross-border e-commerce retail channels are subject to a single-transaction limit of RMB 5,000 and an annual limit of RMB 26,000 per person. A single-item order above RMB 5,000 but within the annual limit may still use the channel, but duty and import VAT and consumption tax are then charged in full at the rates for goods (财关税〔2018〕49号, from 1 January 2019). [12]
Exports. Exported goods are zero-rated. "Exported goods" means goods declared to customs that actually leave China and are sold to a foreign unit or individual (Implementing Regulations, Article 8). [2] An exporter claims refund or exemption from its competent tax authority (VAT Law, Article 33) under one of two methods (Implementing Regulations, Article 47). [1] [2]
- Exemption-credit-refund (免抵退): exempt at export; the related input tax is offset against VAT payable and any balance is refunded.
- Exemption-refund (免退): exempt at export; the related input tax is refunded.
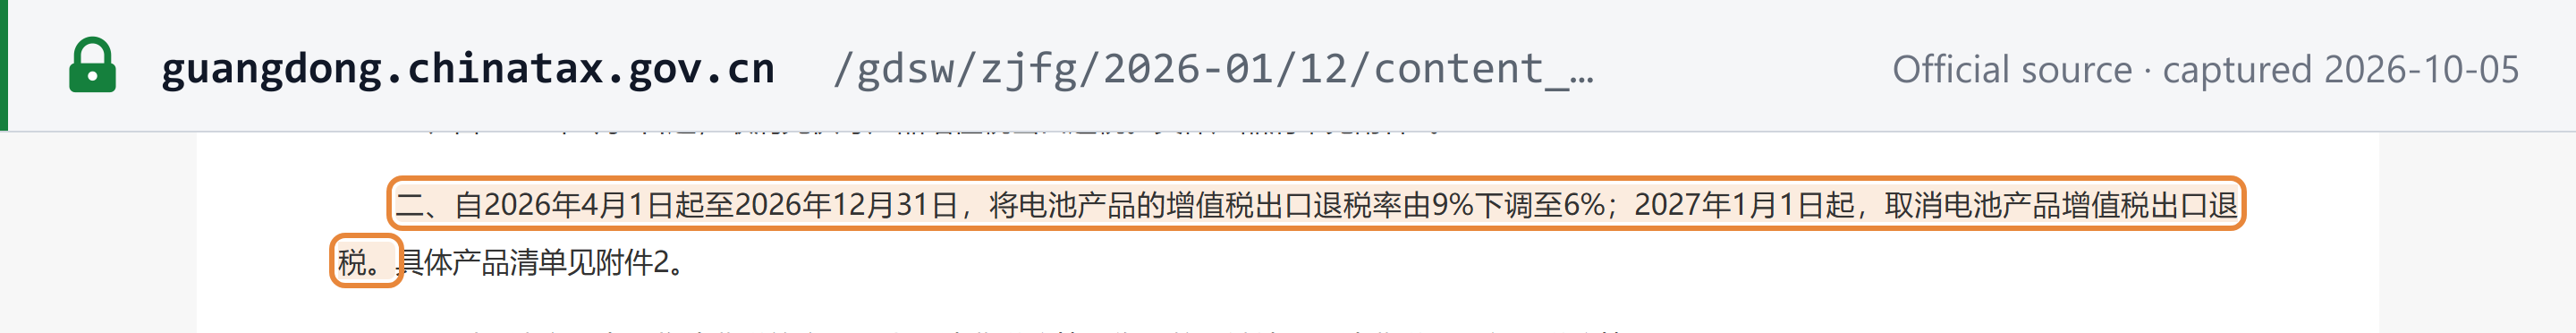
Refunds are computed at the export refund rate set by the State Council, which can be lower than the domestic rate or nil for particular products. MOF/STA Announcement No. 2 of 2026 cancelled the export VAT refund on photovoltaic and similar products from 1 April 2026. It cut the refund rate on battery products from 9% to 6% for 1 April to 31 December 2026, and cancels it entirely from 1 January 2027. The applicable rate is set by the export date on the customs declaration. See event record. [10]
An exporter that misses the claim deadline must pay VAT as if the goods had been sold domestically (Implementing Regulations, Article 48). An exporter that waives refund or exemption cannot return to it for 36 months (Article 49). [2]
Place of supply. Under VAT Law Article 4, a taxable transaction takes place within China where: [1]
- goods: the place of dispatch or location of the goods is in China;
- immovable property and natural-resource rights: the property or resource is in China;
- financial products: the product is issued in China, or the seller is a Chinese unit or individual;
- other services and intangible assets: they are consumed in China, or the seller is a Chinese unit or individual.
A service or intangible asset is "consumed in China" where a foreign seller sells it to a Chinese unit or individual (except services consumed on site outside China), or where it is directly related to goods, immovable property or natural resources in China (Implementing Regulations, Article 4). [2]
Foreign companies selling in — B2B and B2C.
- B2B: the Chinese purchaser is the withholding agent. It withholds VAT at the sales amount multiplied by the rate, unless the foreign seller has appointed a domestic agent to declare and pay (VAT Law, Article 15). The withholding obligation arises on the same day as the seller's tax point (Article 28), and the agent files where it is established (Article 29(5)). [1] A general-taxpayer purchaser deducts the VAT shown on the tax payment certificate it obtains (Implementing Regulations, Article 12(3)). [2]
- B2C: Article 15 applies the same purchaser-withholding rule whatever the type of purchaser, and neither the VAT Law nor the Implementing Regulations contains a separate registration or one-stop-shop regime for foreign sellers to consumers. One special case: where a foreign unit or individual leases immovable property in China to a natural person and has a domestic agent, the agent declares and pays the tax (Implementing Regulations, Article 35). No STA rule setting out how a foreign B2C digital seller accounts for VAT in practice has been published as of 5 October 2026. [2]
Digital products and services. There is no separate digital-services regime. Electronic and online services are taxed as services (generally at 6%), and the place-of-supply test in Article 4 applies. [1]
Marketplace / platform deemed-supplier liability. Not applicable. The VAT Law and the Implementing Regulations contain no rule that makes a platform the deemed supplier. The withholding Measures under Announcement No. 28 of 2026 exclude individuals working through internet platforms where the platform files VAT for them under the platform filing rules (Measures, Article 14). That is a filing arrangement, not deemed-supplier liability. [11]
Invoice requirements
China's invoice is the fapiao (发票), governed by the Fapiao Administrative Measures (中华人民共和国发票管理办法, revised by State Council Decree No. 764, effective 20 July 2023). [5] The VAT Law requires taxpayers to issue and use VAT fapiao lawfully. VAT fapiao may be paper or electronic, and electronic fapiao have the same legal effect as paper (Article 34). [1]
Document types
- Special VAT fapiao (增值税专用发票). It shows the sales amount and the VAT amount separately (Implementing Regulations, Article 5), and it is the main voucher that lets a general-taxpayer buyer deduct input tax (Articles 11–12). It must not be issued where the buyer is a natural person or the transaction is VAT-exempt (Article 37). [2]
- Ordinary VAT fapiao (增值税普通发票). It is issued where a special fapiao is not needed or not allowed. Where the buyer is an enterprise, the seller must print the buyer's taxpayer identification number or USCC on it, or the fapiao cannot be used as a tax voucher (STA Announcement No. 16 of 2017). [8]
- Other deduction vouchers: the customs import VAT special payment certificate, tax payment certificates for VAT withheld on purchases from abroad, and agricultural-product purchase and sales fapiao (Implementing Regulations, Article 11). [2]
China has no value-based "simplified invoice" tier. The split is special against ordinary fapiao, by buyer and use.
Mandatory content
The STA lists the basic face elements of the fully digitalised e-fapiao (STA Announcement No. 11 of 2024, item 3): [4]
| Field | Notes |
|---|---|
| Fapiao name | E.g. "电子发票(增值税专用发票)" or "电子发票(普通发票)". |
| Fapiao number | 20 digits, assigned nationally (see below). |
| Issue date | |
| Buyer information | Name and taxpayer identification number / USCC. Mandatory for enterprise buyers, per STA Announcement No. 16 of 2017. |
| Seller information | Name and taxpayer identification number / USCC. |
| Item name, specification/model, unit, quantity, unit price, amount | Line-item detail. |
| Tax rate / levy rate, tax amount | The VAT must be shown separately (VAT Law, Article 7; Implementing Regulations, Article 5). |
| Total, and total including tax | |
| Remarks | Required content for specific businesses, such as construction or refined oil, is generated from business tags. |
| Issuer | The person who issued the fapiao. Issuing requires real-name identity verification (item 7). |
Discounts. A discount reduces the sales amount only if the price and the discount are shown separately in the "amount" column of the same fapiao; otherwise VAT is charged on the undiscounted price (Announcement No. 25 of 2026, item 10). [9]
Issuance deadline and numbering
The party that receives payment must issue a fapiao to the party that pays (Fapiao Administrative Measures, Article 18). A fapiao must be issued within the prescribed time, in sequence and with all fields completed truthfully at one time (Article 21). [5] Issuing a fapiao also fixes the VAT tax point: the tax point is the date payment is received or the right to payment arises, or the date the fapiao is issued if that is earlier (VAT Law, Article 28). [1]
The e-fapiao number has 20 digits: [4]
- digits 1–2: the last two digits of the year;
- digits 3–4: the issuer's provincial tax-bureau region code;
- digit 5: the issuing channel;
- digits 6–20: a sequential number.
Credit and debit notes
Corrections are made with a red-letter fapiao (红字发票). A red-letter e-fapiao is issued after returns, issuing errors, suspended services or sales allowances (STA Announcement No. 11 of 2024, item 8). [4]
- If the buyer has not yet confirmed the fapiao's use or booked it, the issuer issues the red-letter e-fapiao directly.
- Once the buyer has confirmed or booked it, either party starts the process. The other party must confirm a Red-Letter Fapiao Information Confirmation Form within 72 hours or the form lapses.
- A buyer that has already deducted the input tax must reverse it on the strength of the form.
A seller that does not void the fapiao or issue the red-letter special fapiao as required cannot reduce its output tax or sales amount (Implementing Regulations, Article 38). [2]
Currency and language
Sales are computed in RMB (VAT Law, Article 18). For foreign-currency sales, the taxpayer may convert at the RMB central parity rate on the day of the sale or the first day of the month, and must keep the chosen method for 12 months (Implementing Regulations, Article 17). [1] [2] This guide did not find a statutory language rule beyond the Chinese-language fapiao forms set by the STA.
Self-billing
The Fapiao Administrative Measures allow the payer to issue the fapiao to the payee "in special circumstances" (Article 18). [5] Agricultural-product purchase fapiao and scrap-product purchase fapiao are issued by the buyer, and are named in the e-fapiao rules (STA Announcement No. 11 of 2024, item 8). [4]
Retention and audit trail
- Fapiao stubs of issued fapiao must be kept for 5 years (Fapiao Administrative Measures, Article 28). [5]
- Accounting records are kept for either permanently or for minimum periods of 10 or 30 years, depending on the record type, under the Accounting Archives Management Measures (MOF/National Archives Administration Order No. 79, Article 14). Electronic records that meet the Measures' conditions may be kept in electronic form only (Articles 8–9). [13]
- Audit trail. Each e-fapiao is single-copy and exists only in digital form. If it is delivered by download or print, it is automatically marked with its download and print counts (STA Announcement No. 11 of 2024, items 2 and 9). Every e-fapiao can be checked free of charge on the national fapiao verification platform (item 11). [4]
What a compliant invoice looks like
The STA published fapiao styles as Attachment 1 to Announcement No. 11 of 2024. [4] The illustration below places the item-3 face elements in a typical layout.
电子发票(增值税专用发票) — fully digitalised e-fapiao, special VAT fapiao
| Item nameitem 3 | Spec / modelitem 3 | Unititem 3 | Qtyitem 3 | Unit priceitem 3 | Amountitem 3 | RateVAT Law art. 10 | TaxImpl. Regs art. 5 |
|---|---|---|---|---|---|---|---|
| *Consulting services* Market-entry advisory (fictional) | — | item | 1 | 10,000.00 | 10,000.00 | 6% | 600.00 |
- Total (合计) — amount / taxAnn. 11/2024 item 3
- RMB 10,000.00 / RMB 600.00
- Total including tax (价税合计)Ann. 11/2024 item 3
- RMB 10,600.00
- Remarks (备注): free text, plus mandatory content for special businesses (construction, refined oil, scrap purchase …) generated from business tags — Ann. 11/2024 item 2.
- Issuer (开票人): the identity-verified person who issued the fapiao — Ann. 11/2024 items 3 and 7.
- A special VAT fapiao may not be issued to a natural person or for an exempt supply; an ordinary fapiao (电子发票(普通发票)) is used instead — Implementing Regulations art. 37.
- If downloaded or printed, the platform stamps the download and print counts on the face — Ann. 11/2024 item 9.
E-invoicing status
Status (as of 2026-10-05): fully digitalised e-fapiao rolled out nationwide. The STA introduced the fully digitalised electronic fapiao (全面数字化的电子发票, "数电发票") nationwide from 1 December 2024 (STA Announcement No. 11 of 2024). Pilots had started in Guangdong, Shanghai and Inner Mongolia on 1 December 2021 and spread across the country. [4]
- System. The fully digitalised e-fapiao is a type of "electronic fapiao" under the Fapiao Administrative Measures. Its face elements are fully digitised, its number is assigned nationally, and its issuing quota is granted by the tax authority. The quota caps the total pre-tax amount a taxpayer may invoice in a calendar month and is adjusted to the taxpayer's risk, credit rating and business. Fapiao data flows between the parties automatically through tax digital accounts (items 1 and 6). [4]
- Network. The tax authorities run a national unified electronic fapiao service platform that issues and receives e-fapiao free of charge. Issued fapiao are delivered automatically through the platform, and can also be sent by email, QR code or download (items 5 and 9). [4]
- Buyer side. A buyer that wants to deduct input VAT or claim an export refund must confirm the fapiao's use in its tax digital account (item 10). [4]
- Format. Fapiao categories include e-fapiao (special VAT fapiao), e-fapiao (ordinary fapiao), and e-fapiao for air and rail tickets and motor-vehicle and used-car sales (item 2). No UBL or Peppol-style exchange schema has been published by the STA as of 5 October 2026. Issuance runs through the STA platform rather than an interoperable network. [4]
- Paper. Paper fapiao still exist in law. The VAT Law says VAT fapiao "include paper fapiao and electronic fapiao" with equal legal effect, and that the State actively promotes electronic fapiao (Article 34). Announcement No. 11 of 2024 sets no date for abolishing paper fapiao. [1]
Scope. The e-fapiao applies to fapiao issued by any taxpayer, B2B and B2C alike. The buyer's identifier is mandatory only for enterprise buyers. No separate B2G e-invoicing rule has been published by the STA as of 5 October 2026.
Filing and payment
Filing frequency. The competent tax authority sets each taxpayer's tax period — 10 days, 15 days, one month or one quarter — according to the amount of tax payable. Taxpayers that only occasionally make taxable transactions may pay per transaction (VAT Law, Article 30). [1] The following may use a quarterly period (Implementing Regulations, Article 43): [2]
- small-scale taxpayers;
- banks, finance companies, trust companies and credit cooperatives among general taxpayers;
- other taxpayers named by the STA and MOF.
Return and payment due dates. These follow Articles 30–31 of the VAT Law. [1]
- Monthly or quarterly period: file and pay within 15 days after the period ends.
- 10- or 15-day period: prepay within 5 days after each period ends, and file within 15 days from the first day of the following month.
- Imports: per customs time limits.
- Withholding agents: the same rules apply when they remit withheld tax.
A taxpayer that pays per transaction must file by 30 June of the following year once its sales reach the threshold (Implementing Regulations, Article 44). [2]
Small-scale exemption threshold. From 1 January 2026 to 31 December 2027, a small-scale taxpayer whose sales are below the threshold is exempt. At or above it, VAT is due on the full amount (VAT Law, Article 23). The threshold is: [3] [1]
- RMB 100,000 a month for a monthly period;
- RMB 300,000 a quarter for a quarterly period;
- RMB 1,000 per transaction (or per day) for per-transaction taxpayers (Announcement No. 10 of 2026, item 1).
Prepayments. Prepayment is required for certain transactions (Implementing Regulations, Article 45): [2]
- construction services across prefecture-level areas, or paid for in advance;
- pre-sales of real estate;
- transfers or leases of immovable property outside the taxpayer's county;
- certain cross-provincial oil and gas services.
Input-tax recovery. Input tax is deducted only against a valid deduction voucher: special VAT fapiao, customs import VAT special payment certificates, tax payment certificates, or agricultural-product purchase and sales fapiao (VAT Law, Article 16; Implementing Regulations, Articles 11–12). [1] [2]
Blocked items. Input tax is not deductible on (VAT Law, Article 22): [1] [2]
- simplified-method projects and exempt projects;
- abnormal losses (theft, loss or spoilage through poor management; confiscation for breach of law);
- purchases for collective welfare or personal consumption, which include business entertainment (Implementing Regulations, Article 20);
- catering, residents' daily services and entertainment services consumed directly;
- interest on loans and directly related advisory, handling and consulting fees, which are not deductible "for the time being" (Implementing Regulations, Article 21);
- purchases used for non-taxable transactions that bring economic benefit outside Articles 3–6 of the VAT Law (Implementing Regulations, Article 22).
Mixed-use long-term assets with an original value up to RMB 5 million are fully deductible. Above that, the input tax is deducted in full on purchase and then adjusted year by year (Implementing Regulations, Article 25). [2]
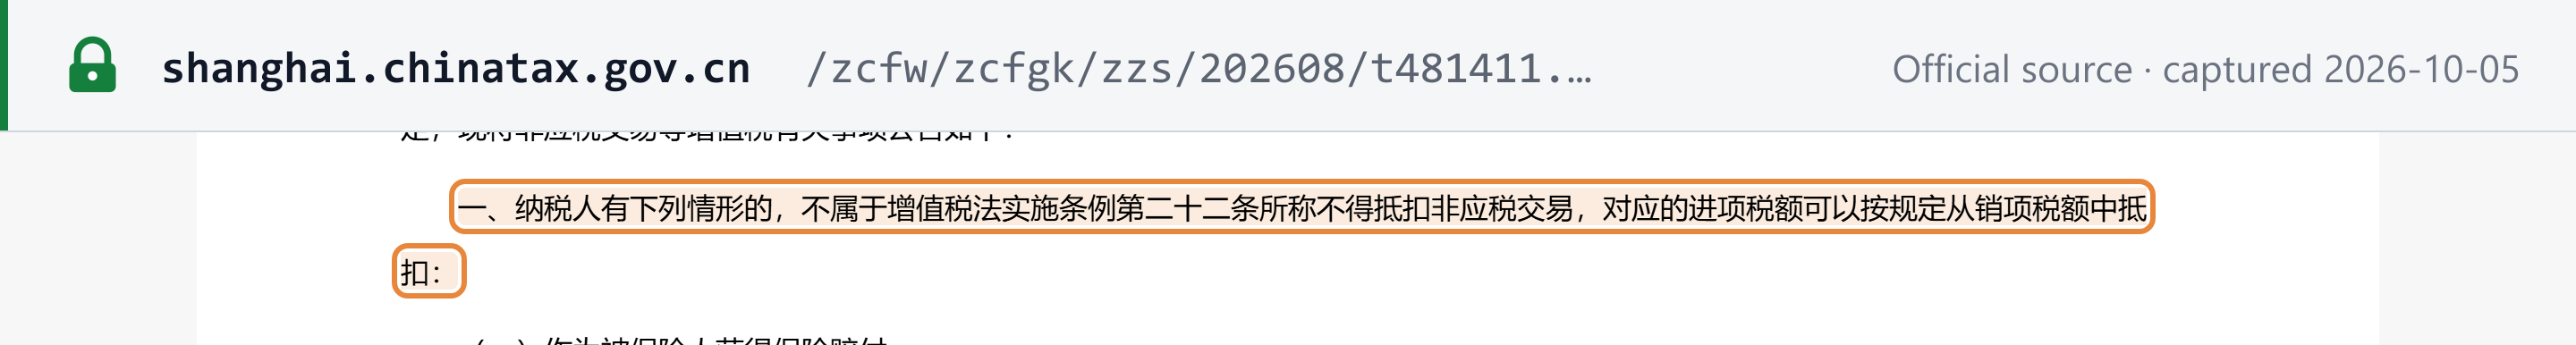
Non-taxable transactions (Announcement No. 25 of 2026). In force from 1 September 2026, MOF/STA Announcement No. 25 of 2026 defines which items fall into the Article 22 block, and also applies to matters from 1 January to 31 August 2026 that had not yet been dealt with. [9]
- Not blocked — related input tax stays deductible: insurance compensation received as the insured; cash or in-kind donations received; liquidated damages where the contract was not performed and no taxable transaction occurred; free services (other than free transfers of financial products); assignment of receivables arising from the taxpayer's own taxable transactions (other than securities); and fiscal subsidies not directly linked to sales income or volume.
- Blocked: sales outside the Article 4 domestic-taxable scope; transfers of equity for consideration (other than securities); dividends from equity and from ordinary shares; and commodity-futures trading (other than physical delivery).
See event record.
Refunds and carry-forward. Where input tax exceeds output tax, the taxpayer may carry the excess forward or apply for a refund, under State Council rules (VAT Law, Article 21). [1] Export refunds are covered under Cross-border rules. Neither the VAT Law nor the Implementing Regulations contains a general bad-debt relief provision. Returns, allowances and cancellations are dealt with through red-letter fapiao (Implementing Regulations, Articles 13–14 and 38). [2]
Exemptions
Statutory exemptions are listed in VAT Law Article 24: [1]
- agricultural producers' sales of their own agricultural products, and related agricultural services;
- medical services by medical institutions (excluding for-profit cosmetic medical institutions, per Implementing Regulations Article 27);
- antique and second-hand books, and individuals' sales of their own used goods;
- imported instruments used directly for scientific research, experiments and teaching;
- imported aid materials donated by foreign governments and international organisations;
- articles imported by organisations of disabled persons for disabled persons' use, and services provided by disabled individuals;
- childcare, kindergarten, elderly-care and disability-service institutions' care services, marriage-introduction services and funeral services;
- schools' accredited (学历) education services and students' work-study services;
- first-gate admission income of memorial halls, museums, cultural centres, galleries, libraries and similar venues, and of religious sites.
MOF/STA Announcement No. 10 of 2026 carries over a much longer list of concession-based exemptions. Some apply from 1 January 2026 with no end date; others run to 31 December 2027. [3]
Exempt is not zero-rated. Input tax attributable to exempt items is not deductible (VAT Law, Article 22(2)). Zero-rated exports and cross-border services remain eligible for refund or exemption of the related input tax (Article 33; Implementing Regulations, Article 47). [1] [2]
Waiving an exemption. A taxpayer may waive a VAT concession, for example so that it can issue special fapiao and recover input tax. After waiving, it cannot use the same concession for 36 months; small-scale taxpayers are exempt from this lock-in (VAT Law, Article 27). A general taxpayer files a written waiver statement with its tax authority (Announcement No. 25 of 2026, item 8). [1] [9] A taxpayer with both exempt and taxable business must account for the exempt sales separately, or it loses the exemption (Article 26). [1]
Special regimes.
- The small-scale taxpayer simplified method with its 3% and 1% levy rates (see Rates).
- The simplified-method elections for general taxpayers under Announcement No. 10 of 2026.
- Consolidated head-office filing (see Registration).
- The State Council may adopt targeted VAT concessions for small and micro enterprises, key industries, innovation and employment, and charitable donations, and must report them to the NPC Standing Committee (VAT Law, Article 25). [1]
Offences and penalties
The VAT Law sends liability to the Tax Collection and Administration Law and related laws (Article 37). [1]
Offences (the misconduct):
- Tax evasion (偷税): forging, altering, hiding or destroying books or vouchers; overstating expenses or understating income; refusing to file after notice; or filing a false return, resulting in unpaid or underpaid tax (Tax Collection and Administration Law, Article 63). Criminal liability applies where the conduct is a crime. [6]
- False invoicing (虚开发票): issuing, or arranging for someone to issue, a fapiao that does not match the actual business, for oneself or for others (Fapiao Administrative Measures, Article 21). Criminal liability applies where the conduct is a crime (Article 35). [5]
- Failure to issue a fapiao when required, or issuing it outside the prescribed time, sequence or fields (Fapiao Administrative Measures, Article 33(1)). [5]
- Failure to register, change or cancel tax registration on time (Tax Collection and Administration Law, Article 60). [6]
- Arrangements without a reasonable commercial purpose that reduce, defer or accelerate VAT can be adjusted by the tax authority (Implementing Regulations, Article 53). [2]
Penalties (the money):
- Late payment: a surcharge of 0.05% of the overdue tax per day from the day the tax becomes overdue (Tax Collection and Administration Law, Article 32). [6]
- Late filing: a fine of up to RMB 2,000, or RMB 2,000–10,000 in serious cases (Article 62). [6]
- Late registration: a fine of up to RMB 2,000, or RMB 2,000–10,000 in serious cases. If the taxpayer does not register even after being ordered to, its business licence can be revoked (Article 60). [6]
- Tax evasion: the unpaid tax and surcharge are recovered, plus a fine of 50% to 5 times the unpaid tax (Article 63). The same 50%–5x fine applies to failure to pay after a deadline set by the tax authority (Article 68). [6]
- Fapiao breaches such as not issuing, issuing out of time or sequence, or improper storage: a fine of up to RMB 10,000, and any illegal gains are confiscated (Fapiao Administrative Measures, Article 33). [5]
- False invoicing: illegal gains are confiscated. The fine is up to RMB 50,000 where the falsely invoiced amount is RMB 10,000 or less, and RMB 50,000–500,000 above that (Article 35). [5]
Frequently asked questions
What are the VAT rates in China?
Under Article 10 of the VAT Law, in force since 1 January 2026, the rates are: [1] [3]
- 13% for goods, processing, repair and replacement services, tangible movable property leasing and imports;
- 9% for transport, postal, basic telecommunications, construction and immovable-property leasing, sales of immovable property, land-use rights, and listed goods such as agricultural products, edible oil, utilities, books, feed and fertiliser;
- 6% for other services and intangible assets;
- 0% for exported goods and qualifying cross-border services.
Small-scale taxpayers on the simplified method pay a 3% levy rate (Article 11). Under MOF/STA Announcement No. 10 of 2026, this is reduced to 1% for most transactions from 1 January 2026 to 31 December 2027.
What is a small-scale taxpayer in China and when must a business register as a general taxpayer?
A small-scale taxpayer has annual taxable sales of RMB 5 million or less (VAT Law, Article 9). It may use the simplified method: sales multiplied by the levy rate, with no input credit. [1] [2]
- A unit or individual business that exceeds RMB 5 million must register as a general taxpayer and use the general method from the period it crossed the line.
- A small-scale taxpayer with sound accounting may register voluntarily.
- Registration as a general taxpayer is one-way: there is no conversion back (Implementing Regulations, Article 36).
- Natural persons are always small-scale taxpayers (Article 7).
What is the fully digitalised e-fapiao (数电发票)?
It is a form of electronic fapiao under the Fapiao Administrative Measures. Its face elements are fully digitised, its number is assigned nationally, its issuing quota is granted by the tax authority, and its data flows automatically through tax digital accounts. It has the same legal effect as paper. [4]
The STA rolled it out nationwide from 1 December 2024 (STA Announcement No. 11 of 2024), after pilots that began on 1 December 2021 in Guangdong, Shanghai and Inner Mongolia. Each e-fapiao has a 20-digit number and is issued free of charge through the national electronic fapiao service platform.
Does a foreign company selling services into China have to register for Chinese VAT?
The VAT Law does not create a registration regime for foreign sellers. Under Article 15, where a foreign unit or individual makes a taxable transaction in China, the purchaser is the withholding agent. It withholds VAT at the sales amount multiplied by the applicable rate, unless the foreign seller appoints a domestic agent to declare and pay. [1] [2]
A service is consumed in China, and so taxable there, where:
- a foreign seller sells it to a Chinese unit or individual, unless the service is consumed on site abroad; or
- it is directly related to goods, immovable property or natural resources in China (Implementing Regulations, Article 4).
A general-taxpayer purchaser that withholds can credit the VAT shown on the tax payment certificate as input tax (Implementing Regulations, Article 12).
When are Chinese VAT returns due?
The tax authority sets each taxpayer's tax period: 10 days, 15 days, one month or one quarter, by the amount of tax payable (VAT Law, Article 30). [1] [2] [6]
- Monthly or quarterly period: file and pay within 15 days after the period ends.
- 10- or 15-day period: prepay within 5 days after each period ends, and file within 15 days from the first day of the next month (Articles 30–31).
- Quarterly periods are open to small-scale taxpayers and to banks, finance companies, trust companies and credit cooperatives (Implementing Regulations, Article 43).
Late payment carries a surcharge of 0.05% per day (Tax Collection and Administration Law, Article 32).
Important websites
- State Taxation Administration (国家税务总局) — the national tax authority: policy releases, the policy and regulation database, and links to provincial tax services. The national site is often slow from outside China; provincial mirrors such as STA Shanghai carry the same policy texts.
- STA policy and regulation database — official texts of tax laws, regulations and MOF/STA announcements.
- Ministry of Finance (财政部) — co-issuer of VAT policy announcements, including export-refund rate changes.
- National Fapiao Verification Platform (全国增值税发票查验平台) — free verification of issued fapiao, including fully digitalised e-fapiao (named in STA Announcement No. 11 of 2024, item 11).
- National Enterprise Credit Information Publicity System — the business register, searchable by name or USCC.
- LookupTax — China USCI validator — checks the format and check character of an 18-character USCC.
VAT registration, filing and e-fapiao issuance are done through each province's electronic tax bureau (电子税务局), which a taxpayer reaches from its provincial tax service's website (for example STA Guangdong). This guide does not link a single national filing URL, because access is by province and requires a registered account.
Recent changes
- 2026-09-03 — MOF/STA Announcement No. 28 of 2026 issued the Measures for Domestic Entities Withholding VAT on Natural Persons. From 1 November 2026, a domestic unit paying an individual in China (境内自然人) for R&D, software, design, consulting, broadcast/film/TV production, cultural or education services must withhold VAT (sales multiplied by the levy rate) and surcharges at payment, where the payment per transaction (or per day) reaches the per-transaction threshold (RMB 1,000 under Announcement No. 10 of 2026) and the individual has not already paid the tax, and file monthly within 15 days of the following month. Until 31 October 2026, individuals self-declare under Article 44 of the Implementing Regulations. (STA Hainan) — see event
- 2026-08-27 — MOF/STA Announcement No. 25 of 2026, in force 1 September 2026, lists which "non-taxable transactions" block input-tax deduction. Insurance payouts, donations received, free services, assignment of own receivables and non-volume-linked subsidies do not block it; equity transfers, dividends and futures trading without delivery do. It also covers matters from 1 January to 31 August 2026 not yet dealt with. (STA Shanghai) — see event
- 2026-01-08 — MOF/STA Announcement No. 2 of 2026 cancelled the export VAT refund on photovoltaic and similar products from 1 April 2026. It cut the battery-product refund rate from 9% to 6% for 1 April to 31 December 2026, and abolishes the battery export VAT refund from 1 January 2027. (STA Guangdong) — see event
Reference links
- NPC — VAT Law of the People's Republic of China (中华人民共和国增值税法), adopted 25 December 2024, in force 1 January 2026
- State Council — Implementing Regulations of the VAT Law (State Council Decree No. 826)
- MOF — MOF/STA Announcement No. 10 of 2026 (VAT concessions after the VAT Law takes effect)
- State Council policy library — STA Announcement No. 11 of 2024 (national rollout of the fully digitalised e-fapiao)
- MOFCOM legal database — Fapiao Administrative Measures (2023 revision, State Council Decree No. 764)
- STA policy database — Tax Collection and Administration Law
- National Energy Administration (State Council notice reproduced) — Unified Social Credit Code master plan (国发〔2015〕33号)
- STA Shanghai — STA Announcement No. 16 of 2017 (buyer taxpayer ID or USCC on ordinary fapiao)
- STA Shanghai — MOF/STA Announcement No. 25 of 2026 (non-taxable transactions and input-tax deduction)
- STA Guangdong — MOF/STA Announcement No. 2 of 2026 (photovoltaic and battery export refunds)
- STA Hainan — MOF/STA Announcement No. 28 of 2026, Measures for Domestic Entities Withholding VAT on Natural Persons (PDF)
- State Council policy library — 财关税〔2018〕49号 (cross-border e-commerce retail import limits)
- MOF — Accounting Archives Management Measures (MOF/NAA Order No. 79)
- LookupTax — China TIN guide (USCC and Resident ID)