Hungary reverses the M-sheet VAT reporting rules via Act XXXV of 2026
This page records one dated change. For the rules in Hungary as they stand today, see the Hungary guide →
- Jurisdiction
- Hungary
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 31 July 2026
- Effective
- 31 July 2026
- Authority
- NAV (Hungarian Tax and Customs Administration) / Ministry of Finance
- Systems
- Reporting, ERP
- Verified
- Corroborated against official id · medium confidence
Hungarian VAT filers and their invoicing/reporting software vendors who had built for the stricter, invoice-level M-sheet (M-lap) reporting due to start 1 July 2026.
No action — monitoring only.
ReportingERP
Hungary carried out the announced reversal of the stricter invoice-level 'M-sheet' (M-lap) VAT-deduction reporting rules. The National Tax and Customs Administration states that the rules for reporting received invoices in the VAT return do not change: after 1 July 2026 businesses may continue to meet the reporting obligation under the rules in force on 30 June 2026, so for received invoices the deductible tax base and tax amount need not be shown separately by tax rate. NAV attributes the change to Act XXXV of 2026, which entered into force on 31 July 2026.
What changed in detail
The stricter, invoice-level “M-sheet” (M-lap) VAT reporting rules never took effect. NAV states that businesses may continue to meet their received-invoice reporting obligation under the rules that were in force on 30 June 2026 — so the deductible tax base and tax amount still do not need to be shown separately by tax rate. NAV attributes this to Act XXXV of 2026, which entered into force 31 July 2026.
This confirms, in enacted form, what the earlier entry reported only as the Ministry of Finance’s late-June intention to submit a bill. The bill became law: Act XXXV of 2026 amends Act LXXXIII of 2025 and the VAT Act (Act CXXVII of 2007) to keep the pre-July reporting practice in place rather than letting the stricter split take effect on schedule.
What it means
Nothing changes in what a Hungarian VAT filer’s software needs to produce today — that is the point. If a filer or vendor already built the invoice-level M-sheet split for a 1 July go-live, that work is not required, and there is now a named Act rather than a ministry announcement to point to if the question comes up in a review. Cite Act XXXV of 2026, not the June announcement, when documenting why the split was not implemented.
Proof
a vállalkozások 2026. július 1-jét követően is a június 30-án hatályos előírások szerint teljesíthetik adatszolgáltatási kötelezettségüket. Így a befogadott számlák esetében nem kell adómértékenként külön feltüntetni a levonásba helyezett adóalapot és adóösszeget.Businesses may continue to meet their data-reporting obligation after 1 July 2026 under the rules in force on 30 June; so for received invoices there is no need to show the deductible tax base and tax amount separately by tax rate.
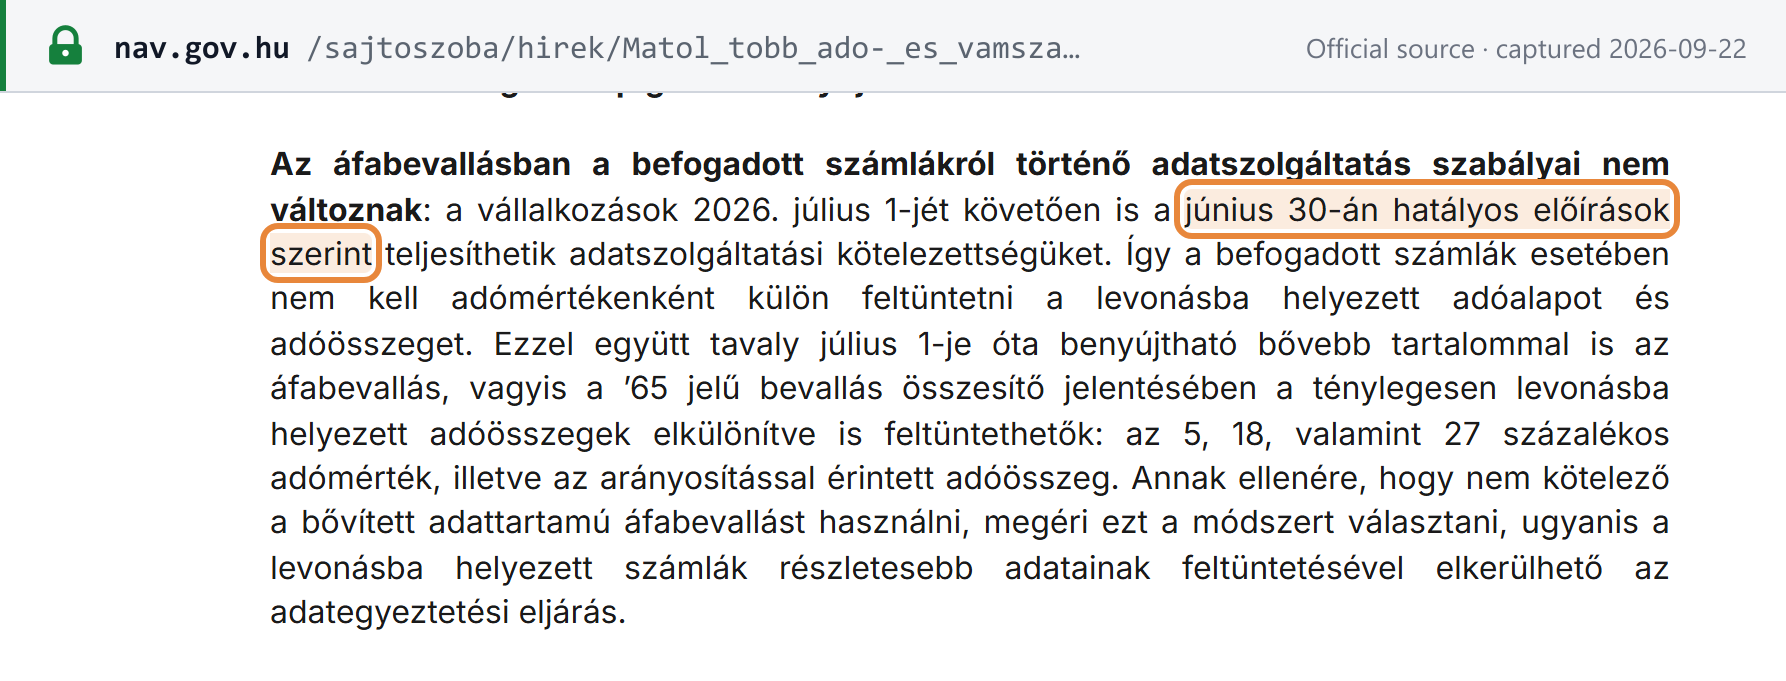 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Hungary says it will not enforce the stricter M-sheet rules effective 1 July 2026