Irish Revenue publishes new guidance on the VAT treatment of waste disposal services (eBrief 140/26)
This page records one dated change. For the rules in Ireland as they stand today, see the Ireland guide →
- Jurisdiction
- Ireland
- Tax
- VAT
- Change type
- Update
- Status
- In force
- Impact
- FYI
- Announced
- 25 September 2026
- Effective
- 25 September 2026
- Authority
- Office of the Revenue Commissioners
- Systems
- Tax engine
- Verified
- Fetched from official source · high confidence
Waste collection, disposal and treatment businesses in Ireland, local authorities supplying waste services, and their customers.
No action — monitoring only.
Tax engine
Irish Revenue eBrief No. 140/26 (25 September 2026) announced a new Tax and Duty Manual, 'VAT Treatment of Waste Disposal Services' (created September 2026). It states that acceptance of waste material for disposal, including waste removal and waste treatment, is taxable at the reduced rate. That covers bin or skip provision, household waste collection, dumping, shredding, incineration or burial, and disposal of dead animals. Treatment, storage or recycling of waste that remains the producer's property, and disposal of electronic records, are taxable at the standard rate. Sales of waste or recycled products are taxed at the rate for the product, and local authorities supplying these services are taxable persons.
What changed in detail
Irish Revenue eBrief No. 140/26, dated 25 September 2026, announced a new Tax and Duty Manual, ‘VAT Treatment of Waste Disposal Services’, created in September 2026.
The manual states that acceptance of waste material for disposal, including waste removal and waste treatment, is taxable at the reduced rate of VAT. That covers bin or skip provision, household waste collection, dumping, shredding, incineration or burial, and the disposal of dead animals.
Treatment, storage or recycling of waste that remains the property of the producer is taxable at the standard rate, as is the disposal of electronic records. Sales of waste or recycled products are taxed at the rate that applies to the product. Local authorities supplying these services are taxable persons.
What it means
The dividing line is who owns the waste. Where the supplier accepts waste for disposal, the reduced rate applies; where the waste stays the producer’s property and is only treated, stored or recycled, the standard rate applies. Businesses that bundle both kinds of service should check how each line is invoiced. Local authorities should note that the manual treats them as taxable persons for these supplies.
Proof
Supplies of services consisting of the acceptance for disposal of waste material, including waste removal and waste treatment are taxable at the reduced rate of VAT.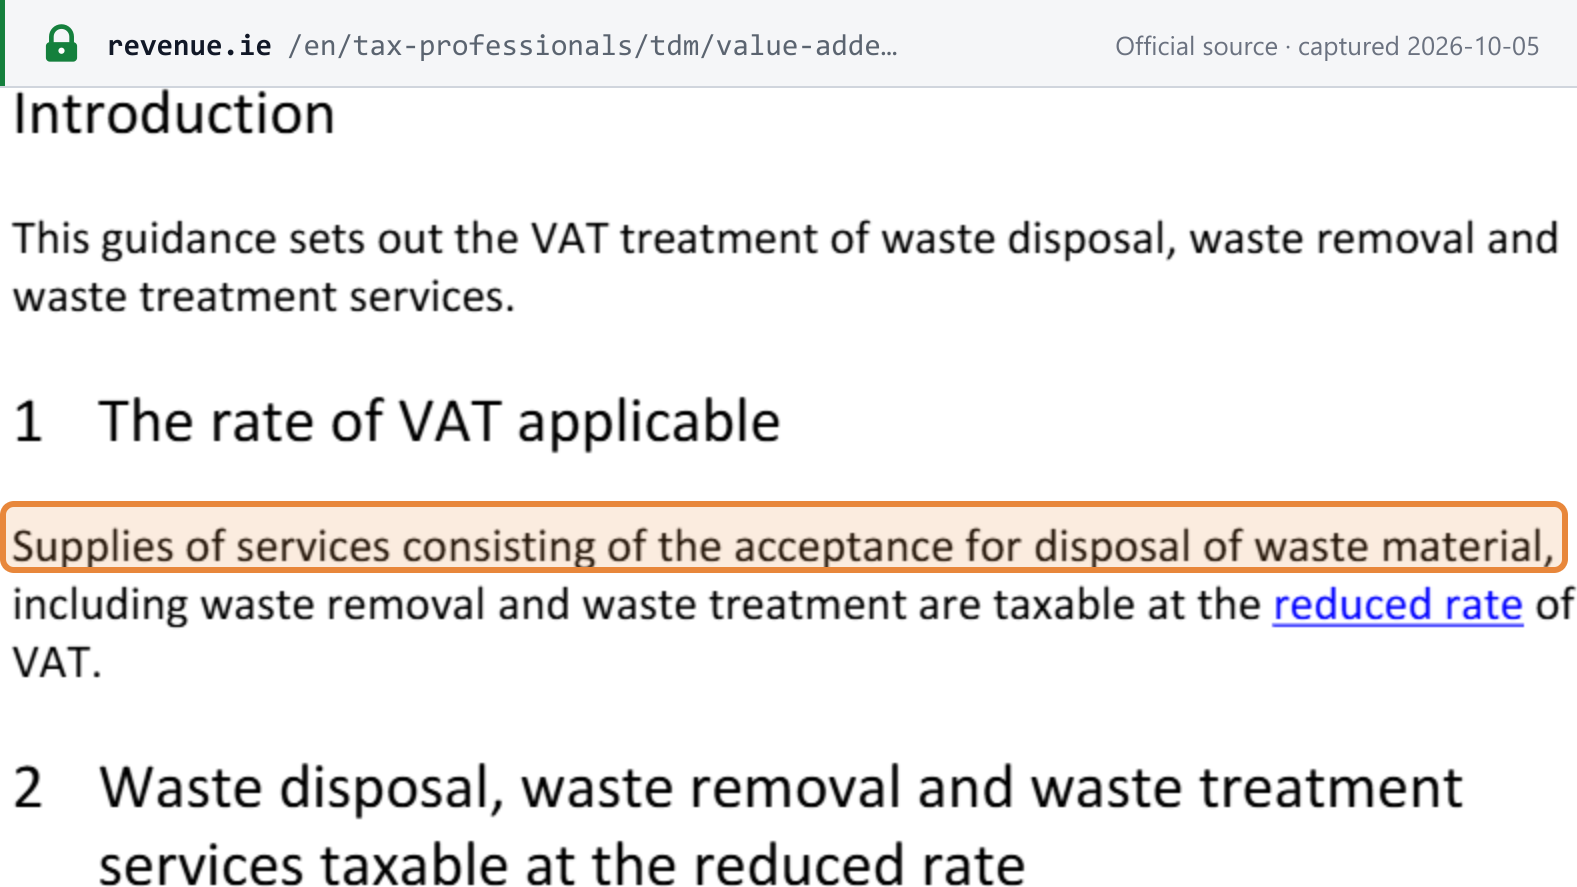 Source snapshot of the official page. Open full size ↗