Ireland cuts the flat-rate farmer addition from 5.1% to 4.5%
This page records one dated change. For the rules in Ireland as they stand today, see the Ireland guide →
- Jurisdiction
- Ireland
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 1 December 2025
- Effective
- 1 January 2026
- Authority
- Irish Statute Book (electronic Irish Statute Book, Office of the Attorney General)
- Systems
- ERP, Tax engine
- Verified
- Fetched from official source · high confidence
VAT-registered businesses buying agricultural goods or services from unregistered flat-rate farmers, and the farmers charging the addition.
Use the 4.5% flat-rate addition on purchases from unregistered farmers from 1 January 2026.
ERPTax engine
Section 73 of Ireland's Finance Act 2025 amends section 86(1) of the VAT Consolidation Act 2010 with effect from 1 January 2026, reducing the flat-rate addition charged by unregistered flat-rate farmers from 5.1% to 4.5%.
What changed in detail
Section 73 of Finance Act 2025 (Act No. 18 of 2025) amends section 86(1) of the VAT Consolidation Act 2010, with effect from 1 January 2026, substituting “4.5 per cent” for “5.1 per cent”. The flat-rate addition is the compensating percentage that an unregistered flat-rate farmer adds to the price charged to a VAT-registered customer, standing in for the VAT the farmer cannot otherwise recover on inputs.
This change has already been in force for nine months; it was not caught and published until this issue.
What it means
Any purchase invoice from an unregistered flat-rate farmer dated 1 January 2026 or later should show 4.5%, not 5.1%. A business still applying the old 5.1% rate in its purchase records or ERP tax tables has been over-claiming the flat-rate addition since the start of the year and should correct the rate table and check invoices processed since then.
Proof
by the substitution of "4.5 per cent" for "5.1 per cent"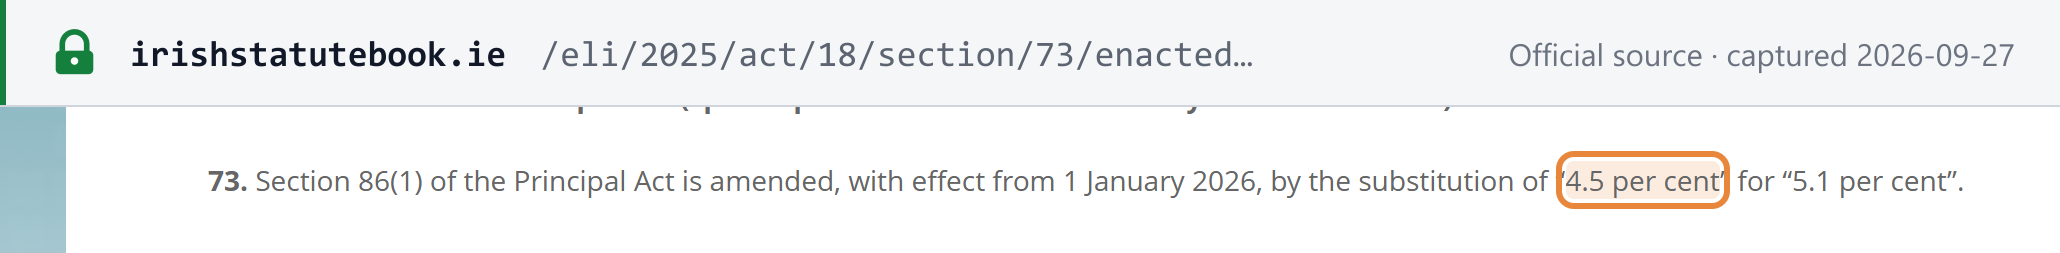 Source snapshot of the official page. Open full size ↗