Ireland moves hotel and guesthouse room hire for non-accommodation use to the standard VAT rate
This page records one dated change. For the rules in Ireland as they stand today, see the Ireland guide →
- Jurisdiction
- Ireland
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 1 December 2025
- Effective
- 1 January 2026
- Authority
- Irish Statute Book (electronic Irish Statute Book, Office of the Attorney General)
- Systems
- Tax engine, POS
- Verified
- Fetched from official source · high confidence
Hotels and guesthouses hiring out rooms for purposes other than accommodation, such as conferences and events; the standard rate now applies to those hires instead of the reduced rate.
Charge the standard rate on hotel and guesthouse room hire for non-accommodation use.
Tax enginePOS
Section 72 of Ireland's Finance Act 2025 amends section 60(1) and Schedule 3, paragraph 11 of the VAT Consolidation Act 2010 with effect from 1 January 2026, so that the reduced rate for lettings of holiday or guest accommodation no longer covers the hire of hotel or guesthouse rooms for purposes other than accommodation, such as conferences and events; those hires are charged at the standard rate.
What changed in detail
Section 72 of Finance Act 2025 (Act No. 18 of 2025) amends section 60(1) and Schedule 3, paragraph 11 of the VAT Consolidation Act 2010, with effect from 1 January 2026. It narrows the reduced-rate description for lettings of “holiday or guest accommodation” so that it no longer extends to the hire of a hotel or guesthouse room for a purpose other than accommodation — for example, hiring a room for a conference or an event. Those hires are now charged at the standard rate rather than the reduced rate.
This change has already been in force for nine months; it was not caught and published until this issue.
What it means
The practical effect is a room-by-room test, not a property-wide one: the same hotel can charge the reduced rate on an overnight stay and the standard rate on the identical room hired out for a conference the same week. Hotels and guesthouses that were still applying the reduced rate to event and meeting-room hire after 1 January 2026 have been under-charging VAT since the start of the year and should correct billing and any returns already filed on the old basis.
Proof
the provision of holiday or guest accommodation in—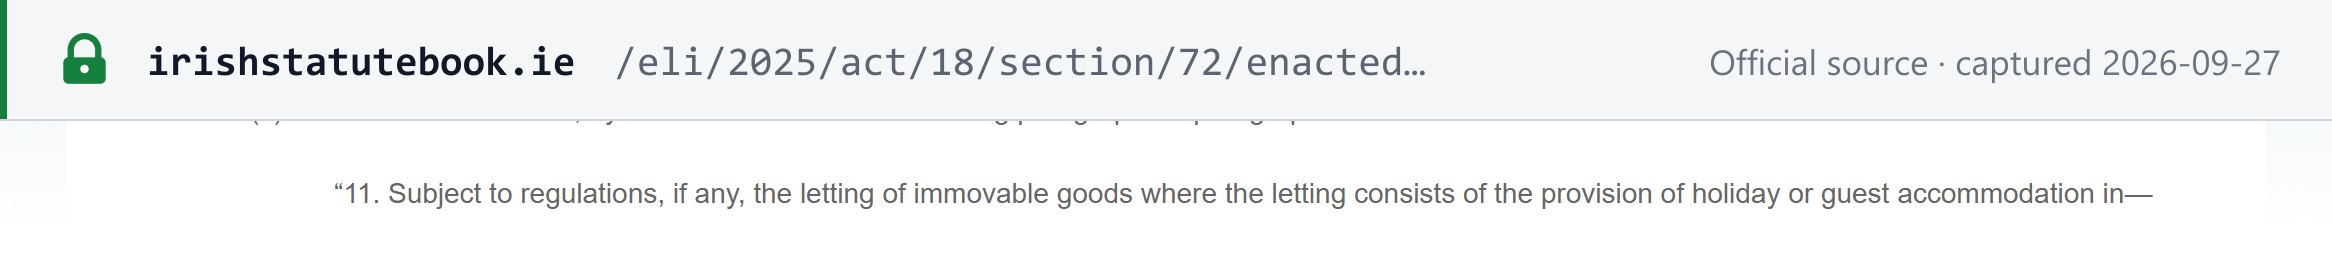 Source snapshot of the official page. Open full size ↗