Italy revises ex officio closure of inactive VAT numbers: notice to the digital address, closure from day 60 (Provvedimento 277710/2026)
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Registration
- Status
- Enacted
- Impact
- Watch
- Announced
- 12 October 2026
- Authority
- Agenzia delle Entrate (Italian Revenue Agency)
- Systems
- ERP, Reporting
- Verified
- Fetched from official source · high confidence
Holders of Italian VAT numbers (partite IVA) that, on the Agenzia's data, have carried on no business, artistic or professional activity in the three preceding years.
Check that the PEC/digital domicile on file for each Italian VAT number is current so closure notices are received.
ERPReporting
Italy's Agenzia delle Entrate Director issued Provvedimento Prot. n. 277710/2026 on 12 October 2026 amending the Director's Provvedimento of 3 December 2019 (n. 1415522) on ex officio closure of inactive VAT numbers (partite IVA) under Article 35(15-quinquies) of DPR 633/1972. Inactive VAT numbers are identified by automated checks on Anagrafe tributaria data, including e-invoices, electronic receipts and voluntary payments; a prior closure notice is sent to the holder's digital address (or by registered post), and closure takes effect from the 60th day after receipt. Within 60 days the holder may contest the closure at any Agenzia office, and after 60 days may request reactivation with reasons; a reactivated VAT number takes effect from its original opening date without interruption.
What changed in detail
The Director of the Agenzia delle Entrate issued Provvedimento Prot. n. 277710/2026 on 12 October 2026. It amends the Director’s Provvedimento of 3 December 2019 (n. 1415522), which governs the ex officio closure of inactive VAT numbers under Article 35(15-quinquies) of DPR 633/1972.
Identification. Inactive VAT numbers are identified by automated checks on information held in the Anagrafe tributaria, including data on electronic invoices, electronic receipts (corrispettivi telematici) and voluntary payments.
Notice. A prior notice of ex officio closure is sent to the holder’s digital address under Article 60-ter of DPR 600/1973 or, failing that, to the representative’s digital address. Where neither exists, it goes by registered post with return receipt to the tax domicile on record. The notice is also available in the “L’Agenzia scrive” section of the Cassetto fiscale.
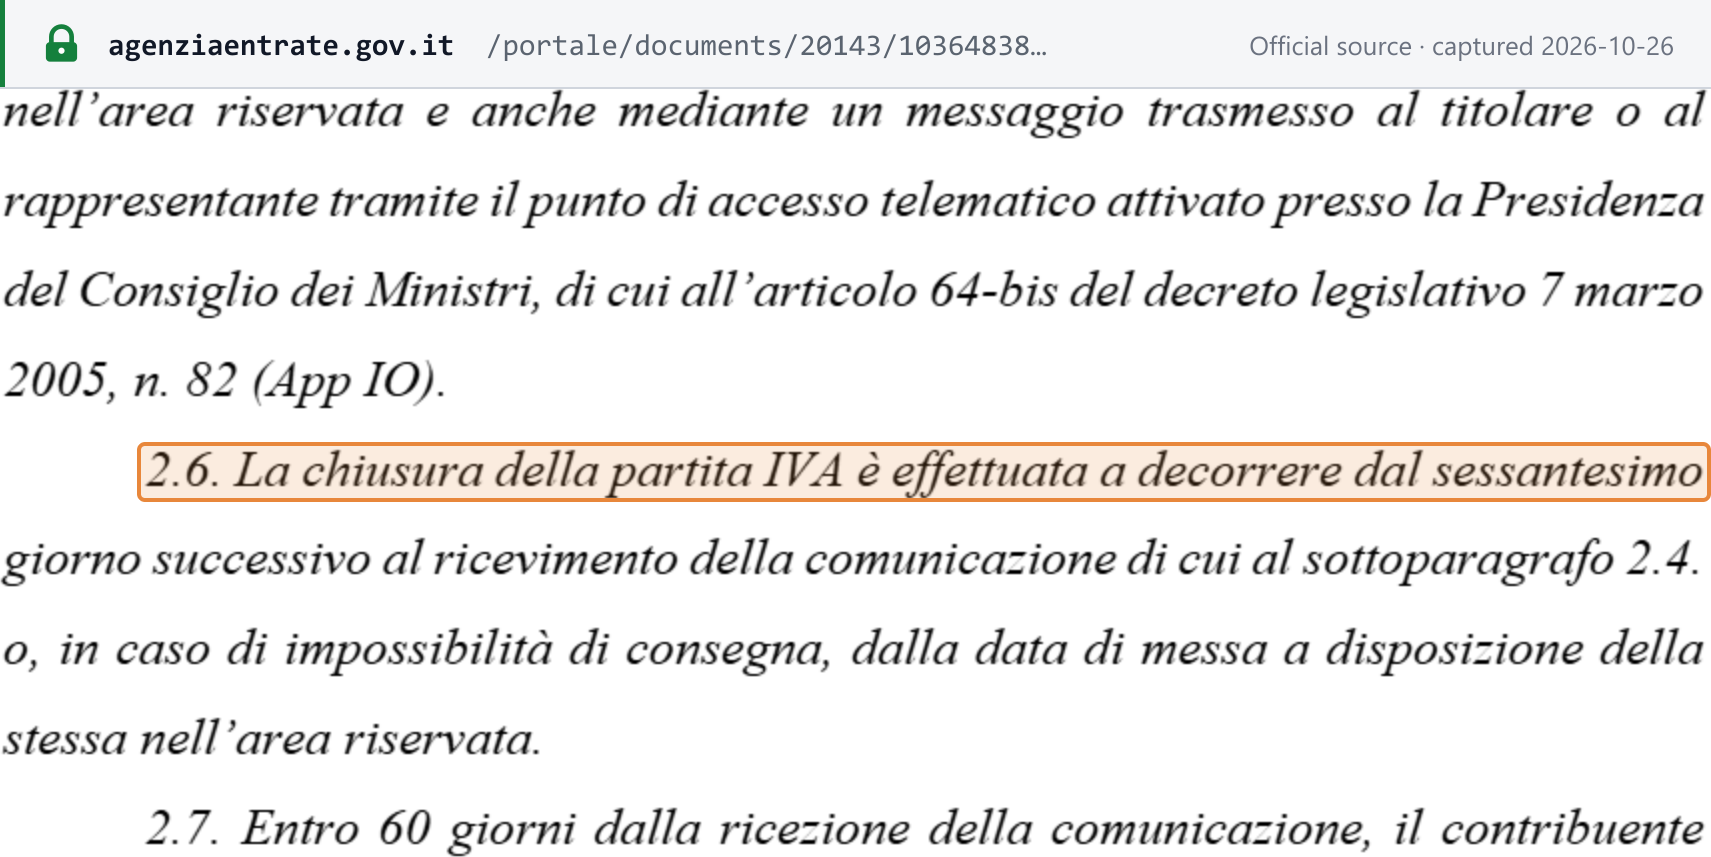
Closure. The VAT number is closed from the 60th day after receipt of the notice or, where delivery is impossible, from the date it is made available in the reserved area.
Challenge and reactivation. Within 60 days of receipt, the holder may go to any Agenzia territorial office to contest the closure. After 60 days, the holder may ask any office for reactivation, giving reasons. A reactivated VAT number takes effect from its original opening date, without interruption.
What it means
The practical risk is a dormant or lightly used Italian VAT number being closed because a notice went to a digital address nobody monitors. Keep the PEC or other digital domicile on file current for every Italian registration, including those of non-resident entities with a representative. Because e-invoice and receipt data now feed the check, a number with no invoicing traffic is the likeliest to be flagged. Reactivation is retroactive to the opening date, but contesting within the 60 days avoids the gap altogether.
Proof
2.6. La chiusura della partita IVA è effettuata a decorrere dal sessantesimo giorno successivo al ricevimento della comunicazione di cui al sottoparagrafo 2.4.2.6. The VAT number is closed with effect from the sixtieth day following receipt of the notice referred to in sub-paragraph 2.4.
 Source snapshot of the official page. Open full size ↗