Kazakhstan draft Tax Code amendment would make resident internet platforms the VAT payer on foreign sellers' B2C sales — a draft, not law
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Kazakhstan as they stand today, see the Kazakhstan guide →
- Jurisdiction
- Kazakhstan
- Tax
- VAT
- Change type
- Digital services
- Status
- Proposed
- Impact
- Watch
- Announced
- 3 September 2026
- Effective
- 1 January 2027
- Authority
- Ministry of National Economy of the Republic of Kazakhstan (Open NPA portal)
- Systems
- E-commerce, Tax engine, Reporting
- Verified
- Fetched from official source · medium confidence
Kazakhstan-resident internet platforms and marketplaces, and foreign sellers of goods and electronic services to individuals in Kazakhstan.
Confirm whether your marketplace or platform is a Kazakhstan-resident internet platform and model VAT collection at the 16% standard rate for foreign sellers' B2C sales from 1 January 2027, pending adoption.
E-commerceTax engineReporting
A draft law amending Kazakhstan's Tax Code (No. 214-VIII ZRK of 18 July 2025), posted on the Open NPA portal by the Ministry of National Economy (created 3 September 2026; public discussion closed 25 September 2026), would add Articles 826-1 to 826-4. A Kazakhstan-resident internet platform (internet-alan) through which a foreign person sells goods or supplies electronic services to individuals would be the VAT payer; the foreign person's turnover through the platform would be the taxable turnover; VAT would be computed at the Article 503(1) standard rate, with a quarterly tax period. Draft Article 826(4) would also provide that e-commerce VAT is not charged where import VAT paid on EAEU goods is included in the taxable import value and is not refundable. The draft's general commencement date is 1 January 2027. It is a draft only.
What changed in detail
This is a draft, not law. The draft law amending Kazakhstan’s Tax Code (No. 214-VIII ZRK of 18 July 2025) was posted on the Open NPA portal by the Ministry of National Economy (created 3 September 2026; public discussion closed 25 September 2026). It has not been adopted.
The draft would add Articles 826-1 to 826-4. A Kazakhstan-resident internet platform through which a foreign person sells goods or supplies electronic services to individuals would be the VAT payer. The foreign person’s turnover through the platform would be the taxable turnover, VAT would be computed at the Article 503(1) standard rate, and the tax period would be a quarter. Draft Article 826(4) would also provide that e-commerce VAT is not charged where import VAT paid on EAEU goods is included in the taxable import value and is not refundable. The draft’s general commencement date is 1 January 2027.
What it means
The model shifts collection from the foreign seller to the local platform, so marketplaces would carry the compliance burden. Platforms should check whether they fall within the definition of a resident internet platform and model collection at the standard rate for foreign sellers’ B2C sales. Do not treat any of this as final until the law is adopted and published.
Proof
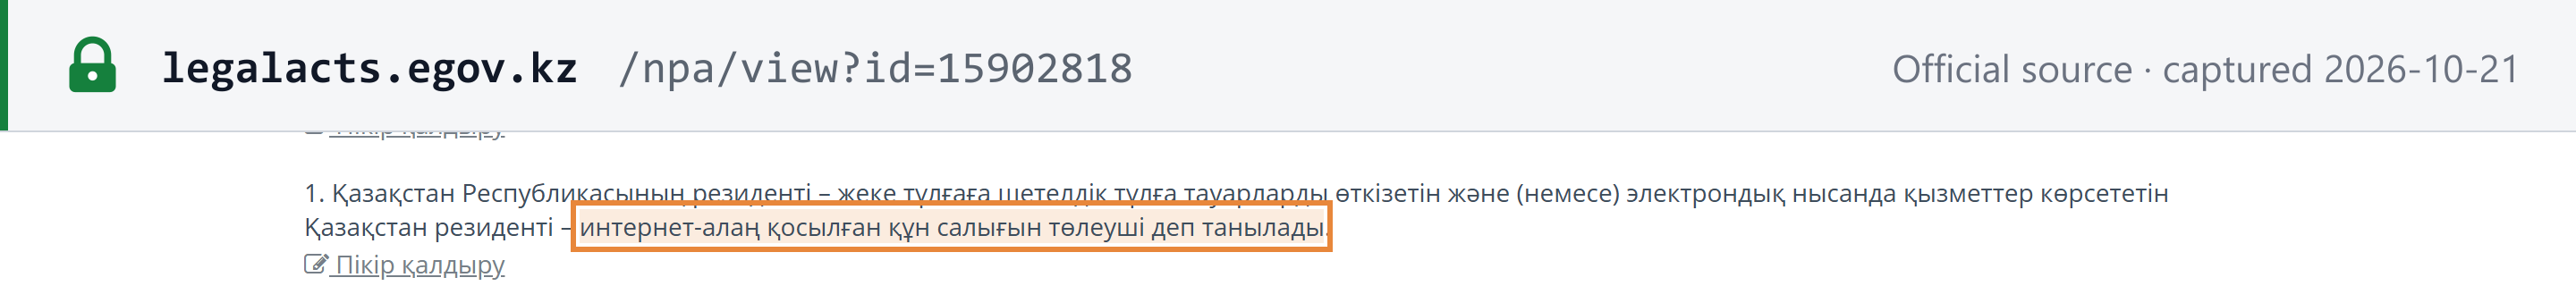
1. Қазақстан Республикасының резиденті – жеке тұлғаға шетелдік тұлға тауарларды өткізетін және (немесе) электрондық нысанда қызметтер көрсететін Қазақстан резиденті – интернет-алаң қосылған құн салығын төлеуші деп танылады.A resident of the Republic of Kazakhstan - an internet platform through which a foreign person sells goods and (or) supplies services in electronic form to an individual - is recognised as a value added tax payer.
 Source snapshot of the official page. Open full size ↗