Kazakhstan draft Tax Code amendment would allow some VAT refunds within ten working days via digital tenge — a draft, not law
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Kazakhstan as they stand today, see the Kazakhstan guide →
- Jurisdiction
- Kazakhstan
- Tax
- VAT
- Change type
- Compliance
- Status
- Proposed
- Impact
- Watch
- Announced
- 3 September 2026
- Effective
- 1 January 2027
- Authority
- Ministry of National Economy of the Republic of Kazakhstan (Open NPA portal)
- Systems
- Reporting, ERP
- Verified
- Fetched from official source · medium confidence
Kazakhstan VAT taxpayers with excess VAT, in particular exporters and zero-rated suppliers, in the categories to be set by the authorised body.
No action — monitoring only; exporters and zero-rated suppliers should note the proposed 10-working-day refund track via digital tenge.
ReportingERP
The same draft Tax Code amendment would add Article 127-1, under which the part of excess VAT (tax overpayment) formed on purchased goods whose onward sale was settled in digital tenge could be refunded without a tax audit within ten working days after the due date for filing the return claiming the refund, for taxpayers who open a digital account at a second-tier bank, confirm payment in digital tenge and consent to data exchange. The categories of eligible taxpayers would be set by the authorised body. Draft only; general commencement date 1 January 2027.
What changed in detail
This is a draft, not law. It is part of the same draft Tax Code amendment posted on the Open NPA portal by the Ministry of National Economy (created 3 September 2026; public discussion closed 25 September 2026).
The draft would add Article 127-1. The part of excess VAT (tax overpayment) formed on purchased goods whose onward sale was settled in digital tenge could be refunded without a tax audit within ten working days after the due date for filing the return claiming the refund. The track would be open to taxpayers who open a digital account at a second-tier bank, confirm payment in digital tenge and consent to data exchange. The categories of eligible taxpayers would be set by the authorised body. The draft’s general commencement date is 1 January 2027. The track would not apply to ordinary refunds under Article 127.
What it means
The proposal pairs a fast, audit-free refund with digital-tenge settlement. Exporters and zero-rated suppliers would be the natural users, but eligibility depends on categories not yet defined. Plan nothing around the ten-day timeline until the law is adopted.
Proof
2. Цифрлық теңгені пайдалана отырып салықтың асып кету сомасын қайтару салықтың асып кету сомасын қайтару туралы талап көрсетілген салық декларациясын салық органына ұсыну үшін осы Кодексте белгіленген күн өткеннен кейін он жұмыс күні ішінде салықтық тексеру жүргізбестен салықтың асып кету сомасын қайтаруды жүзеге асырудан тұрады.Refund of the excess tax amount using digital tenge consists of refunding the excess tax amount within ten working days after the date set by this Code for submitting to the tax authority the tax return stating the claim for refund, without conducting a tax audit.
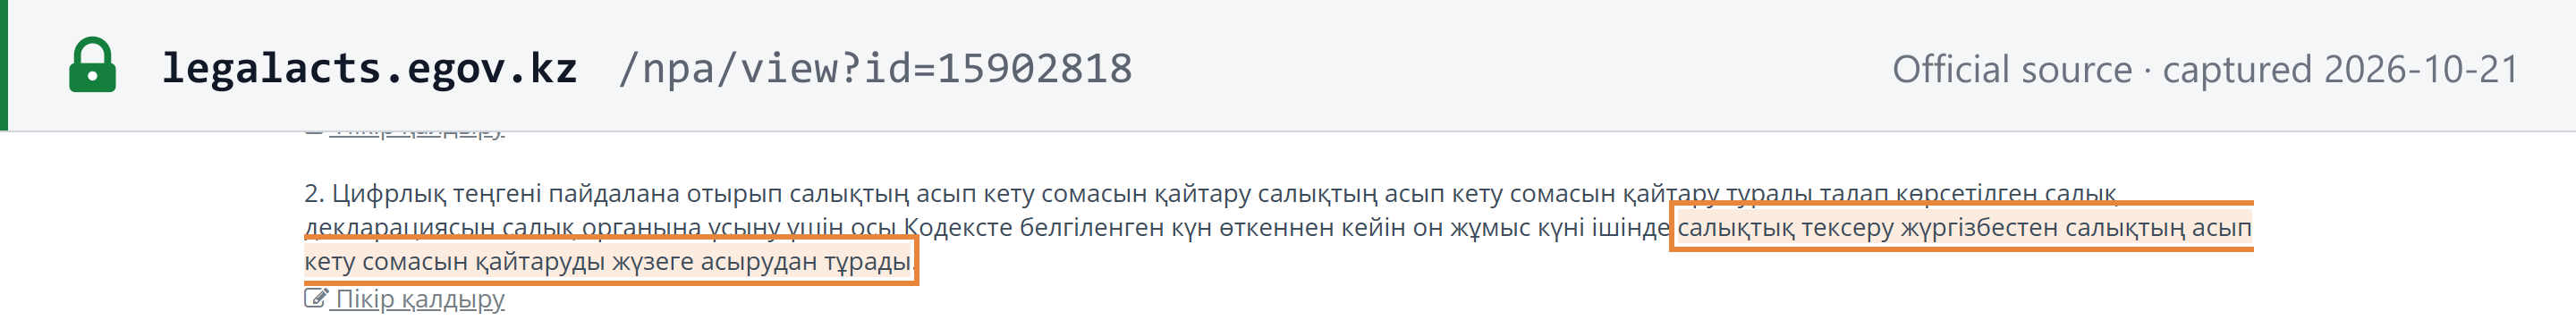 Source snapshot of the official page. Open full size ↗