Malaysia's Budget 2027 proposes a sales tax refund for traders supplying machinery and inputs to manufacturers from 1 January 2027
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Malaysia as they stand today, see the Malaysia guide →
- Jurisdiction
- Malaysia
- Tax
- Sales tax
- Change type
- Compliance
- Status
- Proposed
- Impact
- Plan ahead
- Announced
- 9 October 2026
- Effective
- 1 January 2027
- Authority
- Ministry of Finance Malaysia (Kementerian Kewangan)
- Systems
- ERP, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Traders and local distributors who paid sales tax on machinery, spare parts, equipment and approved inputs that they supplied to manufacturers.
Traders and distributors supplying manufacturers: watch for the implementing order and claim procedure before 1 January 2027.
ERPTax engineReporting
Malaysia's Budget 2027, tabled 9 October 2026, proposes a sales tax refund facility for traders or local distributors who paid sales tax on machinery, spare parts and equipment (Item 55, Schedule A) and on approved inputs for pharmaceutical, animal feed, fertiliser and pesticide manufacturing (Schedule B) that they supplied to manufacturers, under the Sales Tax (Persons Exempted From Payment of Tax) Order 2018. Proposed effective 1 January 2027; implementing instrument not yet published.
What changed in detail
This is a budget proposal, not an enacted measure. Malaysia’s Budget 2027, tabled on 9 October 2026, proposes a sales tax refund facility in Appendix 33 of the Budget 2027 tax measures (Langkah Cukai).
The facility would go to traders or local distributors who paid sales tax on goods they supplied to manufacturers, covering:
- machinery, spare parts and equipment under Item 55, Schedule A of the Sales Tax (Persons Exempted From Payment of Tax) Order 2018; and
- approved inputs for manufacturing pharmaceutical, animal feed, fertiliser and pesticide products under Schedule B of the same Order.
Under the current position described in the appendix, manufacturers are exempt on these goods only where they import them directly or buy them directly from a registered local manufacturer. No exemption applies where the goods are bought from a local trader or distributor. The proposed refund would be effective from 1 January 2027. The implementing instrument has not yet been published.
What it means
The proposal targets a gap in the exemption: a manufacturer buying through a local trader pays sales tax that a direct importer would not. A refund to the trader or distributor, rather than an exemption, changes who carries that cash cost.
Nothing can be claimed until the implementing order and claim procedure are published. Traders and distributors that supply manufacturers should record sales tax paid on qualifying lines from now, so they can substantiate refunds if the proposal is enacted as announced for 1 January 2027.
Proof
dicadangkan kemudahan bayaran balik cukai jualan diberikan kepada pedagang atau pengedar tempatan yang telah membayar cukai jualan ke atas barangan yang dibekalkan kepada pengilangit is proposed that a sales tax refund facility be given to traders or local distributors who have paid sales tax on goods supplied to manufacturers
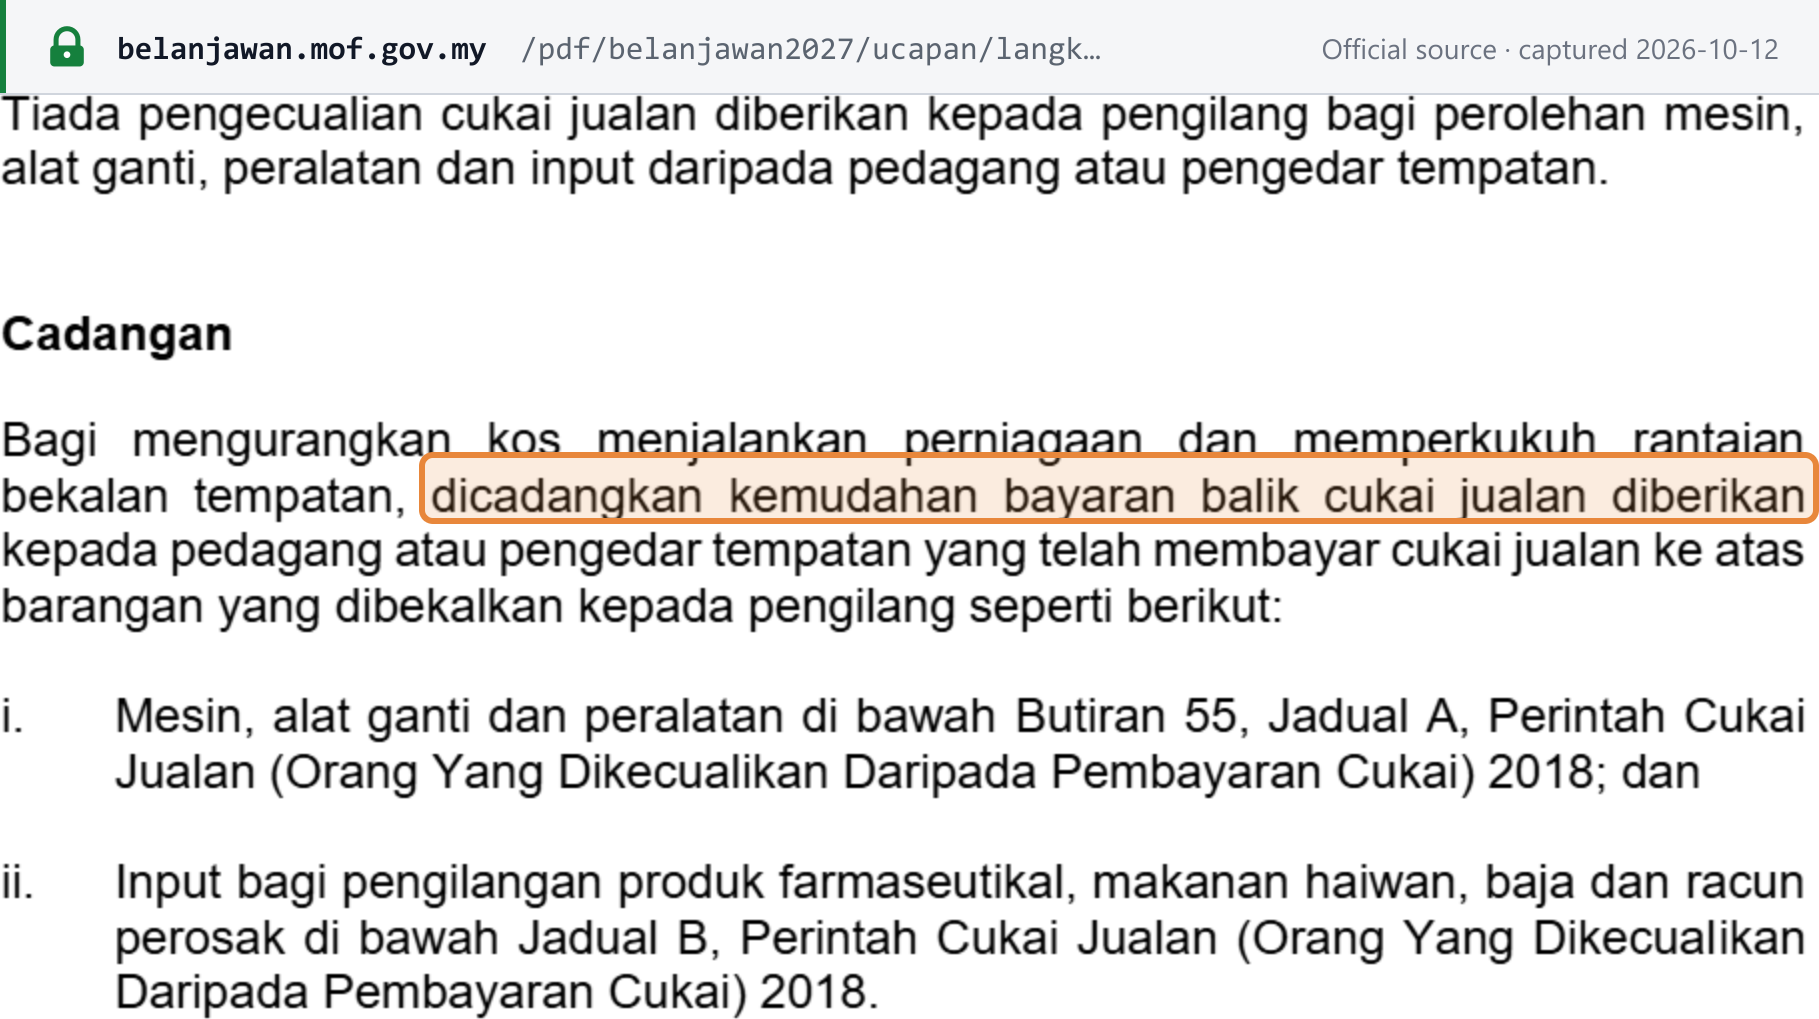 Source snapshot of the official page. Open full size ↗