Maldives makes MIRAconnect the mandatory channel for GST filing and payment
- Jurisdiction
- Maldives
- Tax
- GST
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 21 September 2026
- Effective
- 1 January 2027
- Authority
- Maldives Inland Revenue Authority (MIRA)
- Systems
- Reporting, Tax engine
- Verified
- Fetched from official source · high confidence
Every person registered, or required to be registered, for Maldives GST; non-resident suppliers of inbound tourism products under GST Act section 15(a)(6) move to MIRAconnect earlier, from 1 October 2026.
Be able to file the Maldives GST return through MIRAconnect and pay GST via MIRAconnect or MRTGS by 1 January 2027, or by 1 October 2026 if supplying inbound tourism products from outside the Maldives.
ReportingTax engine
Regulation 2026/R-82 (32nd Amendment to the GST Regulation), gazetted 21 September 2026, adds paragraphs to section 78-2 of the GST Regulation: persons registered or required to be registered for GST must file the GST return through MIRAconnect, and must pay GST and GST-related fines through MIRAconnect or MRTGS. Those two paragraphs take effect from 1 January 2027; for persons supplying the services described in section 15(a)(6) of the GST Act (inbound tourism products and related agency or booking services supplied by a person with no permanent place of business in the Maldives) they take effect from 1 October 2026. The existing paragraphs (a) and (b) of section 78-2 apply only until 31 December 2026, and the Commissioner General may allow another filing or payment channel where a person has a reasonable excuse. English wording below is the analyst own translation of the Dhivehi text and is not part of the instrument; the evidence quote is the Thaana original.
What changed in detail
Regulation 2026/R-82 (the 32nd Amendment to the GST Regulation), gazetted 21 September 2026, adds paragraphs to section 78-2 of the GST Regulation: persons registered or required to be registered for GST must file the GST return through MIRAconnect, and must pay GST and GST-related fines through MIRAconnect or MRTGS.
Those two paragraphs take effect from 1 January 2027. For persons supplying the inbound tourism products and related agency or booking services described in GST Act section 15(a)(6) - suppliers with no permanent place of business in the Maldives - they take effect earlier, from 1 October 2026. The existing paragraphs (a) and (b) of section 78-2 apply only until 31 December 2026, and the Commissioner General may allow another filing or payment channel where a person has a reasonable excuse.
What it means
Non-resident inbound-tourism suppliers get the shorter runway: they move to MIRAconnect-only filing and payment three months before everyone else, on 1 October 2026 rather than 1 January 2027, which is the detail most likely to be missed by a supplier reading only the general commencement date. Every GST-registered person should confirm MIRAconnect access - and, for payment, an MRTGS route - works before their applicable date, since the existing channel under section 78-2(a)/(b) stops being available at the end of the same transition.
Proof
މި މާއްދާގެ (ބ) އާއި (ޅ) އަށް ޢަމަލުކުރާނީ، 1 ޖަނަވަރީ 2027 އިން ފެށިގެންނެވެ.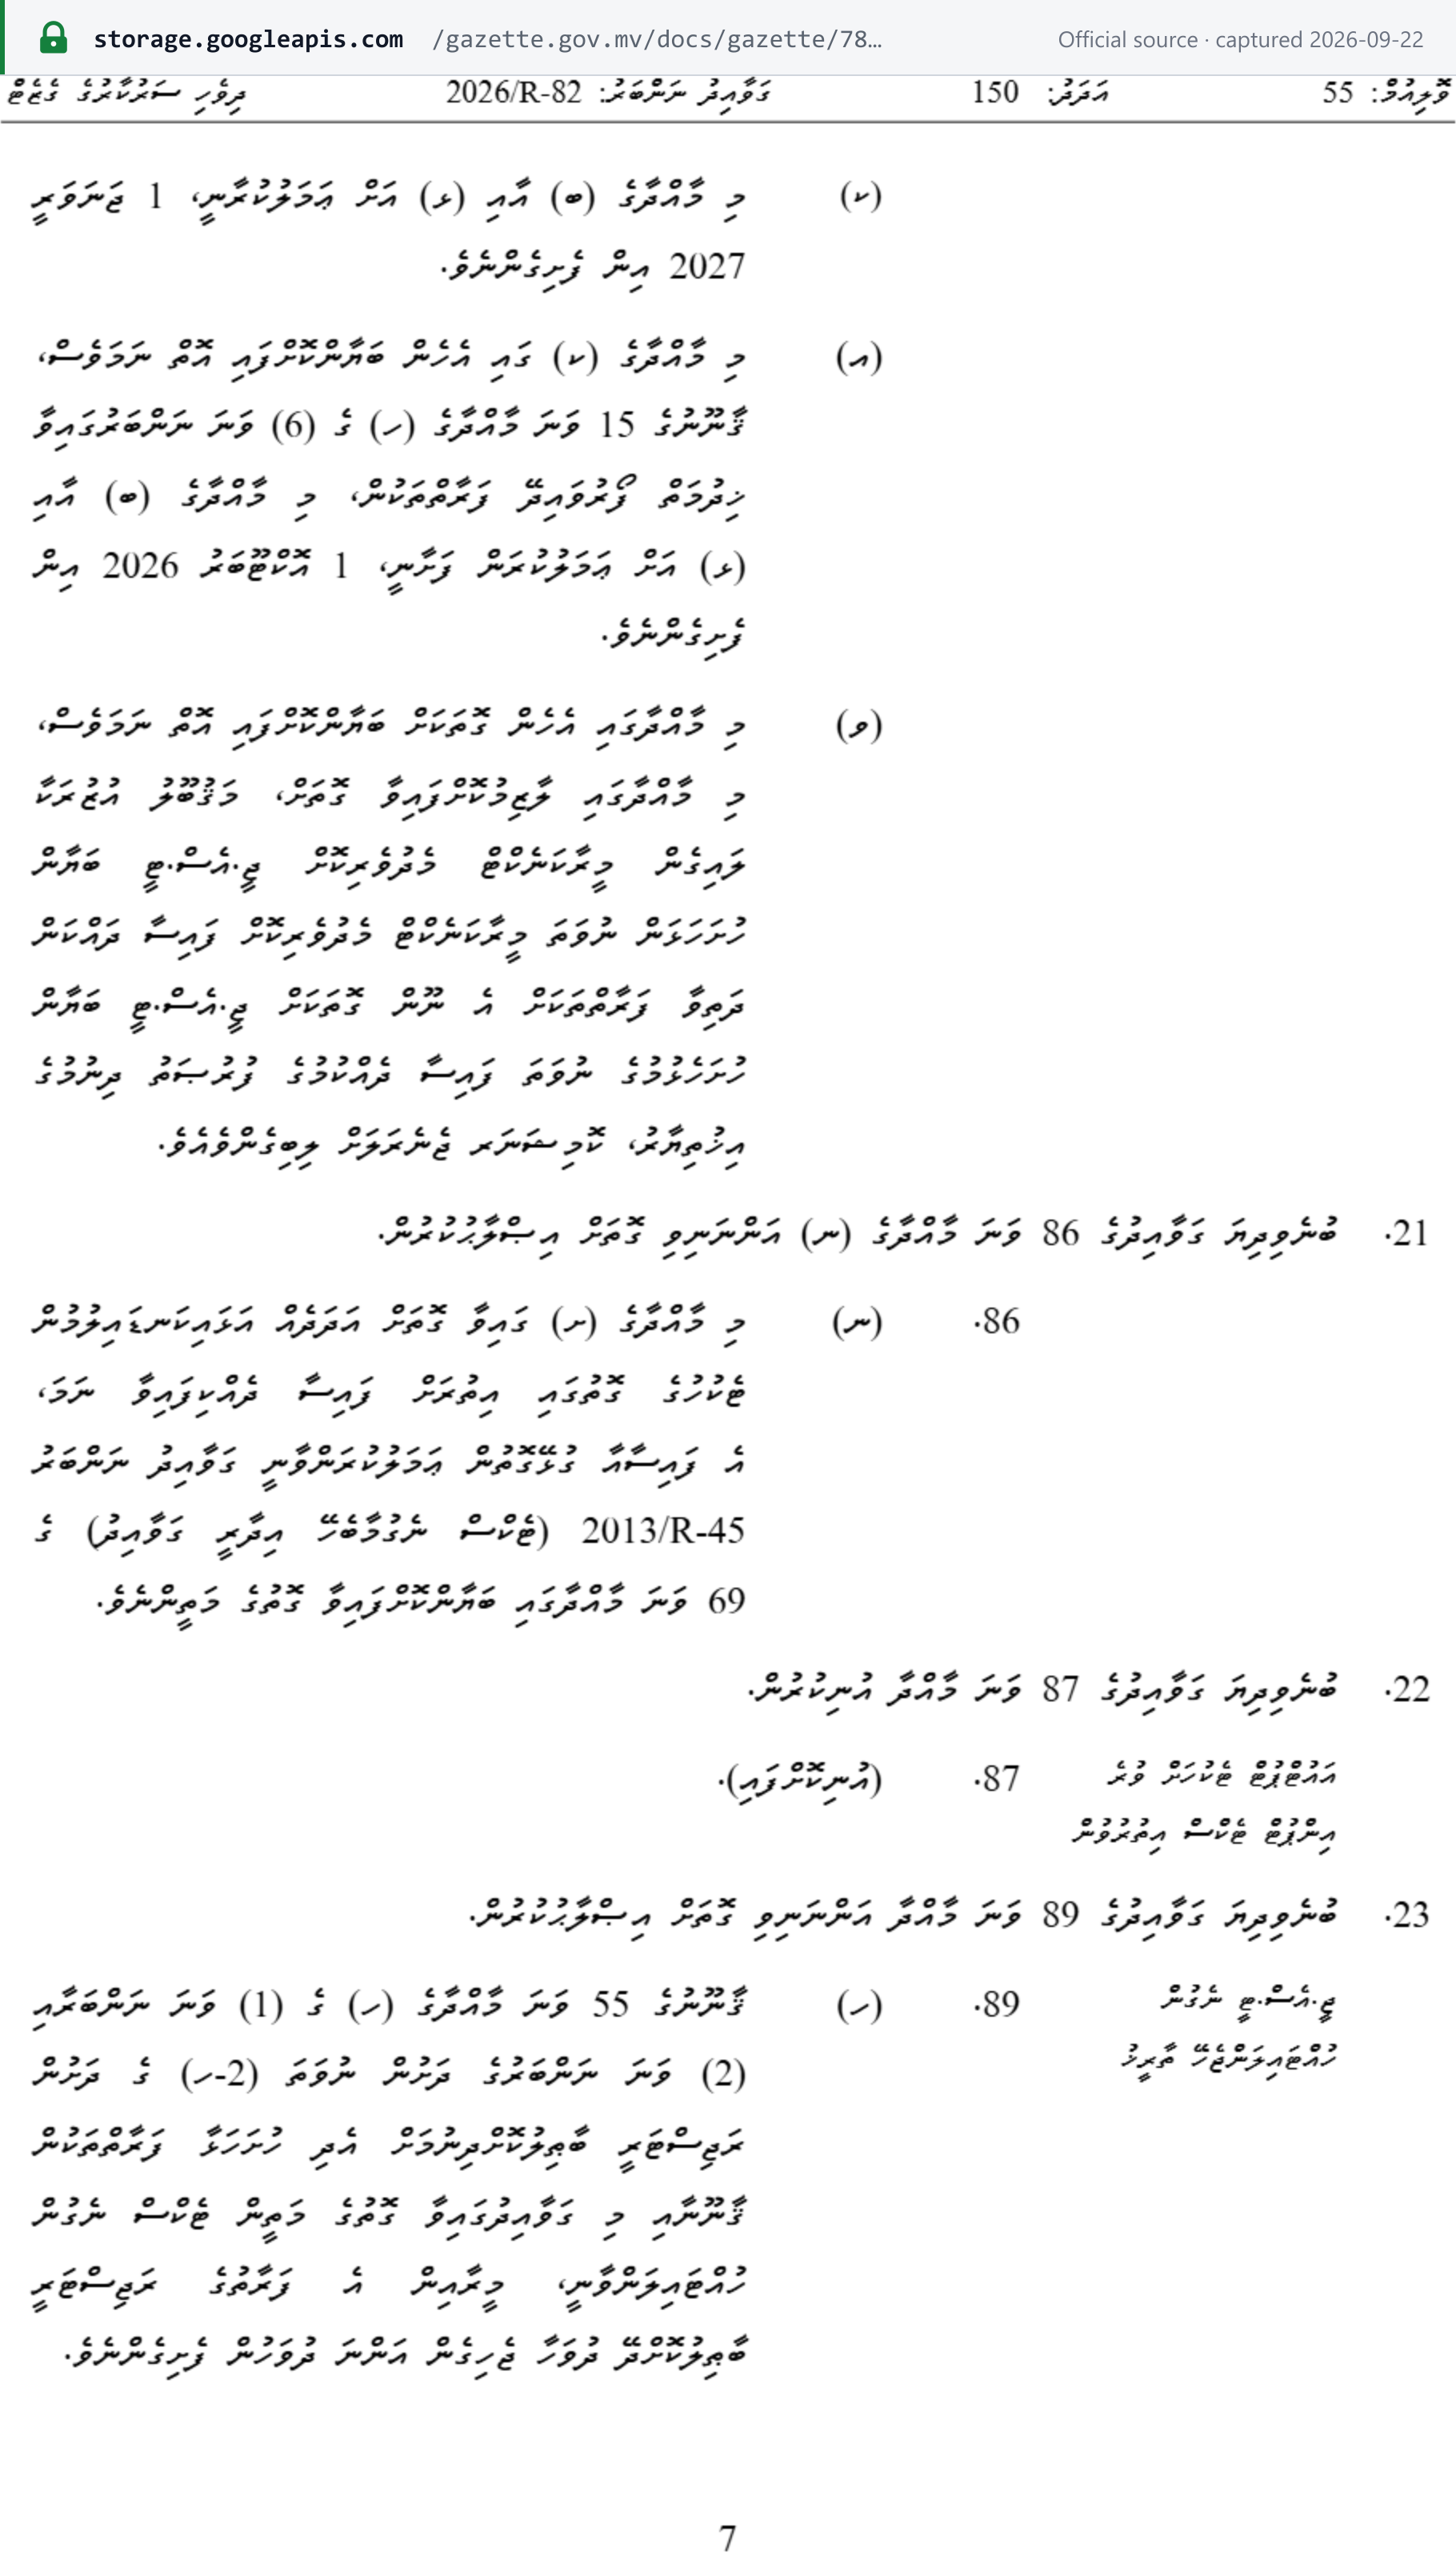 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Regulation 2026/R-82, 32nd Amendment to the GST Regulation - Gazette of Maldives, Volume 55 No. 150, 21 September 2026 · storage.googleapis.com