Maldives builds out GST registration for non-resident inbound-tourism suppliers
- Jurisdiction
- Maldives
- Tax
- GST
- Change type
- Registration
- Status
- Enacted
- Impact
- Action required
- Announced
- 21 September 2026
- Effective
- 1 October 2026
- Authority
- Maldives Inland Revenue Authority (MIRA)
- Systems
- Invoicing, Tax engine, E-commerce, Reporting
- Verified
- Fetched from official source · high confidence
Persons with no permanent place of business in the Maldives who supply inbound tourism products or related agency/booking services under GST Act section 15(a)(6).
Non-resident suppliers of Maldives inbound tourism products and related agency or booking services should register for GST with MIRA on form MIRA 120 and account for GST on transactions invoiced or paid on or after 1 October 2026.
InvoicingTax engineE-commerceReporting
Regulation 2026/R-82 (32nd Amendment to the GST Regulation), gazetted 21 September 2026, builds out the GST regime for persons with no permanent place of business in the Maldives who supply inbound tourism products or related agency or booking services under section 15(a)(6) of the GST Act as amended by the Eighth Amendment. New section 3(a-1) requires such persons to apply for GST registration, and to register a new taxable activity, on form MIRA 120 (GST Registration - Overseas Suppliers); new sections 13(c-1) and (c-2) and new section 29-1 set the valuation formula (A-B) x t/(t+1) with a floor of zero; new section 64-1 removes the obligation to show the GST amount and the GST-exclusive price on their tax invoices, receipts, credit notes and debit notes; new section 92(a)(7-1) to (7-7) add seven record-keeping categories; new sections 95(b) and (d) and 97(b) permit records in another language and held outside the Maldives; new sections 105-3 and 105-4 define permanent place of business and the consideration amount; and sections 8, 23, 44(a)(5), 74, 75, 87, 107 and 111 are repealed. New section 99(b) provides that no GST is chargeable on a section 15(a)(6) transaction where the tax invoice, invoice or receipt is prepared, or the consideration or part of it is paid, before 1 October 2026. English wording below is the analyst own translation of the Dhivehi text and is not part of the instrument; the evidence quote is the Thaana original.
What changed in detail
Regulation 2026/R-82 (the 32nd Amendment to the GST Regulation), gazetted 21 September 2026, builds out the GST regime for persons with no permanent place of business in the Maldives who supply inbound tourism products or related agency or booking services under GST Act section 15(a)(6), as amended by the Eighth Amendment.
New section 3(a-1) requires such persons to apply for GST registration, and to register a new taxable activity, on form MIRA 120 (GST Registration - Overseas Suppliers). New sections 13(c-1)/(c-2) and 29-1 set the valuation formula (A-B) x t/(t+1) with a floor of zero. New section 64-1 removes the obligation to show the GST amount and the GST-exclusive price on their invoices, receipts, credit notes and debit notes. New section 92(a)(7-1) to (7-7) add seven record-keeping categories, and new sections 95(b), (d) and 97(b) permit records in another language and held outside the Maldives. New section 99(b) provides that no GST is chargeable on a section 15(a)(6) transaction where the invoice or receipt is prepared, or the consideration paid, before 1 October 2026.
What it means
The registration trigger is the transaction date, not the supplier’s home jurisdiction or size: any non-resident selling inbound Maldives tourism products or booking/agency services around that product needs form MIRA 120 filed ahead of the first in-scope invoice or payment dated on or after 1 October 2026. The section 99(b) carve-out rewards suppliers who invoice or collect payment before that date for the same booking - worth checking against existing forward bookings rather than assumed to only matter for new sales made after commencement.
Proof
މި މާއްދާގެ (ހ) އާއި (ށ) އަށް ޢަމަލުކުރާނީ 31 ޑިސެންބަރު 2026 ގެ ނިޔަލަށެވެ.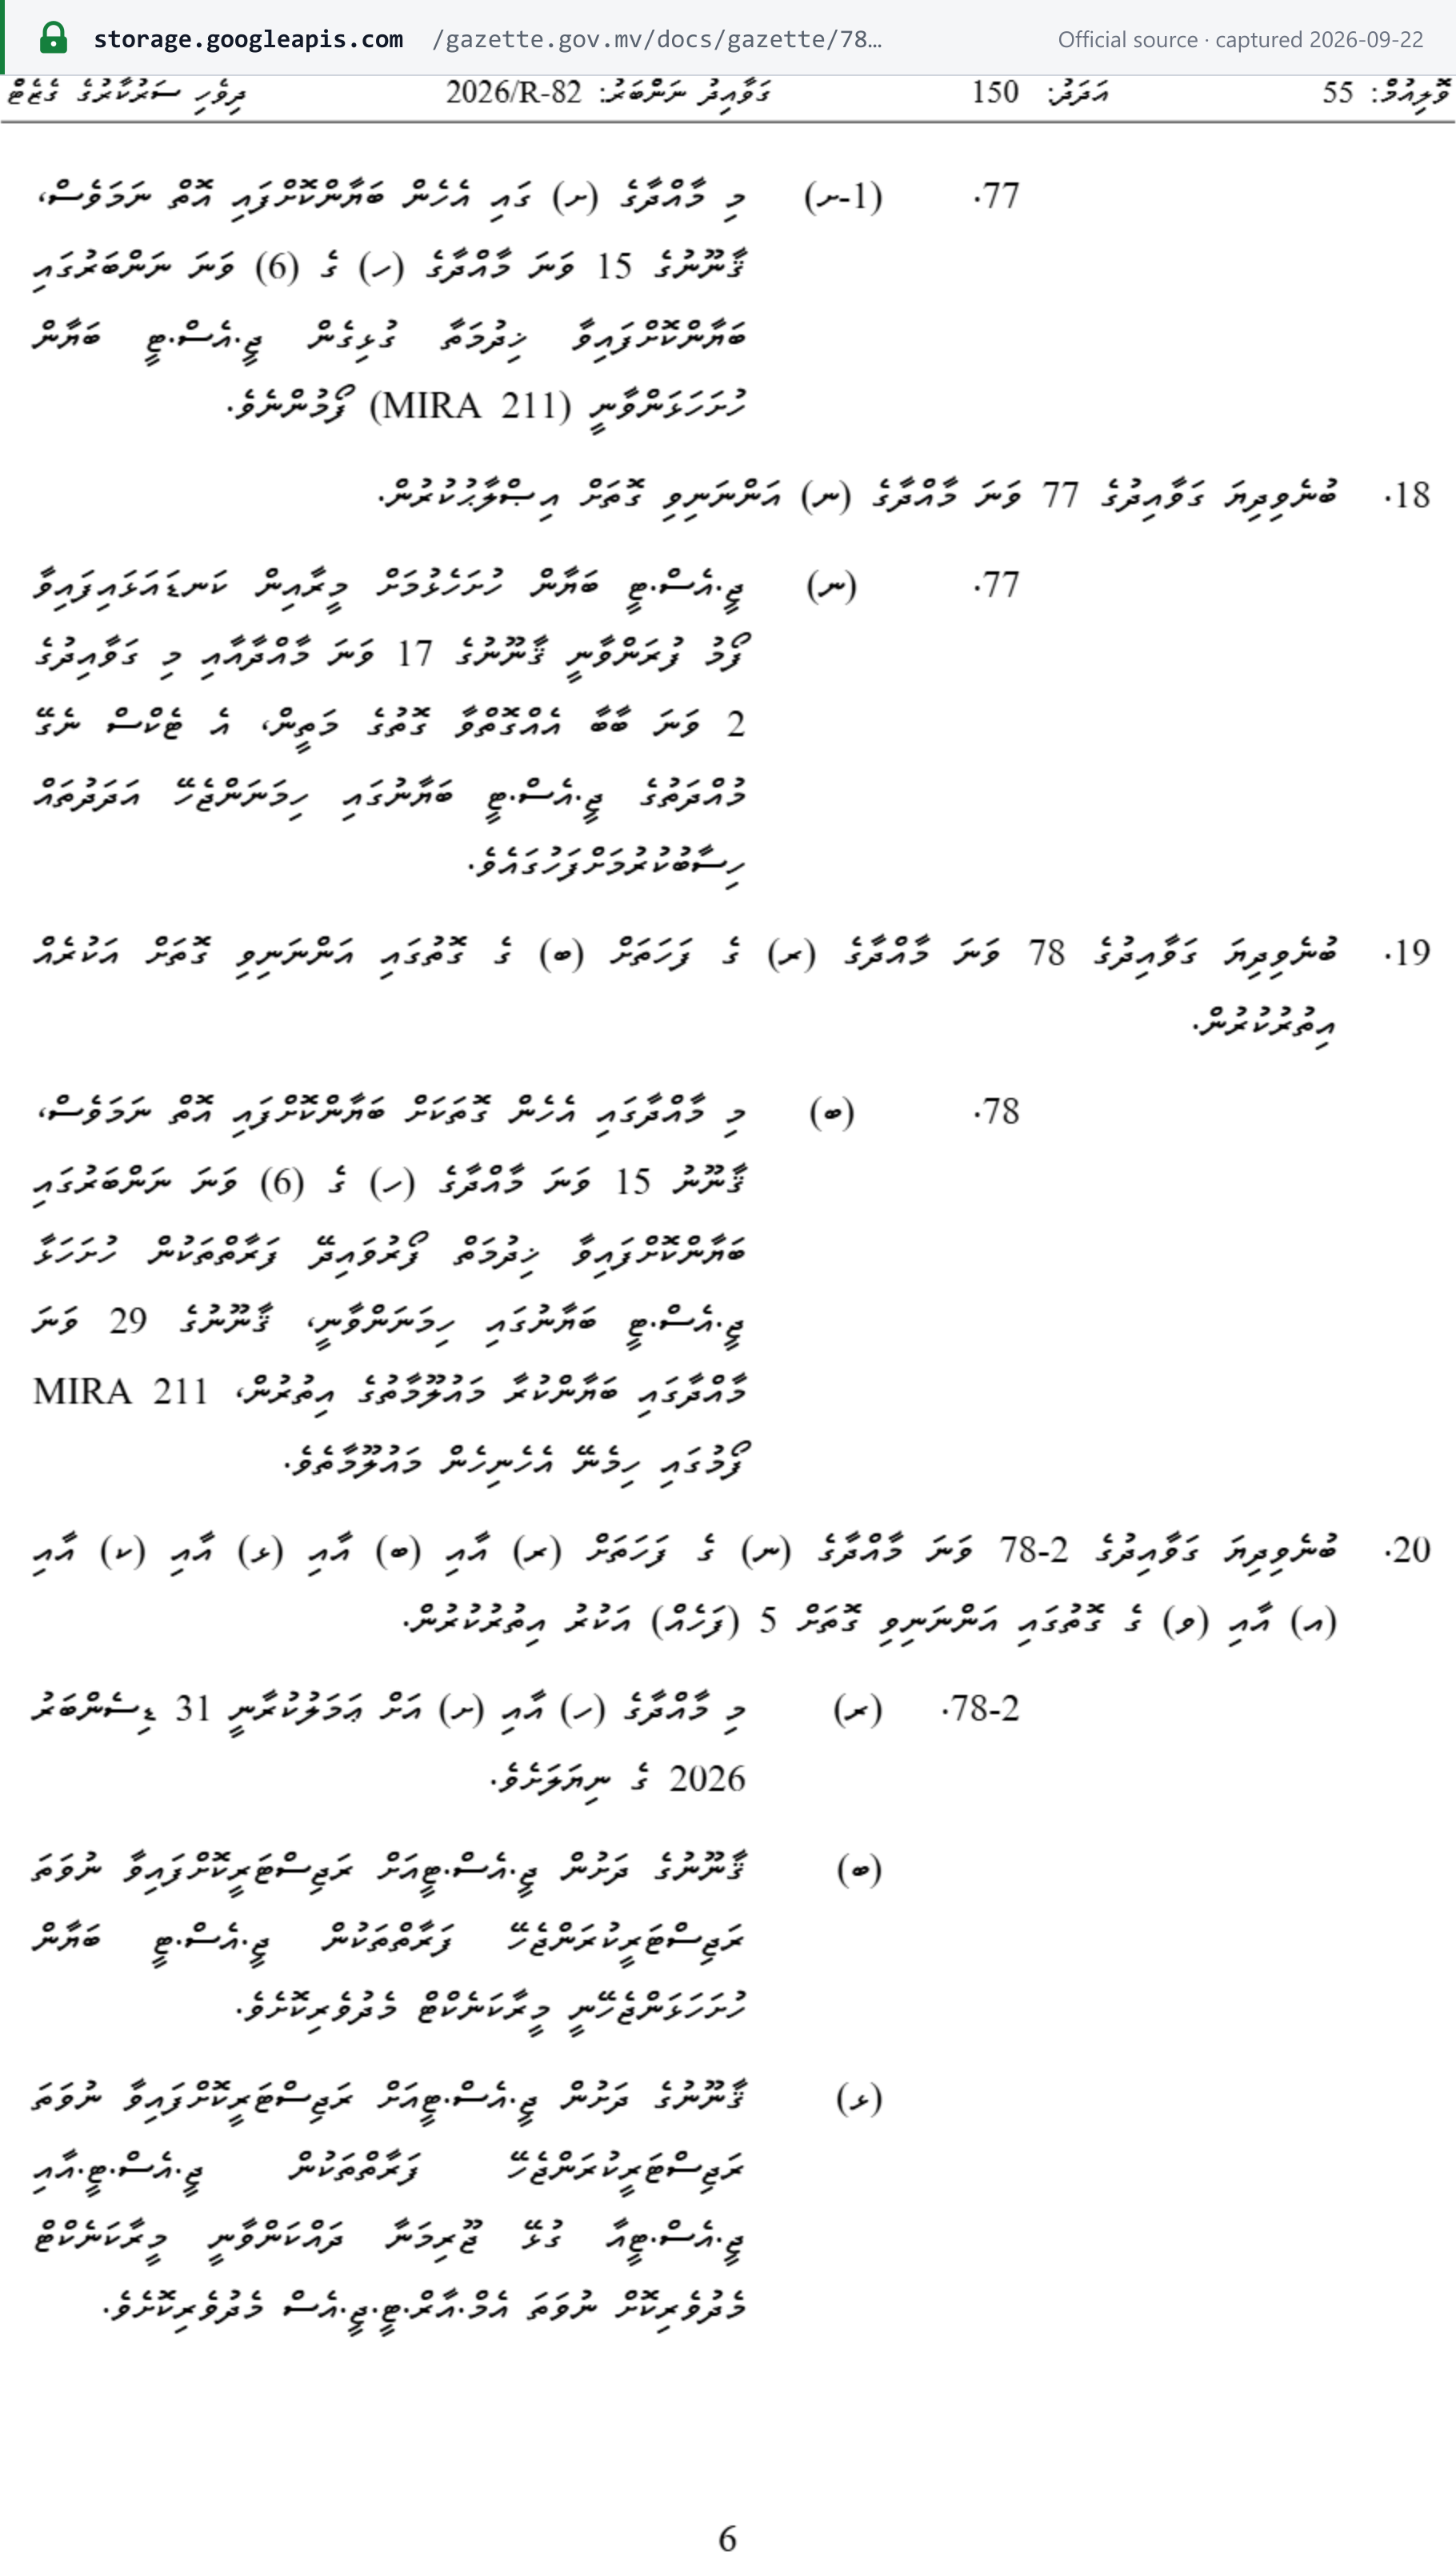 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Regulation 2026/R-82, 32nd Amendment to the GST Regulation - Gazette of Maldives, Volume 55 No. 150, 21 September 2026 · storage.googleapis.com
Sources
- ގަވާއިދު ނަންބަރު 2026/R-82 — ގަވާއިދު ނަންބަރު 2011/R-43 (މުދަލާއި ޚިދުމަތުގެ އަގުން ޓެކްސް ނެގުމުގެ ގަވާއިދު) އަށް 32 ވަނަ އިޞްލާޙު ގެނައުމުގެ ގަވާއިދު (Regulation 2026/R-82, 32nd Amendment to the GST Regulation)
- Gazette entry for Regulation 2026/R-82 (32nd Amendment to the GST Regulation)
- GST Registration - Overseas Suppliers (MIRA 120)