Maldives sets a three-day deadline for issuing a tax invoice or receipt
- Jurisdiction
- Maldives
- Tax
- GST
- Change type
- Invoice rules
- Status
- In force
- Impact
- Plan ahead
- Announced
- 31 August 2026
- Effective
- 31 August 2026
- Authority
- Maldives Inland Revenue Authority (MIRA)
- Systems
- Invoicing, ERP
- Verified
- Fetched from official source · high confidence
Every GST-registered person in the Maldives, on all goods and all services supplied — there is no sector, size or value carve-out in the new subsections.
GST-registered persons in the Maldives should confirm invoicing/billing systems issue a tax invoice or receipt within 3 days of goods removal/availability or service completion, as now required by law.
InvoicingERP
The same Eighth Amendment to the Goods and Services Tax Act (Law No. 10/2026, gazetted 31 August 2026) inserts a mandatory tax invoice/receipt issuance deadline: registered persons must issue a tax invoice or receipt within 3 days of goods being removed from (or made available at) the place of supply, and within 3 days of completion of services. If not issued within that period, the invoice/receipt is deemed issued on the date the period expires, for time-of-supply purposes. The Act commences from the date of its Gazette publication, i.e. 31 August 2026.
What changed in detail
The Eighth Amendment to the Goods and Services Tax Act (Law Number 10/2011), Law No. 10/2026, was passed on 26 August 2026 and published in the Government Gazette on ratification by the President on 31 August 2026. Clause 31 commences the Act on that publication date, so the invoicing rule below has applied since then.
Clause 13 inserts three new subsections after section 17(c) of the GST Act.
Section 17(d) requires a registered person to issue a tax invoice or receipt within three days of, for all goods supplied: the date the goods are removed from the place of supply; or, where they are not removed, the date they are made available to the recipient. Section 17(e) applies the same three-day limit to all services supplied, running from the date the services are completed.
Section 17(f) makes the deadline self-executing. Where no invoice or receipt is issued within the period set by subsection (d) or (e), then for the purposes of determining the time of supply under section 17, one is deemed issued on the date that period expires.
The obligation is expressed across all goods and all services of a registered person, with no threshold, sector or document-type exception in the inserted text.
What it means
Before this, late invoicing mostly deferred the tax point. Section 17(f) removes that: the time of supply now moves whether or not the paperwork does, so a document issued on day ten can land in an earlier taxable period than the date printed on it. The practical failure mode is not a penalty — it is a return that omits supplies MIRA considers already taxable.
Three days is short enough that it is a systems constraint rather than a policy one. Month-end consolidated billing, progress invoicing agreed in a contract, and any approval workflow that sits between service completion and invoice release are all now capable of breaching it while the business believes it is compliant. The controls worth having are a report of supplies with no document within three days, and a check that “completion of services” is a date the system actually records — for many service businesses it is not captured anywhere.
Proof
(d) A registered person shall issue a tax invoice or receipt within 3 (three) days of the following dates, in respect of all goods supplied: (1) Where the goods are removed from the place of supply, the date on which such goods are removed; (2) Where the goods are not removed from the place of supply, the date on which such goods are made available to the recipient. (e) A registered person shall issue a tax invoice or receipt within 3 (three) days from the date of completion of services, in respect of all services supplied. (f) Even if a tax invoice or receipt is not issued within the period specified in subsection (d) or (e), for the purposes of determining the time of supply under Section 17 of the Act, it shall be deemed that a tax invoice or receipt is issued on the date of expiration of that period.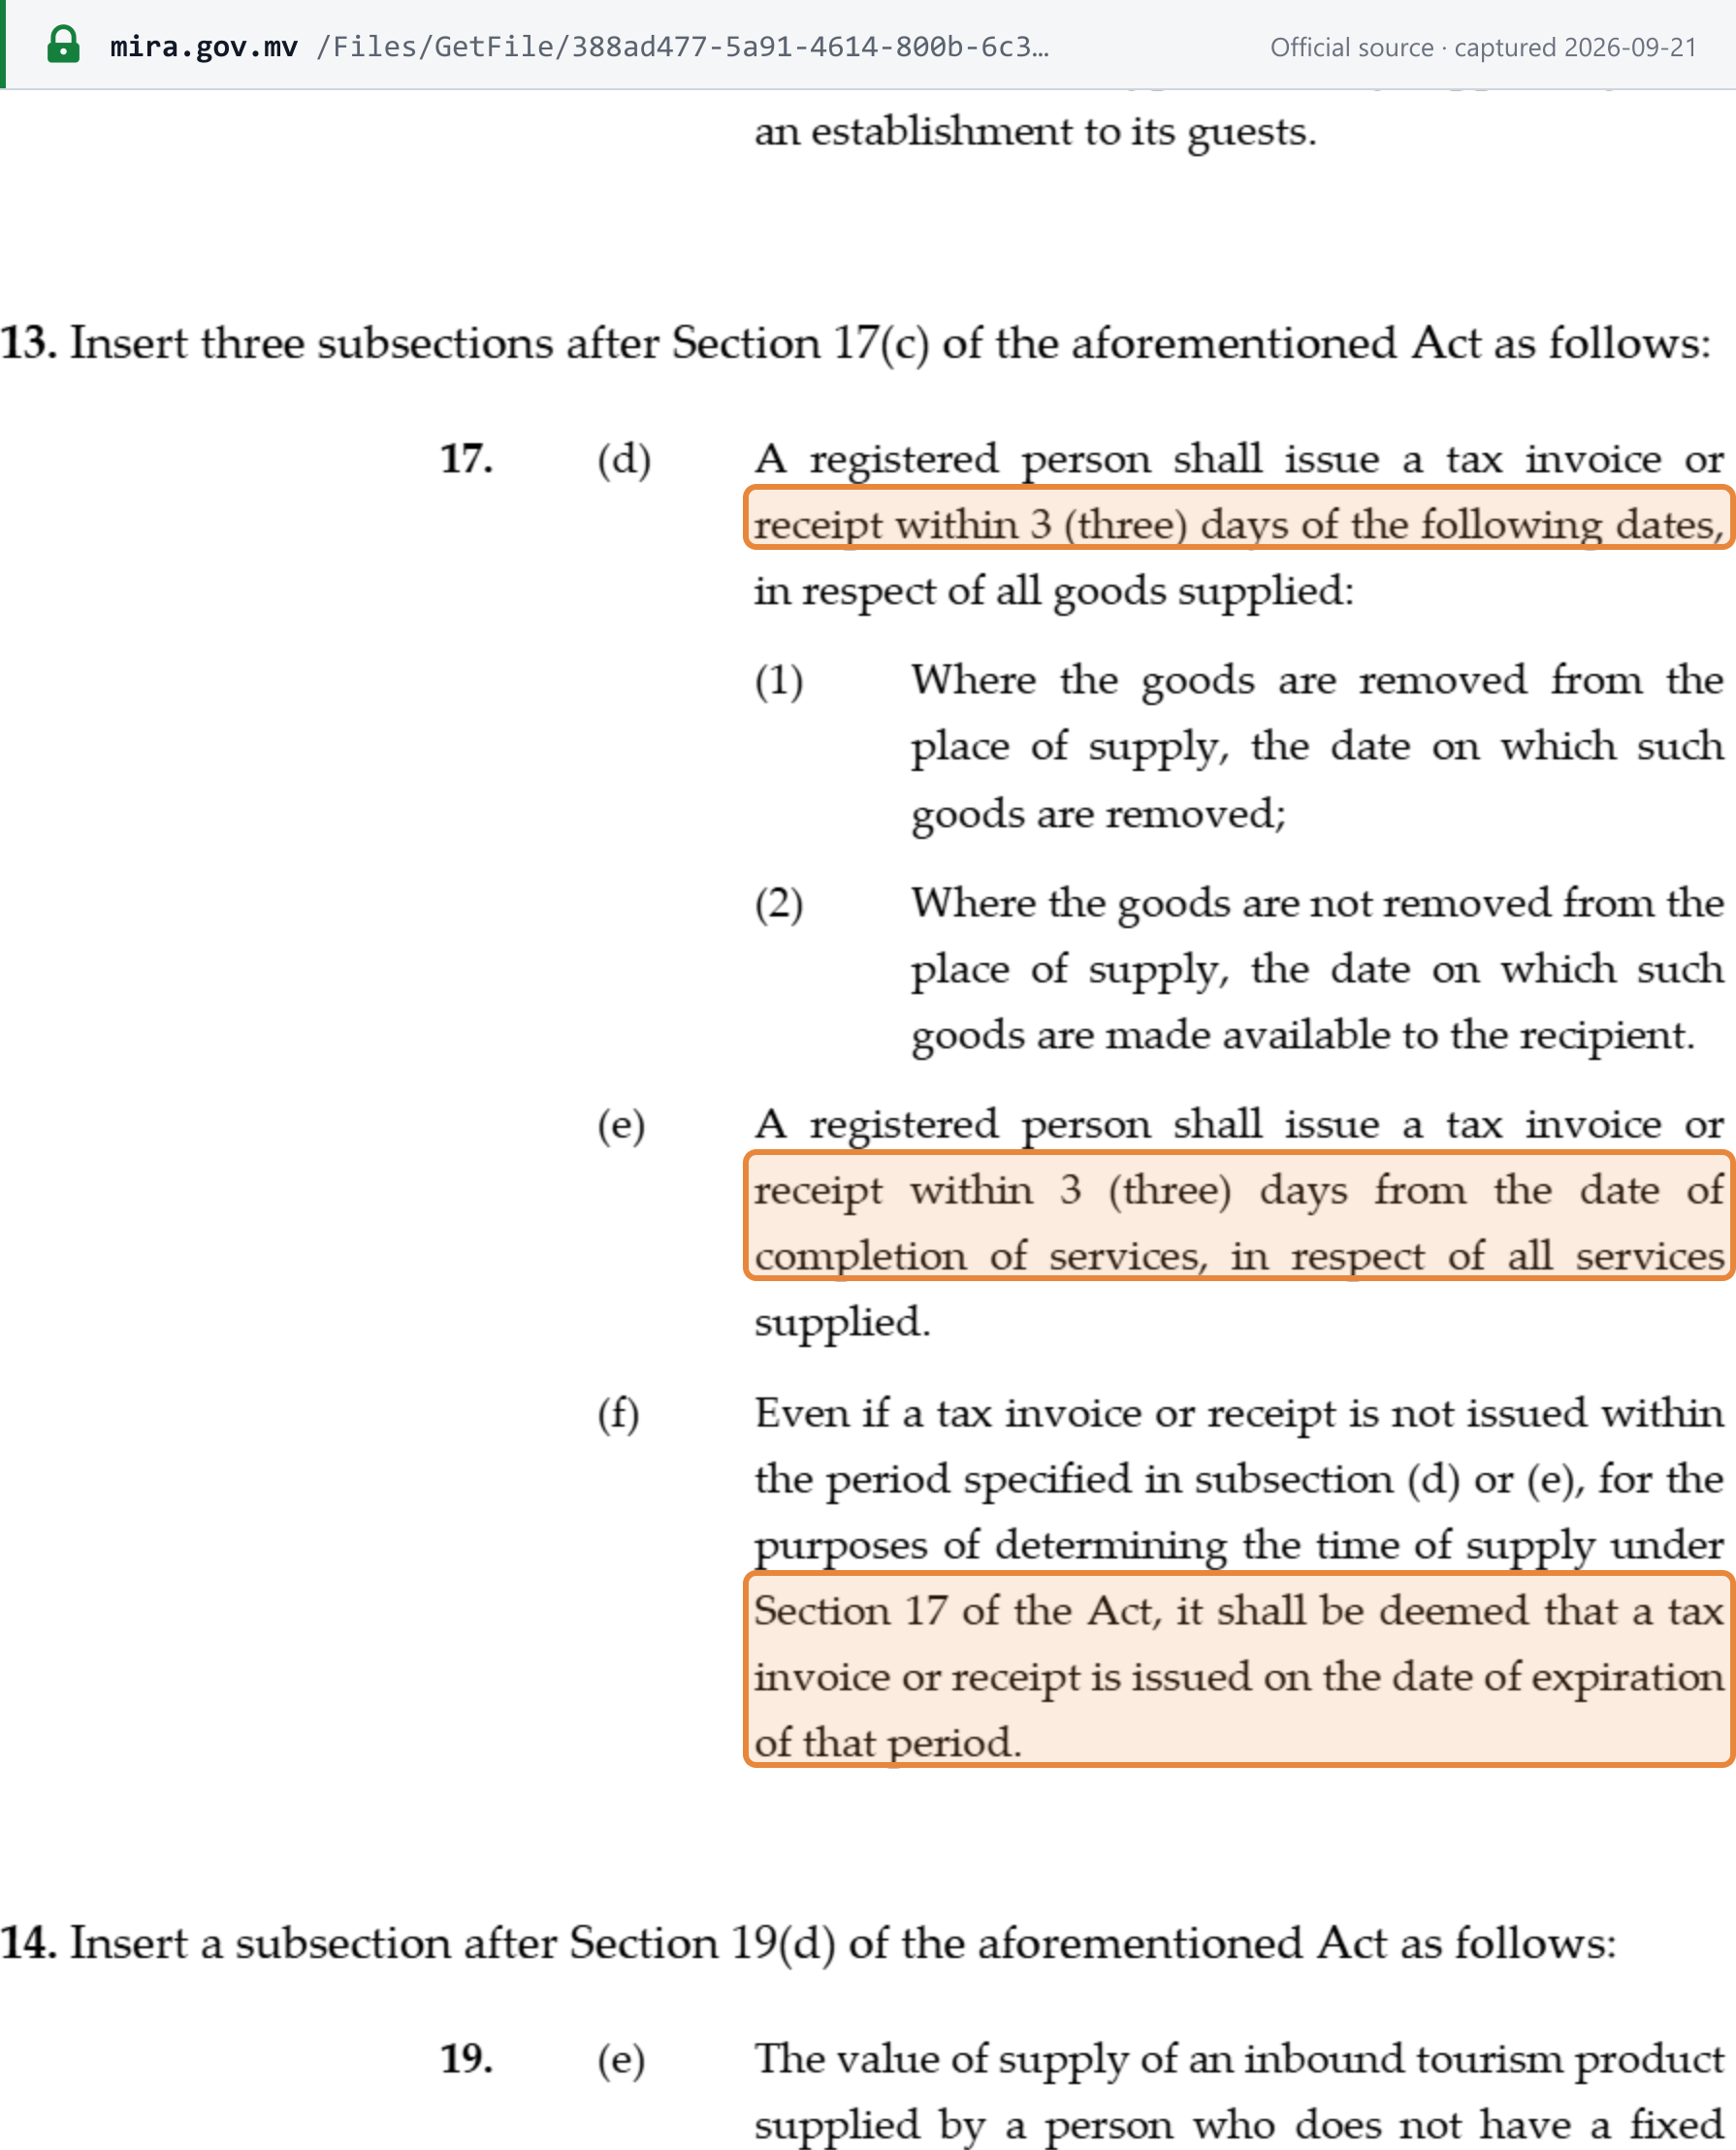 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Eighth Amendment to the Goods and Services Tax Act (Law Number 10/2011), Law No. 10/2026 — MIRA unofficial English translation, clause 13 (p.7 of 13) · www.mira.gov.mv
This Act shall commence from the date of its publication in the Government Gazette following its passing and ratification.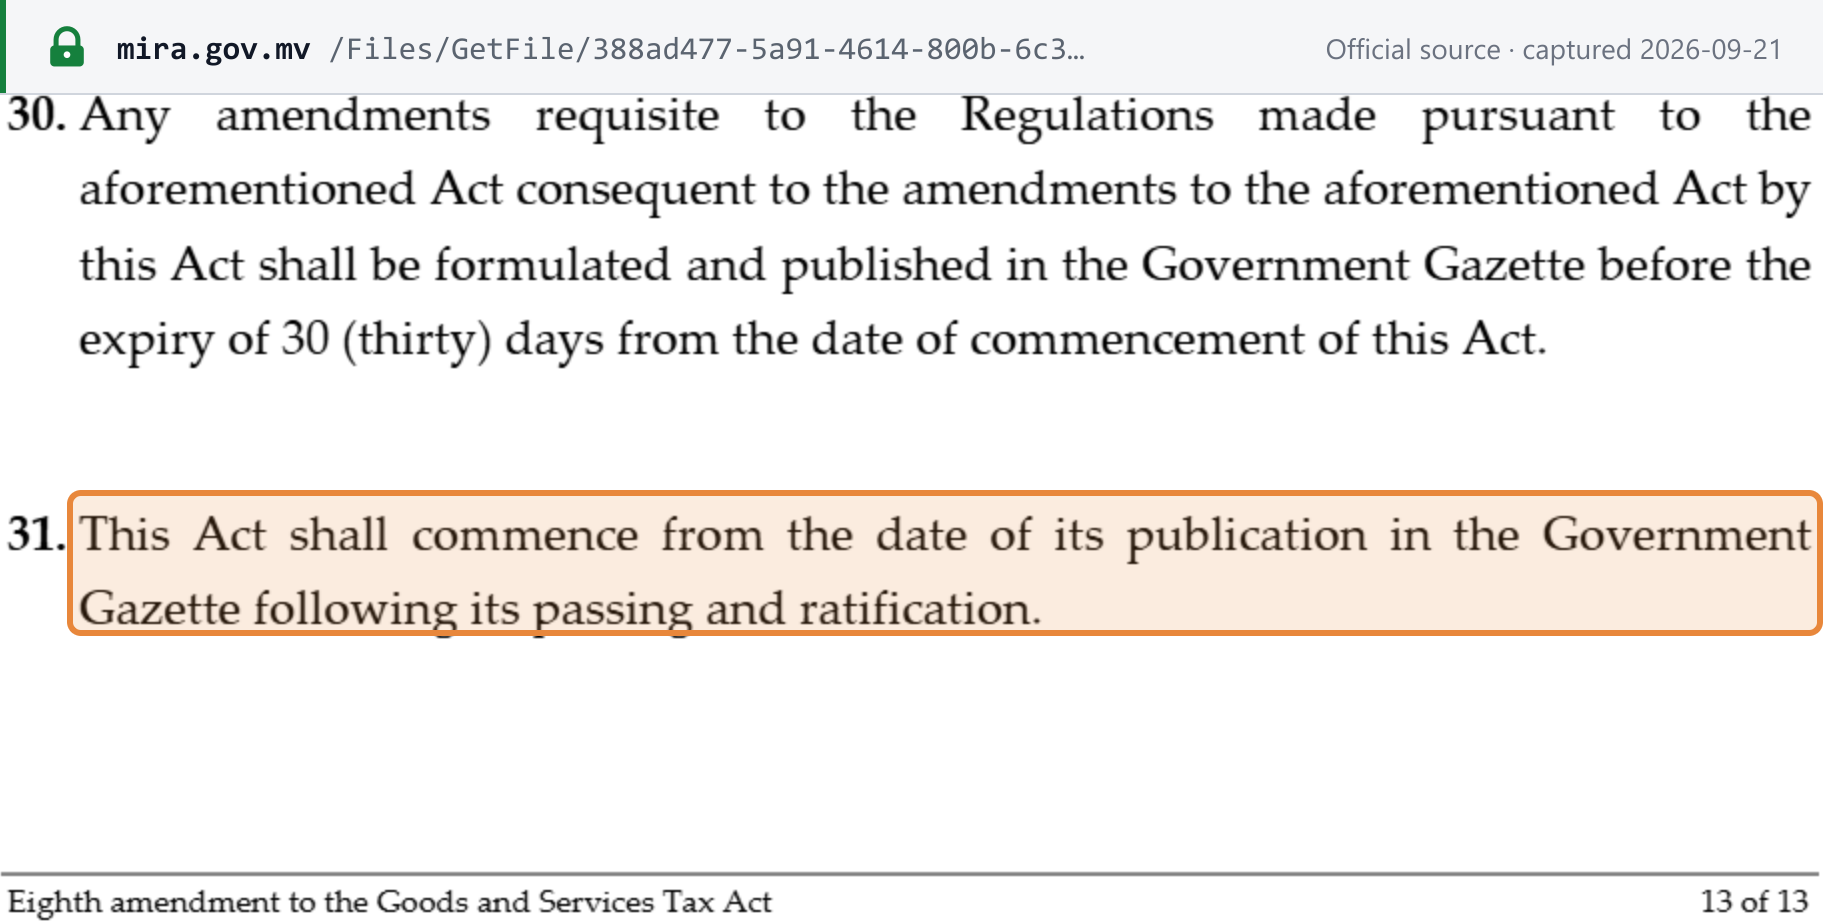 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Eighth Amendment to the Goods and Services Tax Act, Law No. 10/2026 — clause 31, commencement (p.13 of 13) · www.mira.gov.mv