Mauritius drops the local tax-representative requirement for foreign digital-service suppliers
This page records one dated change. For the rules in Mauritius as they stand today, see the Mauritius guide →
- Jurisdiction
- Mauritius
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- Plan ahead
- Announced
- 13 August 2026
- Effective
- 13 August 2026
- Authority
- Mauritius Revenue Authority
- Systems
- Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Foreign suppliers of digital or electronic services to Mauritius that fall within VAT Act section 14A — in particular those that had appointed a Mauritius-established tax representative because their turnover exceeded the Sixth Schedule threshold.
Foreign suppliers of digital/electronic services to Mauritius that previously appointed a local tax representative under VAT Act s.14A(2) should confirm they may now file and remit VAT directly, without a Mauritius-established representative.
Tax engineReporting
Section 25(f) of the Finance Act 2026 (Act No. 14 of 2026, assented 12 August 2026, gazetted 13 August 2026) amends VAT Act section 14A (foreign supplier of digital/electronic services). It repeals subsection (2), which had required a foreign supplier whose turnover exceeded the Sixth Schedule threshold to appoint a locally-established tax representative; it amends subsection (3) so that filing returns and remitting VAT is now the direct responsibility of 'the foreign supplier' rather than a tax representative; and it repeals subsection (5). This section is not among the sections given a specific commencement date in section 28 of the Act, so (consistent with other un-scheduled VAT Act amendments in the same Act, e.g. ss.25(j),(u)) it takes effect on the Act's gazettal date.
What changed in detail
The Finance Act 2026 (Act No. 14 of 2026) was passed by the National Assembly on 31 July 2026, assented to by the President on 12 August 2026 and published on 13 August 2026. Section 25 of the Act amends the Value Added Tax Act 1998.
Paragraph (f) of section 25 rewrites section 14A, the provision governing a foreign supplier of digital or electronic services. It does three things. It repeals subsection (2), which had required a foreign supplier whose turnover exceeded the amount specified in the Sixth Schedule to appoint a tax representative established in Mauritius. It amends subsection (3), replacing the words “The tax representative appointed under subsection (2)” with “The foreign supplier”, so the duty to submit returns and pay the tax now rests on the supplier itself. And it repeals subsection (5).
Section 28 of the Act schedules specific commencement dates for a number of the section 25 paragraphs — 25(b), (c), (e), (g), (h), (i) and (r)(xiii) on 1 October 2026, 25(t)(iii) on 1 July 2026, 25(p) and (q) on 1 January 2027, and 25(t)(ii) on 27 April 2026. Paragraph (f) is not among them, so it takes effect on the Act’s own commencement, the date of publication: 13 August 2026.
What it means
The intermediary goes; the obligation does not. A foreign supplier that was filing through a Mauritius-established representative is now the filer and payer of record itself, and the representative’s removal does not change registration status, return frequency or the tax due. What it changes is who the MRA looks at when a return is late.
Two housekeeping consequences follow. Standing appointments and powers of attorney given to a local representative are now redundant, and are worth unwinding deliberately rather than letting lapse — they usually carry indemnities and fee tails. And any process that routed MRA correspondence through the representative needs a new address, because the Act does not provide one.
Note that a separate paragraph of the same section, 25(g), narrows the section 15 registration test from 1 October 2026. Confirm registration status against that change before relying on this one.
Proof
in section 14A – (i) by repealing subsection (2); (ii) in subsection (3), by deleting the words "The tax representative appointed under subsection (2)" and replacing them by the words "The foreign supplier"; (iii) by repealing subsection (5);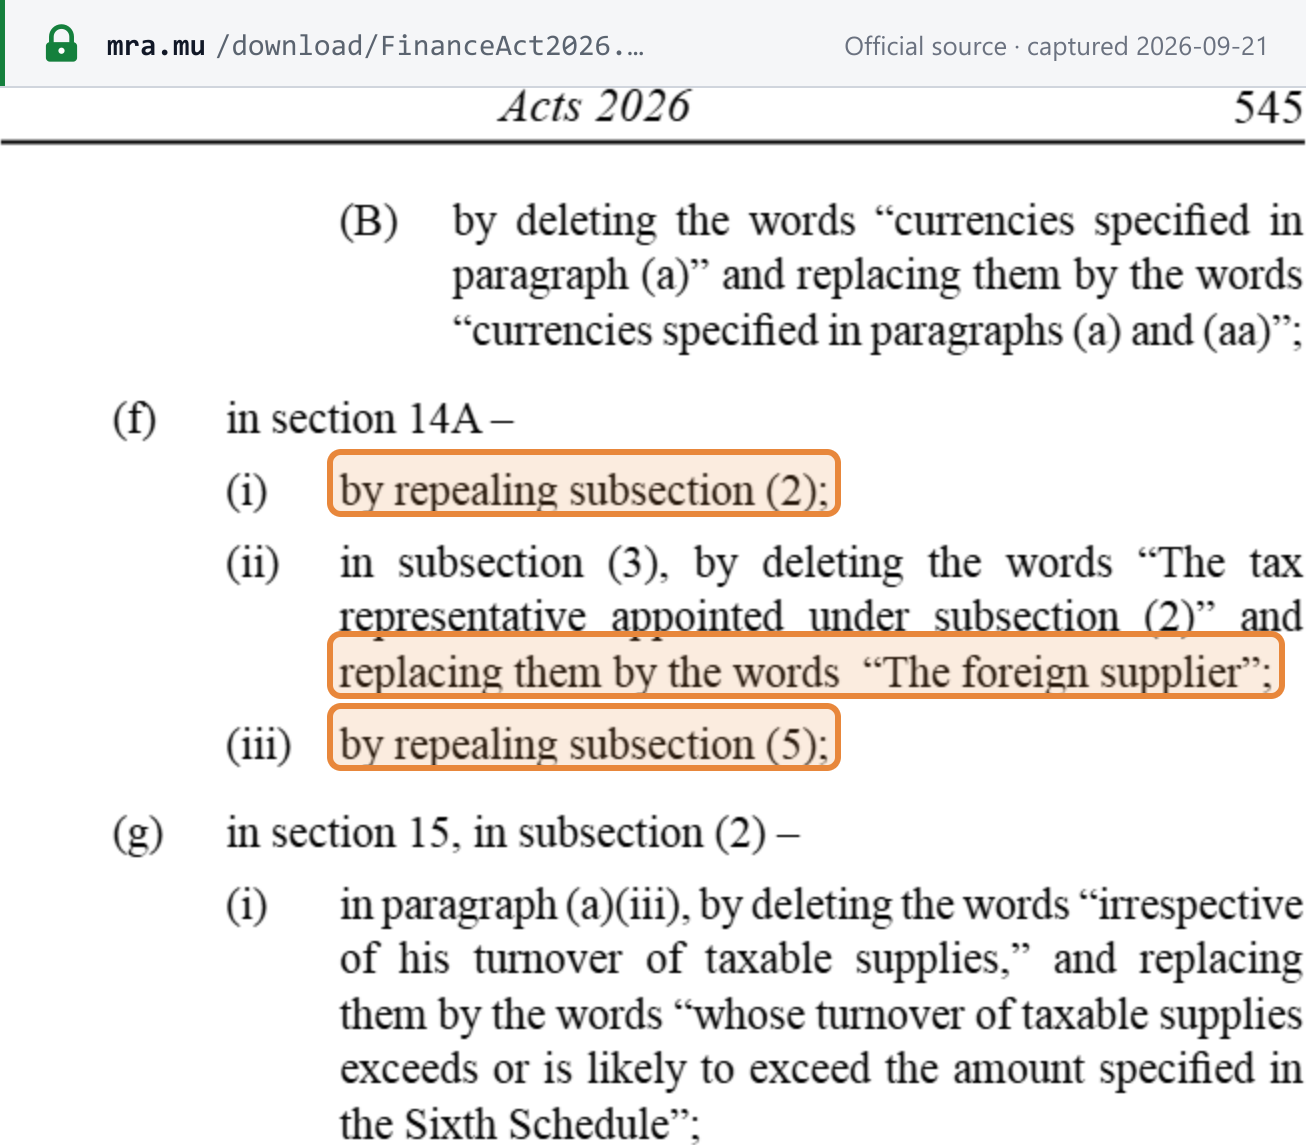 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · The Finance Act 2026 (Act No. 14 of 2026), Mauritius — Acts 2026 p.545, s.25(f) · www.mra.mu