Mauritius extends the banking VAT exemption to licensed payment service providers
This page records one dated change. For the rules in Mauritius as they stand today, see the Mauritius guide →
- Jurisdiction
- Mauritius
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Plan ahead
- Announced
- 13 August 2026
- Effective
- 13 August 2026
- Authority
- Mauritius Revenue Authority
- Systems
- Tax engine
- Verified
- Fetched from official source · high confidence
Payment service providers licensed and regulated by the Bank of Mauritius under the National Payment Systems Act, on services supplied to non-residents and to corporations holding a Global Business Licence.
Licensed payment service providers regulated under Mauritius's National Payment Systems Act should review whether services supplied to non-residents or Global Business Licence corporations now qualify for VAT exemption under the amended Fifth Schedule item 6.
Tax engine
Section 25(s)(ii) of the Finance Act 2026 (Act No. 14 of 2026) repeals and replaces item 6(2) of the Fifth Schedule to the VAT Act. Previously only banks holding a Banking Act licence were VAT-exempt on banking transactions with non-residents and Global Business Licence corporations; the new item 6(2) extends the same exemption to a payment service provider (PSP) licensed and regulated by the Bank of Mauritius under the National Payment Systems Act, for services to non-residents and Global Business Licence corporations. Not listed in section 28's specific commencement clauses, so it defaults to the Act's gazettal date.
What changed in detail
The Finance Act 2026 (Act No. 14 of 2026), assented to on 12 August 2026 and published on 13 August 2026, amends the Value Added Tax Act 1998 at section 25. Paragraph (s)(ii) repeals paragraph (2) of item 6 of the Fifth Schedule — the schedule of exempt supplies — and replaces it.
The repealed paragraph covered only banks. Under the replacement, item 6(2) exempts the supply of services (a) by a bank holding a banking licence under the Banking Act, in respect of its banking transactions with non-residents and corporations holding a Global Business Licence under the Financial Services Act; or (b) by a payment service provider (“PSP”) licensed and regulated by the Bank of Mauritius under the National Payment Systems Act, to non-residents and to corporations holding a Global Business Licence issued by the Financial Services Commission established under the Financial Services Act.
Limb (a) restates the previous position. Limb (b) is new. The test in both is the customer: non-residents and Global Business Licence corporations.
Section 28 of the Act gives specific commencement dates to several paragraphs of section 25 — (b), (c), (e), (g), (h), (i) and (r)(xiii) on 1 October 2026, among others — but not to paragraph (s)(ii). It therefore takes effect on the Act’s publication date, 13 August 2026.
What it means
This is an exemption, not a zero rate, and the difference is the whole commercial point. A PSP that moves qualifying supplies out of the standard rate also moves the related input tax out of recovery, so a provider with a mixed book now has a partial-exemption apportionment to run where it previously had a fully taxable one. For a PSP selling almost entirely to non-residents and Global Business Licence corporations, the net effect can be worse, not better.
Two scope questions decide whether a supply qualifies, and neither is about the service. The first is the licence: only a Bank of Mauritius licence under the National Payment Systems Act counts. The second is the customer’s status at the time of supply — residence, or a live Global Business Licence. That makes customer-status evidence, not product classification, the thing to get into the billing system.
Proof
(ii) in item 6, by repealing paragraph (2) and replacing it by the following paragraph – (2) The supply of services – (a) by a bank holding a banking licence under the Banking Act in respect of its banking transactions with non-residents and corporations holding a Global Business Licence under the Financial Services Act; or (b) a payment service provider ('PSP'), licensed and regulated by the Bank of Mauritius under the National Payment Systems Act, to non-residents and corporations holding a Global Business Licence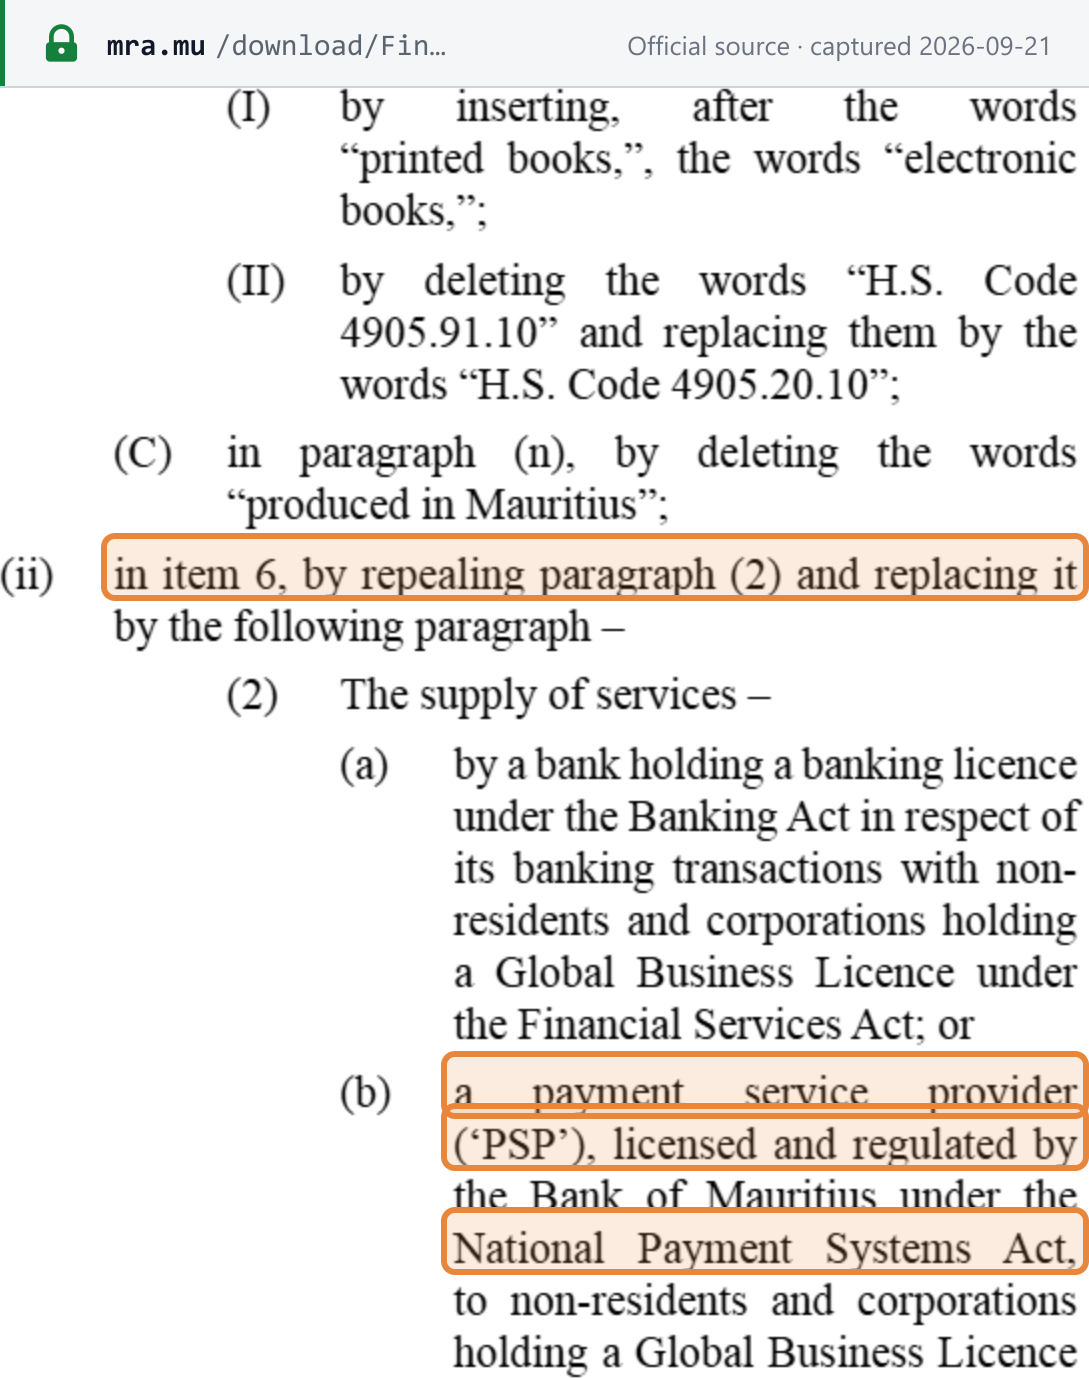 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · The Finance Act 2026 (Act No. 14 of 2026), Mauritius — Acts 2026 pp.551-552, s.25(s)(ii) · www.mra.mu