Mauritius: services by management licence holders to offshore clients are VAT-exempt from 1 October 2026, zero-rated before
This page records one dated change. For the rules in Mauritius as they stand today, see the Mauritius guide →
- Jurisdiction
- Mauritius
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Plan ahead
- Announced
- 2 October 2026
- Effective
- 1 October 2026
- Authority
- Mauritius Revenue Authority
- Systems
- Invoicing, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Holders of a management licence under the Financial Services Act that supply services to Global Business Licence corporations, non-resident trusts and non-resident foundations.
Treat management-licence services to GBC, non-resident trusts and foundations as exempt from 1 October 2026 and keep pre-October invoices zero-rated.
InvoicingTax engineReporting
The Mauritius Revenue Authority communique of 2 October 2026 states that supplies of services by a holder of a management licence under the Financial Services Act to Global Business Licence corporations, to trusts whose settlor and majority of beneficiaries are non-residents, and to foundations whose founder and majority of beneficiaries are non-residents are exempt under item 97 of the First Schedule to the VAT Act from 1 October 2026, and that such supplies made before 1 October 2026 qualify as zero-rated.
What changed in detail
A Mauritius Revenue Authority communiqué of 2 October 2026 sets out the VAT treatment of services supplied by the holder of a management licence under the Financial Services Act. Supplies to the following are an exempt supply under item 97 of the First Schedule to the VAT Act with effect from 1 October 2026:
- corporations holding a Global Business Licence;
- trusts whose settlor and the majority of whose beneficiaries are non-residents;
- foundations whose founder and the majority of whose beneficiaries are non-residents.
The communiqué adds that such supplies made before 1 October 2026 qualify as zero-rated.
What it means
The change is from zero-rating to exemption. A zero-rated supplier can recover the input VAT it pays on its costs; an exempt supplier generally cannot, so licence holders should expect irrecoverable input VAT on supplies made from 1 October 2026. Supplies made before that date keep zero-rated treatment, so invoices and returns need to be split at the cut-off.
Proof
is an exempt supply under item 97 of the First Schedule to the VAT Act with effect from 01 October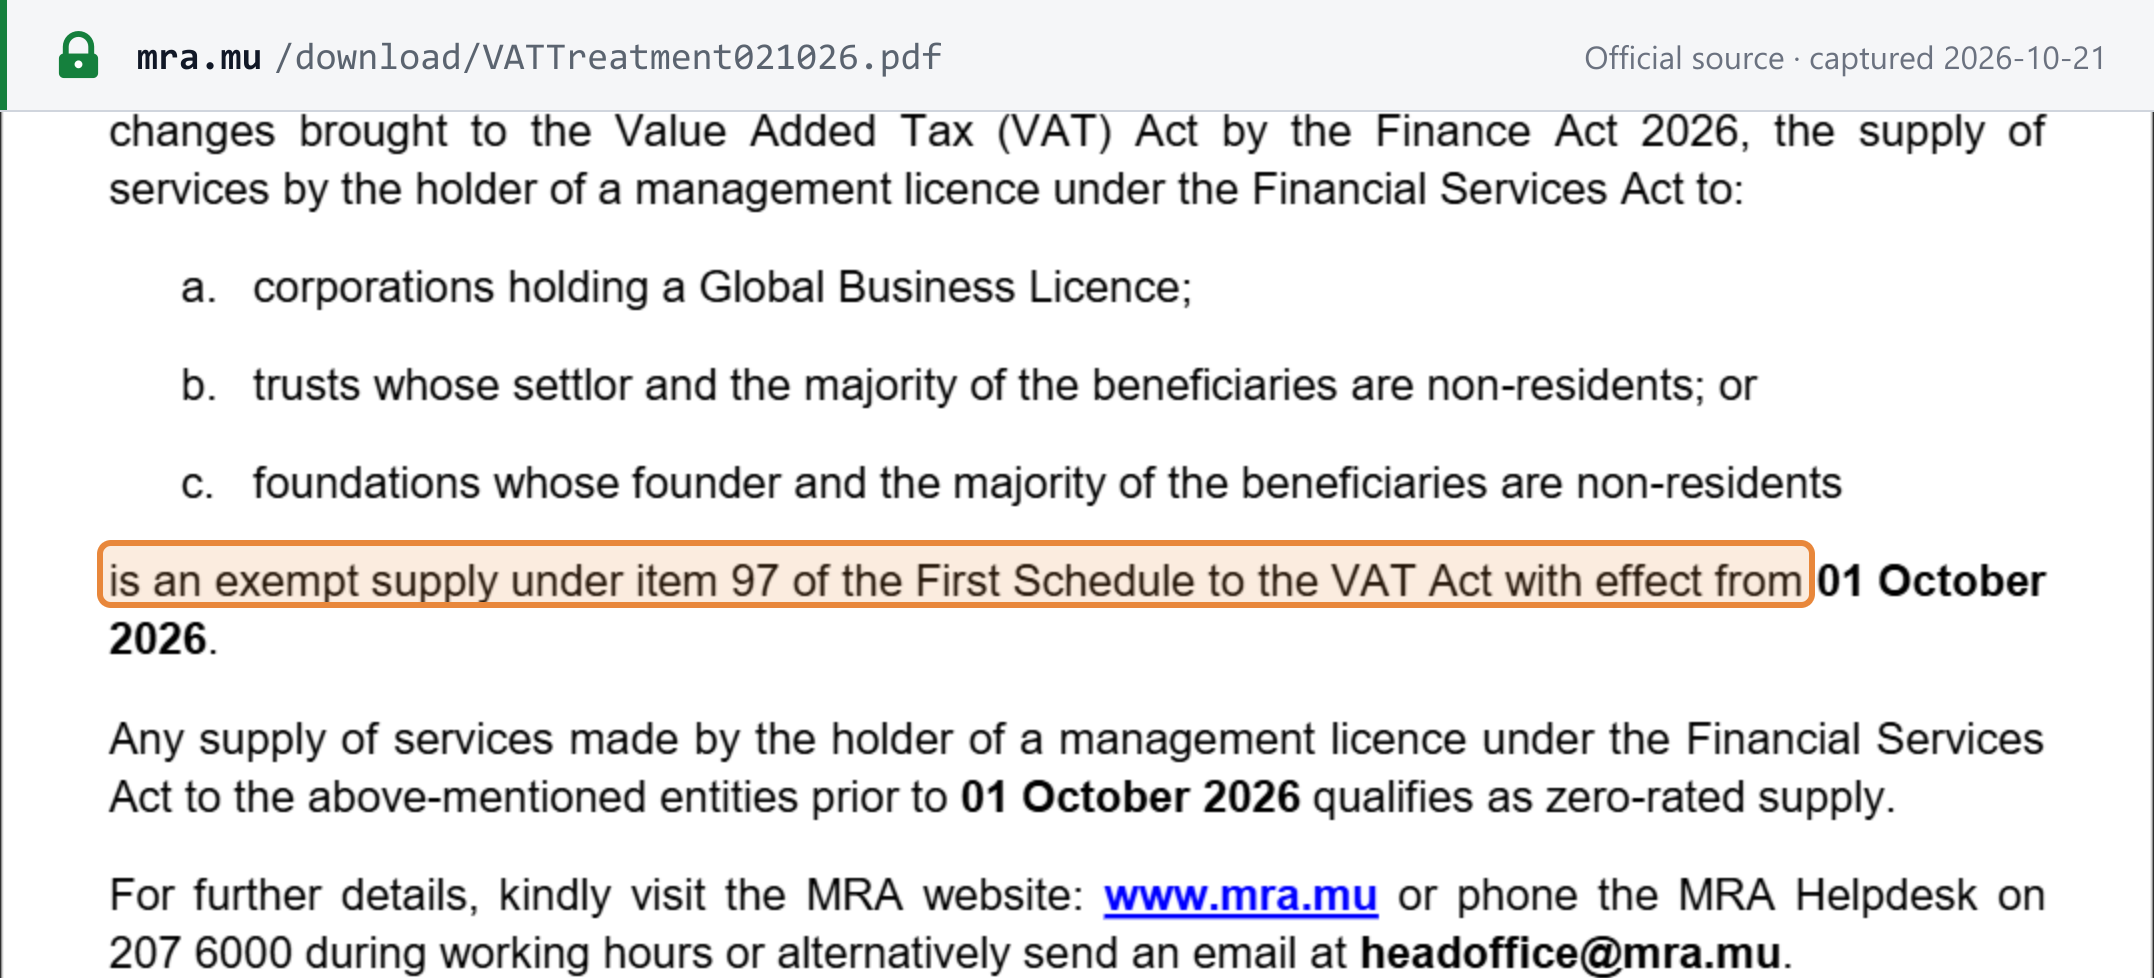 Source snapshot of the official page. Open full size ↗