Nepal's 5% VAT on ride-sharing and on electricity to end consumers applies from 17 July 2026 (Finance Act 2083)
This page records one dated change. For the rules in Nepal as they stand today, see the Nepal guide →
- Jurisdiction
- Nepal
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Announced
- 14 July 2026
- Effective
- 17 July 2026
- Authority
- Inland Revenue Department, Nepal
- Systems
- Tax engine, Invoicing, E-commerce
- Verified
- Fetched from official source · medium confidence
Resident ride-sharing operators in Nepal and the drivers affiliated to their platforms, and persons supplying electricity services to end consumers.
Ride-sharing operators should confirm VAT at 5 per cent of fare value is collected from 17 July 2026 and reconcile any June-dated assumptions.
Tax engineInvoicingE-commerce
Correction of record: Nepal's Finance Act (Arthik Ain) 2083 was published in the Nepal Gazette (Part 2, Vol. 76, Extra No. 29) on 30 Asar 2083 BS, which is 14 July 2026, not 15 June 2026. It inserts sub-section (1Kha) in section 7 of the VAT Act 2052 (via section 55(1)(Ka)), under which a resident ride-sharing operator must assess and collect VAT at 5 per cent of the taxable value on transport and delivery services supplied through its platform by affiliated drivers; the same sub-section applies the 5 per cent to electricity services supplied to end consumers. Section 1(2) of the Act brings section 55(1)(Ka)(1Kha) into force from Shrawan 1, 2083 BS (17 July 2026), not on publication. The Inland Revenue Department decided on 2083/03/31 BS (15 July 2026, not 14-15 June) to issue the public notice on VAT in ride-sharing services; the notice is dated 31 Asar 2083.
What changed in detail
Nepal’s Finance Act (Arthik Ain) 2083, Act No. 10 of 2083, was published in the Nepal Gazette (Part 2, Volume 76, Extraordinary No. 29) on 30 Asar 2083, which is 14 July 2026.
Section 55(1)(Ka) of the Act inserts a new sub-section (1Kha) into section 7 of the Value Added Tax Act 2052. Under it, a resident ride-sharing operator must assess and collect VAT at 5 per cent of the taxable value when transacting with the drivers affiliated to its platform who provide transport and delivery services. The same sub-section applies the 5 per cent to persons supplying electricity services to end consumers.
Section 1(2) of the Act brings sub-clause (1Kha) into force from Shrawan (Saun) 1, 2083 — 17 July 2026 — rather than on publication. Most other sub-sections of section 55 took effect immediately.
The Inland Revenue Department decided on 2083/03/31 (15 July 2026) to issue a public notice on VAT in ride-sharing services. The notice is dated 31 Asar 2083.
This corrects the earlier record, np-vat-section-7-1kha-2026. That record gave 15 June 2026 as the effective date and converted the IRD decision date of 2083/03/31 to about 14–15 June 2026. It also did not state the 5 per cent rate, the electricity limb, or the separate commencement date. The correct dates are 14 July 2026 for publication, 15 July 2026 for the IRD decision and 17 July 2026 for commencement.
What it means
For ride-sharing operators the date that matters is 17 July 2026, not June. Collection systems and reconciliations built around a June start should be checked: fares before 17 July fall outside the new sub-section.
The electricity limb is easy to miss, because the sub-section reads as a ride-sharing provision. A supplier of electricity to end consumers is covered by the same 5 per cent rule and should check its billing.
Bikram Sambat dates convert to slightly different Gregorian dates each year. Anchor compliance calendars to the gazette date rather than to a rule of thumb.
Proof
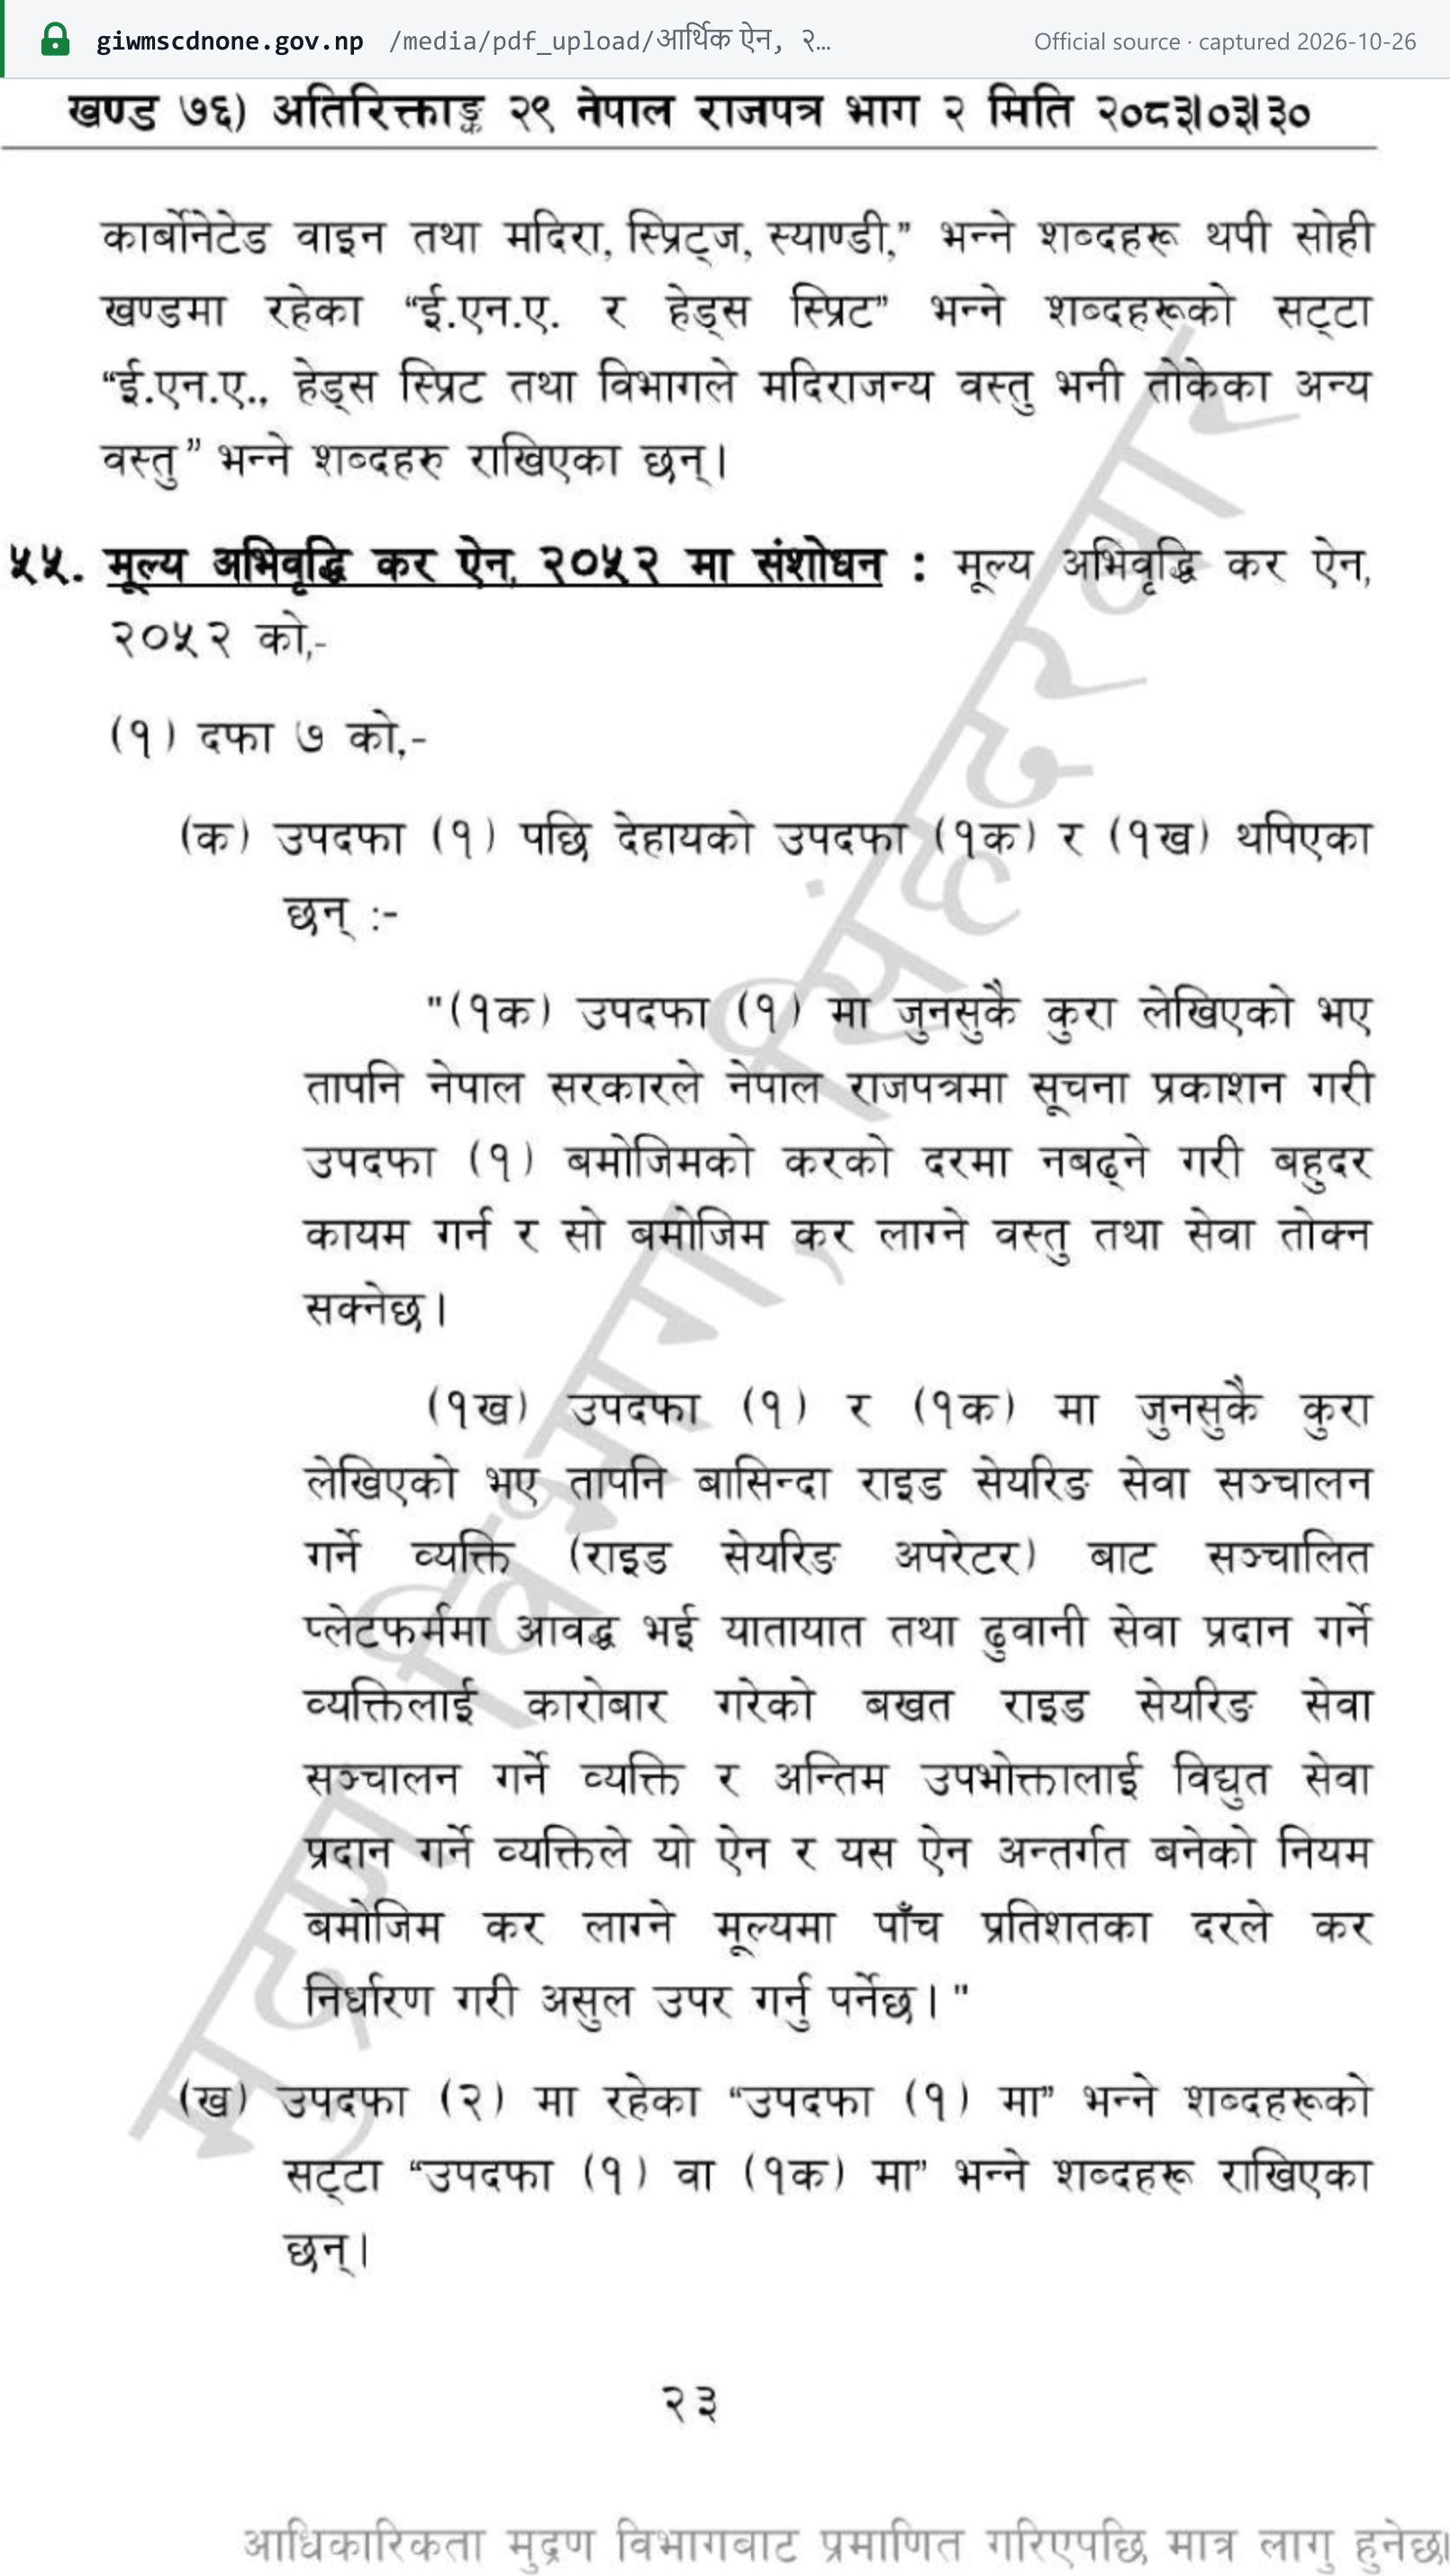
(१ख) उपदफा (१) र (१क) मा जुनसुकै कुरा लेखिएको भए तापनि बासिन्दा राइड सेयरिङ सेवा सञ्चालन गर्ने व्यक्ति (राइड सेयरिङ अपरेटर) बाट सञ्चालित प्लेटफर्ममा आवद्ध भई यातायात तथा ढुवानी सेवा प्रदान गर्ने व्यक्तिलाई कारोबार गरेको बखत राइड सेयरिङ सेवा सञ्चालन गर्ने व्यक्ति र अन्तिम उपभोक्तालाई विद्युत सेवा प्रदान गर्ने व्यक्तिले यो ऐन र यस ऐन अन्तर्गत बनेको नियम बमोजिम कर लाग्ने मूल्यमा पाँच प्रतिशतका दरले कर निर्धारण गरी असुल उपर गर्नु पर्नेछ।(1Kha) Notwithstanding anything contained in sub-sections (1) and (1Ka), the person operating a resident ride-sharing service (ride-sharing operator), when transacting with a person who provides transport and delivery services affiliated to the platform it operates, and a person who provides electricity services to end consumers, shall assess and collect tax at the rate of five per cent of the taxable value in accordance with this Act and the rules made under it.
 Source snapshot of the official page. Open full size ↗
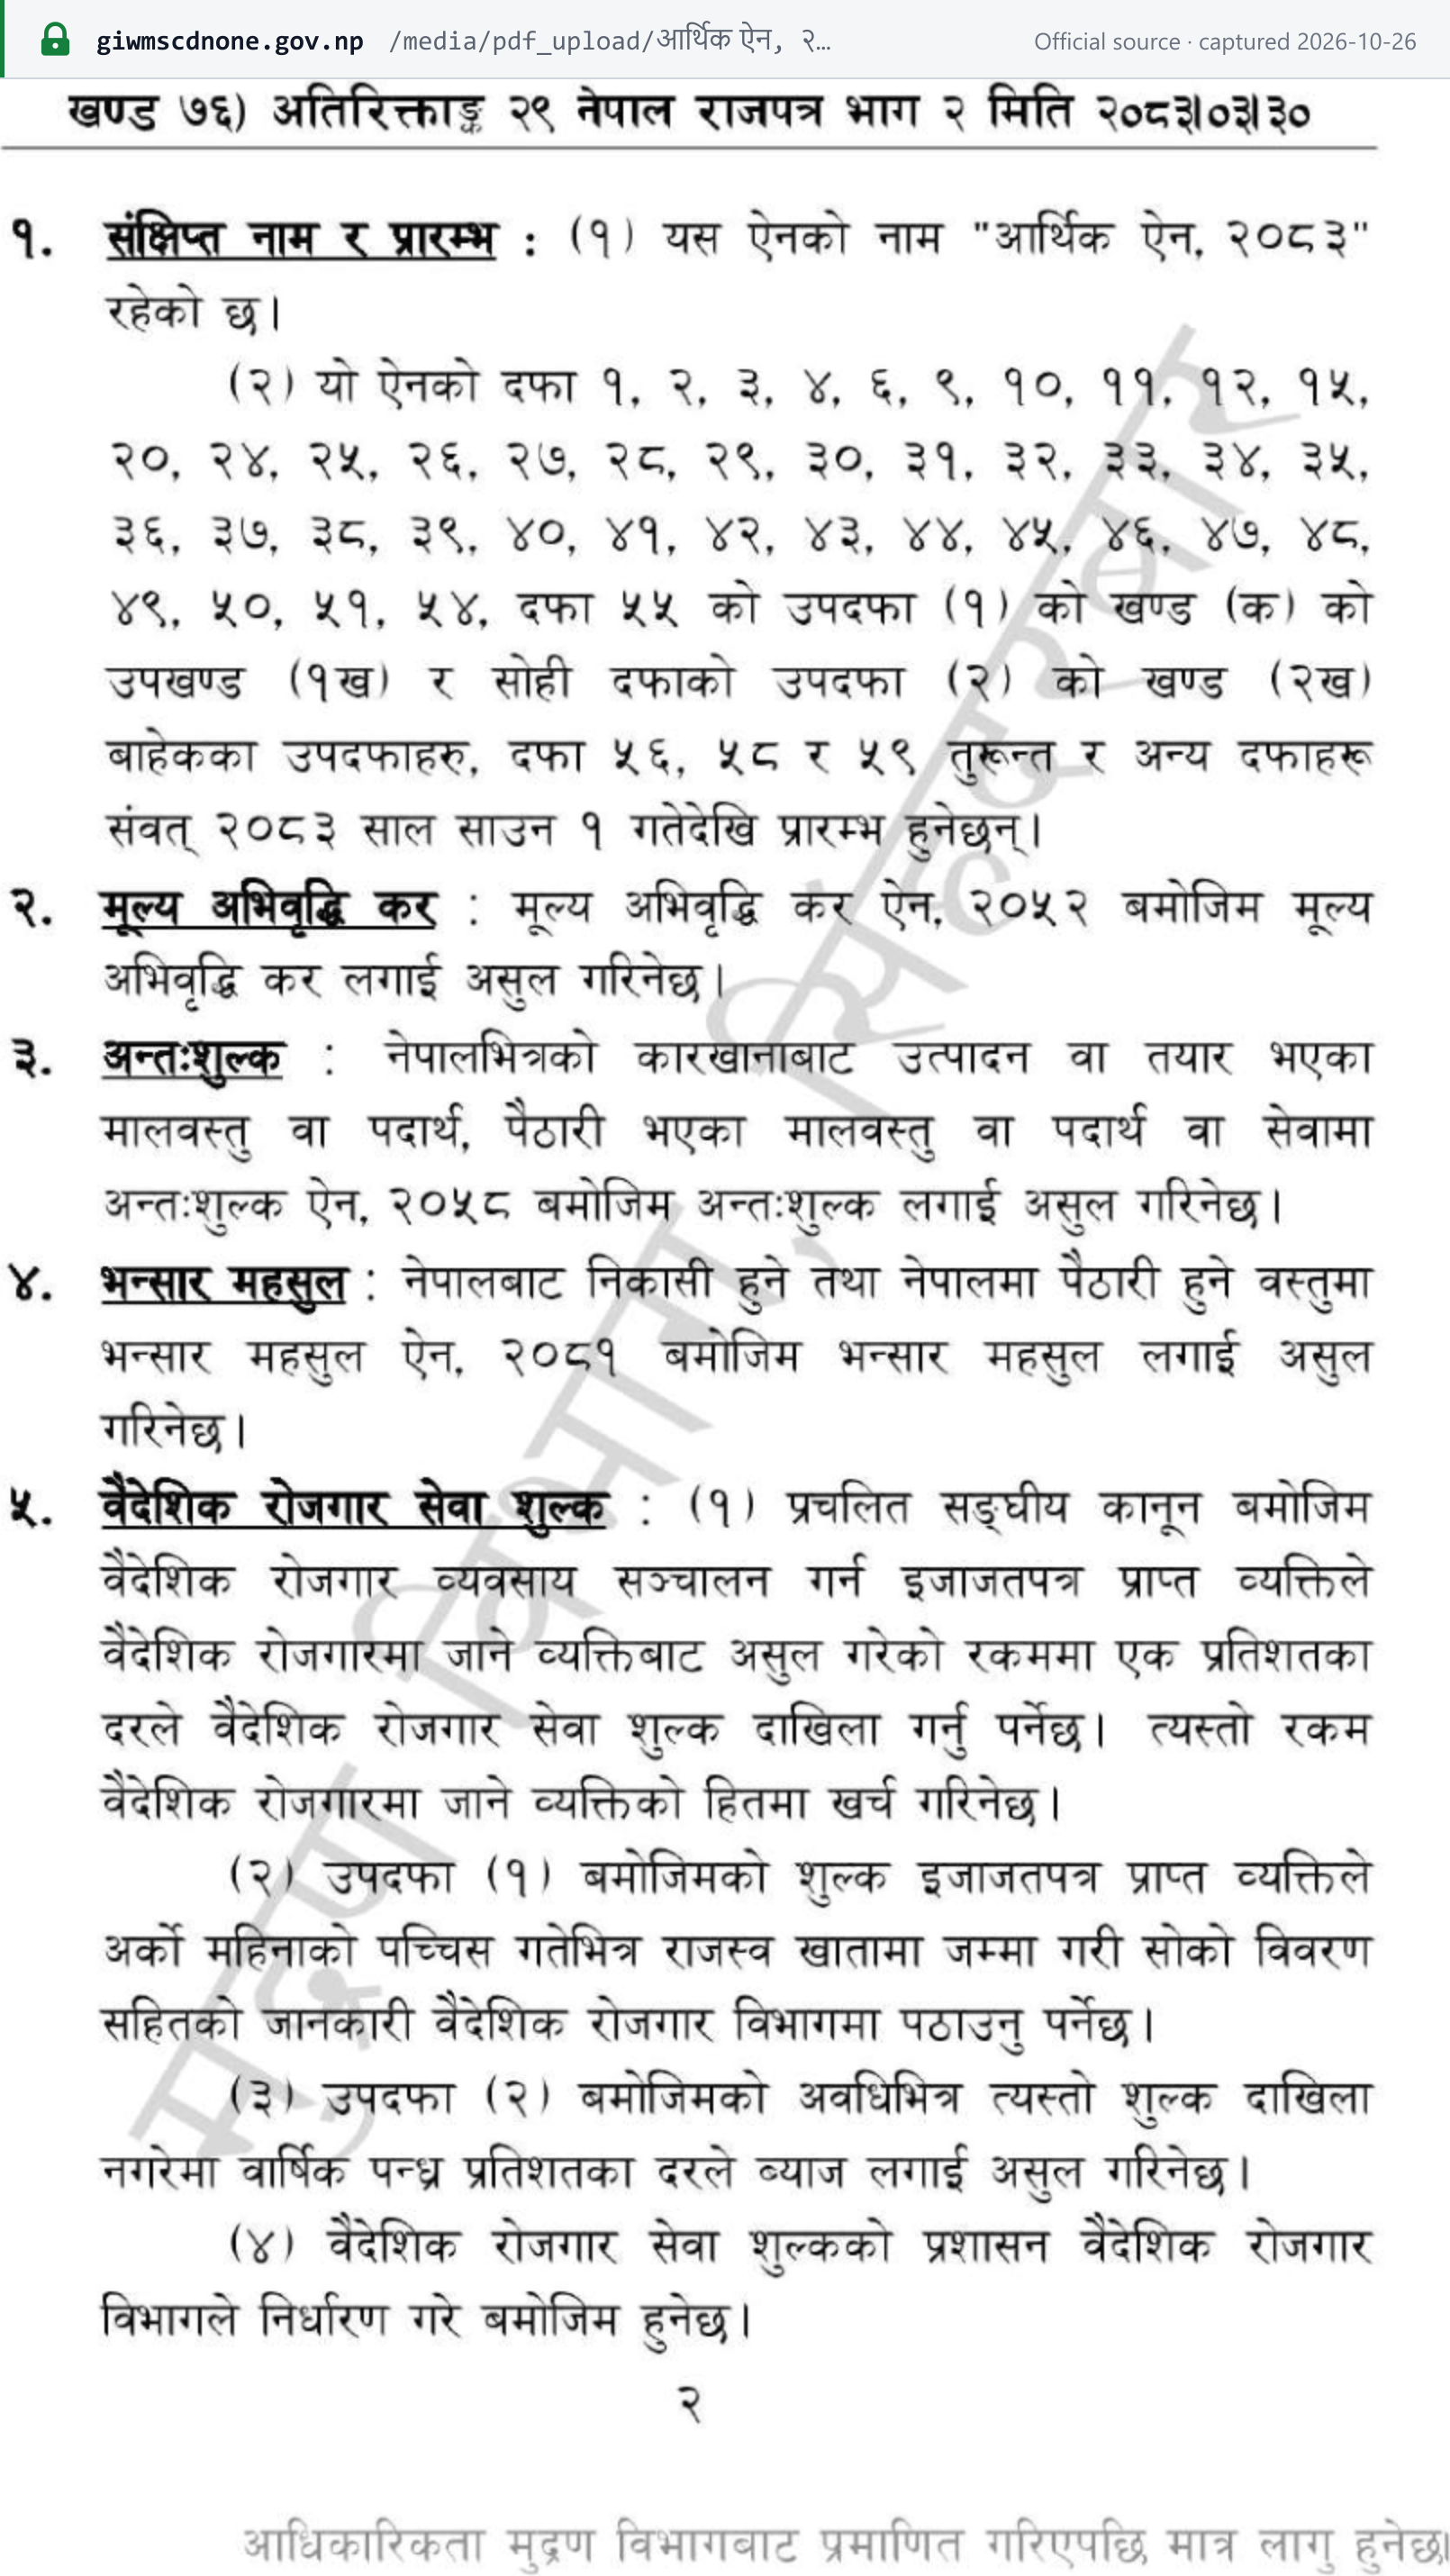
दफा ५५ को उपदफा (१) को खण्ड (क) को उपखण्ड (१ख) र सोही दफाको उपदफा (२) को खण्ड (२ख) बाहेकका उपदफाहरू, दफा ५६, ५८ र ५९ तुरुन्त र अन्य दफाहरू संवत् २०८३ साल साउन १ गतेदेखि प्रारम्भ हुनेछन्।… the sub-sections of section 55 other than sub-clause (1Kha) of clause (Ka) of sub-section (1) and clause (2Kha) of sub-section (2) of that section, and sections 56, 58 and 59, shall commence immediately, and the other sections shall commence from Saun 1, 2083.
 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Nepal creates a VAT collection mechanism for ride-sharing operators and their drivers effective 15 June 2026