Netherlands publishes its ViDA single VAT registration law (Stb. 2026, 327), in force from 1 January 2027
This page records one dated change. For the rules in Netherlands as they stand today, see the Netherlands guide →
- Jurisdiction
- Netherlands
- Tax
- VAT (BTW)
- Change type
- Registration
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 19 October 2026
- Effective
- 1 January 2027
- Authority
- Staatsblad van het Koninkrijk der Nederlanden
- Systems
- ERP, Tax engine, Invoicing, Reporting, E-commerce
- Verified
- Fetched from official source · high confidence
Non-established suppliers of gas, electricity, heating or cooling to non-business customers in the Netherlands; foreign suppliers without a Dutch VAT number selling to Dutch VAT-registered customers; businesses using call-off stock.
Update OSS and distance-sales logic for 1 January 2027 and schedule the 1 July 2028 reverse-charge change.
ERPTax engineInvoicingReportingE-commerce
The Wet van 7 oktober 2026 amending the Wet op de omzetbelasting 1968 (Wet implementatie Richtlijn btw in het digitale tijdperk - enkele btw-registratie, bill 36 920) was published in the Staatsblad on 19 October 2026 (Stb. 2026, 327) and enters into force on 1 January 2027. From 1 January 2027 to 30 June 2028 supplies of gas, electricity and heating or cooling through networks to non-business or non-taxable customers by a business not established in the Member State of taxation are treated as intra-Community distance sales. From 1 July 2028 VAT is reverse-charged to the customer where the supplier is not established in the Netherlands and has no Dutch VAT number and the customer has a Dutch VAT number (new art. 12(4) Wet OB 1968), and the call-off stock rules (art. 3b and related provisions) lapse from 1 July 2029.
What changed in detail
The Wet van 7 oktober 2026 amending the Wet op de omzetbelasting 1968 (Wet implementatie Richtlijn btw in het digitale tijdperk – enkele btw-registratie, bill 36 920) was published in the Staatsblad on 19 October 2026 as Stb. 2026, 327. It enters into force on 1 January 2027.
From 1 January 2027 to 30 June 2028, supplies of gas through a natural gas system, of electricity, and of heating or cooling through networks, made to non-business or non-taxable customers by a business not established in the Member State where the supply is taxed, are treated as intra-Community distance sales of goods.
From 1 July 2028 a new article 12(4) of the Wet OB 1968 shifts the VAT to the customer where the supplier does not live in, is not established in and has no fixed establishment in the Netherlands, has no Dutch VAT identification number, and the customer has a Dutch VAT number.
From 1 July 2029 the call-off stock rules, including article 3b, lapse.
What it means
This is now law, so the dates are fixed. Energy suppliers selling cross-border to Dutch consumers can use the OSS from 1 January 2027. The bigger change is the 1 July 2028 domestic reverse charge for foreign suppliers without a Dutch VAT number, which may remove the need to register in the Netherlands for supplies to Dutch-registered customers, so invoicing and VAT determination logic need a dated rule for it. Call-off stock arrangements should be wound down or restructured before 1 July 2029.
Proof
Deze wet treedt in werking met ingang van 1 januari 2027.This Act enters into force on 1 January 2027.
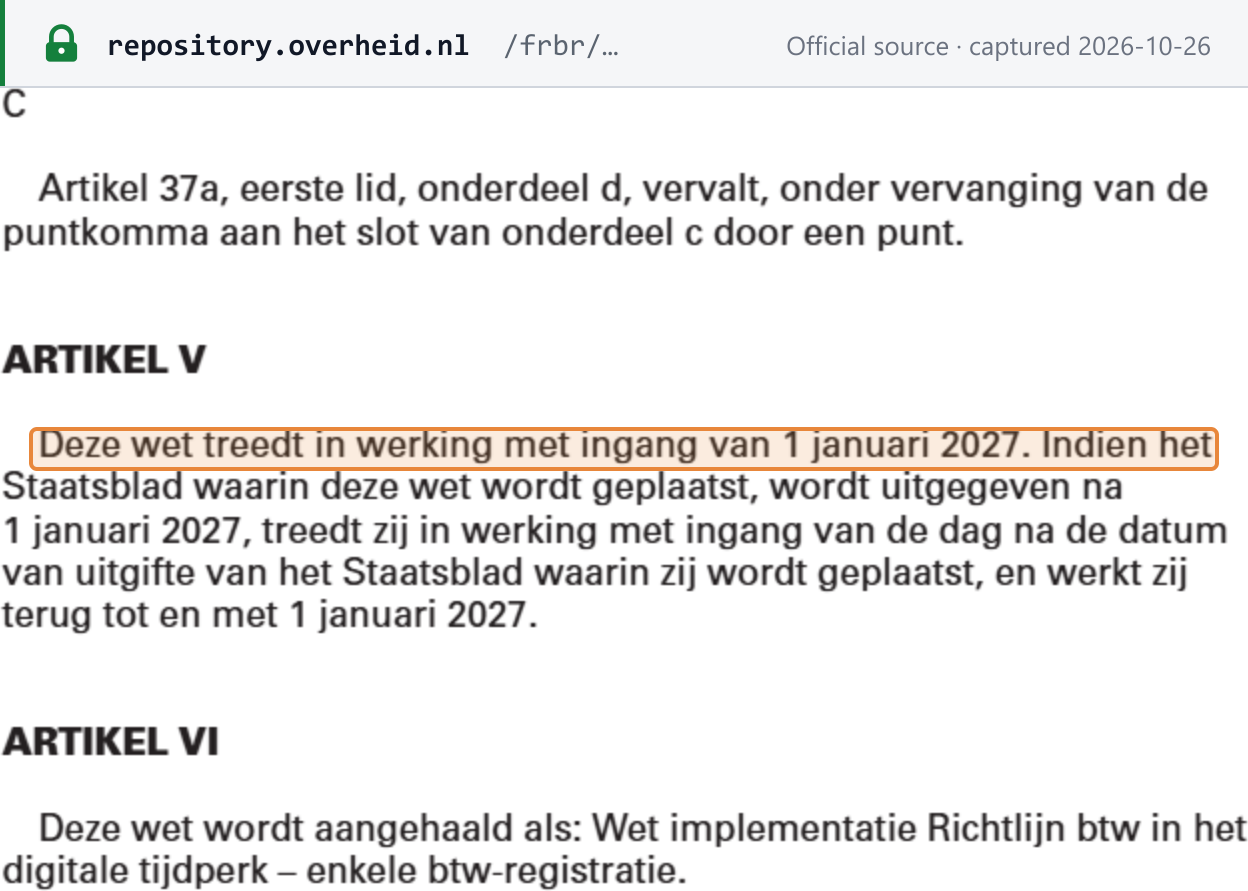 Source snapshot of the official page. Open full size ↗