Philippines BIR sets e-invoicing permit and certification rules, deadline 31 December 2026
This page records one dated change. For the rules in Philippines as they stand today, see the Philippines guide →
- Jurisdiction
- Philippines
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- Action required
- Announced
- 22 September 2026
- Effective
- 22 September 2026
- Authority
- Bureau of Internal Revenue (BIR), Philippines
- Systems
- Invoicing, ERP
- Verified
- Fetched from official source · high confidence
Covered taxpayers under RR 8-2022 and RR 11-2025 as amended by RR 26-2025, other than those classified as Micro taxpayers.
Secure a BIR Permit to Issue electronic invoices and be issuing them by 31 December 2026; obtain EIS certification within six months of the permit.
InvoicingERP
The Philippine Bureau of Internal Revenue issued Revenue Memorandum Circular No. 98-2026 on 22 September 2026, prescribing policies and guidelines for issuing electronic invoices under RR 8-2022 and RR 11-2025 as amended by RR 26-2025. Covered taxpayers other than micro taxpayers must issue electronic invoices on or before 31 December 2026, must secure a Permit to Issue electronic invoices, and must obtain Electronic Invoicing System certification within six months of the permit being issued. The circular took effect immediately.
What changed in detail
The Philippine Bureau of Internal Revenue issued Revenue Memorandum Circular No. 98-2026 on 22 September 2026, prescribing policies and guidelines for issuing electronic invoices under RR 8-2022 and RR 11-2025, as amended by RR 26-2025. Covered taxpayers — other than those classified as Micro taxpayers — must:
- issue electronic invoices on or before 31 December 2026;
- secure a Permit to Issue electronic invoices from the BIR; and
- obtain Electronic Invoicing System (EIS) certification within six months of that permit being issued.
Taxpayers not covered by the Section 237 mandate may still issue electronic invoices in place of manual invoices. The circular took effect immediately on issuance.
What it means
31 December 2026 is now a hard compliance date, not a target: covered taxpayers need the Permit to Issue in hand before that date, since the EIS certification clock (six months) only starts once the permit is issued — leaving the application late risks missing certification even if invoicing starts on time. Micro taxpayers stay outside the mandate but can opt in voluntarily. Systems and finance teams should treat the permit application as the first task, not the invoicing system build, since the permit is the gating step for everything that follows.
Proof
shall be required to issue electronic invoices and comply with the provisions of this Circular on or before December 31,2026.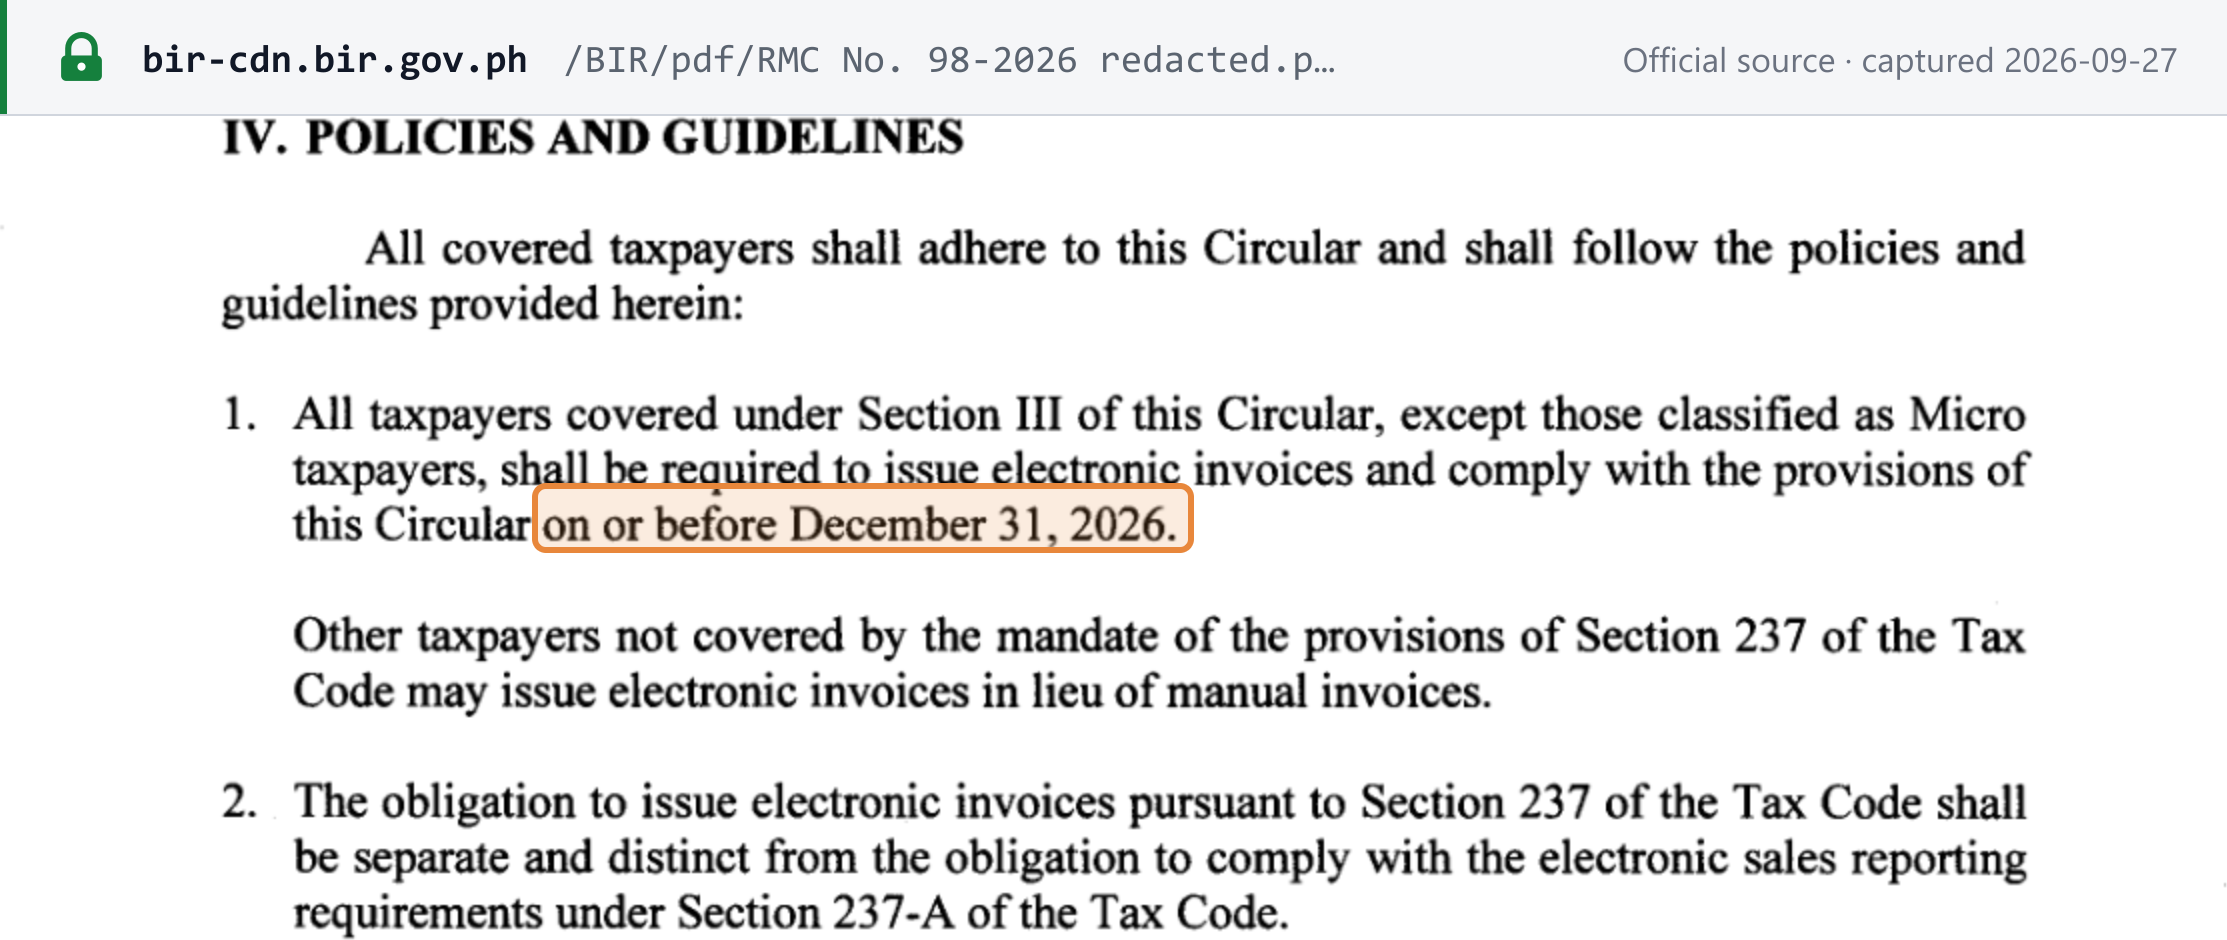 Source snapshot of the official page. Open full size ↗