Philippine head-office/branch e-invoicing rule sits in RR 11-2025, not RR 26-2025
This page records one dated change. For the rules in Philippines as they stand today, see the Philippines guide →
- Jurisdiction
- Philippines
- Tax
- VAT
- Change type
- E-invoicing
- Status
- Enacted
- Impact
- FYI
- Effective
- 31 December 2026
- Authority
- Bureau of Internal Revenue (BIR), Philippines
- Verified
- Fetched from official source · high confidence
Philippine taxpayers covered by BIR Revenue Regulations No. 11-2025 that operate as a Head Office with one or more Branch Offices.
No action — monitoring only.
The rule that a covered taxpayer's head office and all its branch offices must issue electronic invoices, and be covered by electronic sales reporting, is set by BIR Revenue Regulations No. 11-2025, Sections 3.A and 3.B. Revenue Regulations No. 26-2025 amends only the transitory provisions of RR 11-2025, giving covered taxpayers until 31 December 2026 to comply, and contains no head-office or branch provision. This corrects ph-einvoicing-deadline-rr-26-2025 (2026-W38), which attributed the head-office and branch obligation to RR 26-2025; the 31 December 2026 deadline in that entry is unaffected.
What changed in detail
This corrects the record of Revenue Regulations No. 26-2025, which attributed the head-office and branch electronic-invoicing obligation to that regulation. RR 26-2025 does not contain it.
The rule that a covered taxpayer’s Head Office and all its Branch Offices must issue electronic invoices, and be covered by electronic sales reporting, is set by RR No. 11-2025, Sections 3.A and 3.B. RR No. 26-2025 amends only the transitory provisions of RR 11-2025 — giving covered taxpayers until 31 December 2026 to comply — and contains no head-office or branch provision of its own.
What it means
The 31 December 2026 deadline in the earlier record is correct and unaffected by this correction; only its attribution of the head-office/branch rule to RR 26-2025 was wrong. When citing the source for the branch-office obligation itself, cite RR 11-2025, Sections 3.A/3.B, not RR 26-2025.
Proof
In case the above taxpayers or business activities are registered as a Branch Office, the taxpayers' Head Office and all its Branch Offices shall also be mandated to issue electronic invoices.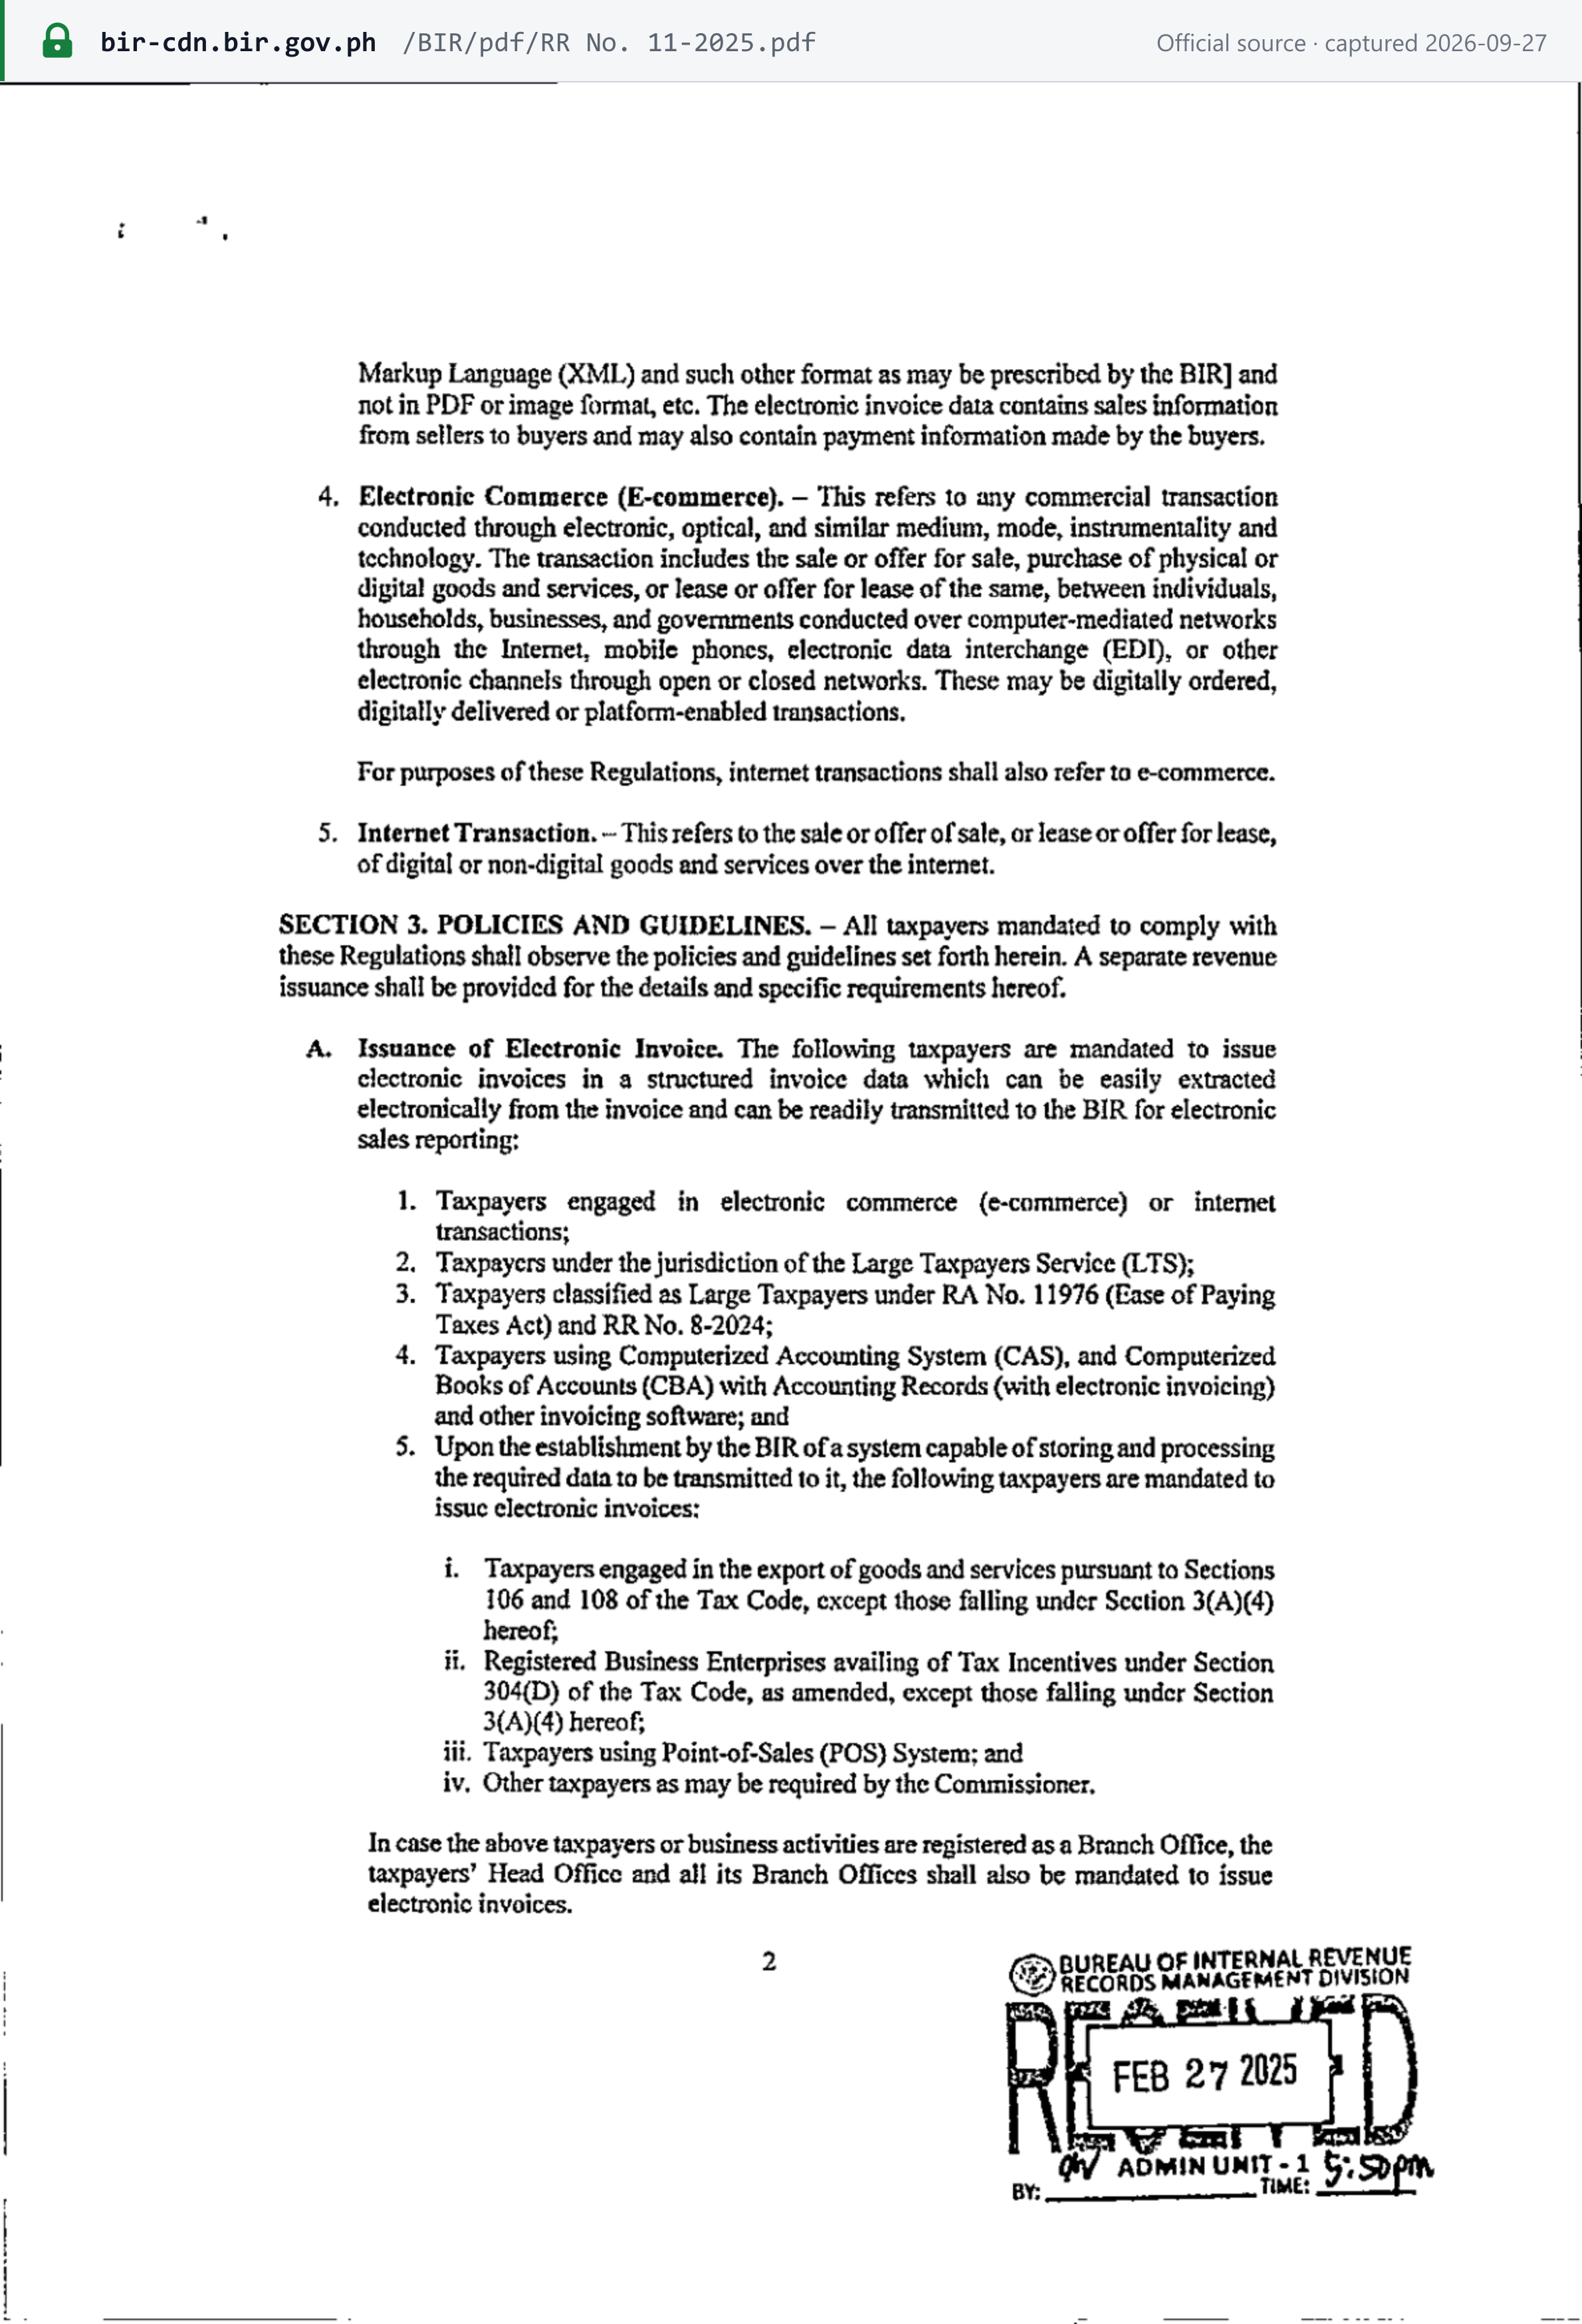 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- BIR gives covered Philippine taxpayers until 31 December 2026 to issue electronic invoices effective 31 December 2026