Poland's Act poz. 1270 changes the small-business VAT exemption limit and joint liability rules from 2027, and TAX FREE confirmation from 2028
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 29 September 2026
- Effective
- 1 January 2027
- Authority
- Dziennik Ustaw Rzeczypospolitej Polskiej
- Systems
- ERP, Tax engine, POS, Reporting
- Verified
- Fetched from official source · high confidence
Small businesses using the subjective VAT exemption, buyers and sellers within joint-and-several liability rules, retailers in the TAX FREE scheme, and cash register users in Poland.
Review exemption-threshold calculations, supplier due diligence for joint liability and cash-register deregistration procedures before 1 January 2027.
ERPTax enginePOSReporting
The same Act of 4 September 2026 (Dz.U. 2026 poz. 1270) also counts supplies under art. 13(3) towards the sales value for the small-taxpayer VAT exemption (new art. 113(1a)); rewrites the joint-and-several liability rule in art. 105a around a revised annex 15 and a new annex 16, with a carve-out for service purchases where the invoice total is below PLN 15,000 gross unless net purchases from one supplier exceed PLN 50,000 in a month; from 1 July 2028 allows travellers to obtain TAX FREE export confirmation through a terminal at designated border crossings (new art. 128(3a)); and introduces a PLN 300 penalty for failing to apply to deregister a cash register by the deadline. Effective 1 January 2027 except provisions listed in art. 9 (including the TAX FREE terminal provisions, 1 July 2028).
What changed in detail
The Act of 4 September 2026 (Dz.U. 2026 poz. 1270), which also introduces the VAT warehouse regime, makes four other changes.
First, supplies under art. 13(3) now count towards the sales value used for the subjective VAT exemption for small businesses (new art. 113(1a)).
Second, it rewrites the joint-and-several liability rule in art. 105a around a revised annex 15 and a new annex 16. There is a carve-out for service purchases where the invoice total is below PLN 15,000 gross, unless net purchases from one supplier exceed PLN 50,000 in a month.
Third, from 1 July 2028, travellers may obtain TAX FREE export confirmation through a terminal at designated border crossings (new art. 128(3a), with the terminal definition in art. 2 pkt 46a and the border-crossing list in art. 130(5)).
Fourth, a PLN 300 penalty is introduced for failing to apply to deregister a cash register by the deadline.
The provisions are effective from 1 January 2027, except those listed in art. 9: the TAX FREE terminal provisions apply from 1 July 2028, and art. 1 pkt 27 (cash register rules) from 1 January 2028.
What it means
The exemption-limit change matters most to businesses near the exemption limit, since art. 13(3) supplies now count towards it. The joint-liability carve-out has two thresholds that work together, PLN 15,000 gross per service invoice and PLN 50,000 net per supplier per month, so buyers need to track both. The TAX FREE terminals come later than the rest, so retailers in the scheme have until 1 July 2028. The cash-register penalty is small but applies if the deadline is missed.
Proof
Do wartości sprzedaży, o której mowa w ust. 1, wlicza się również czynności, o których mowa w art. 13The sales value referred to in para. 1 also includes the transactions referred to in art. 13
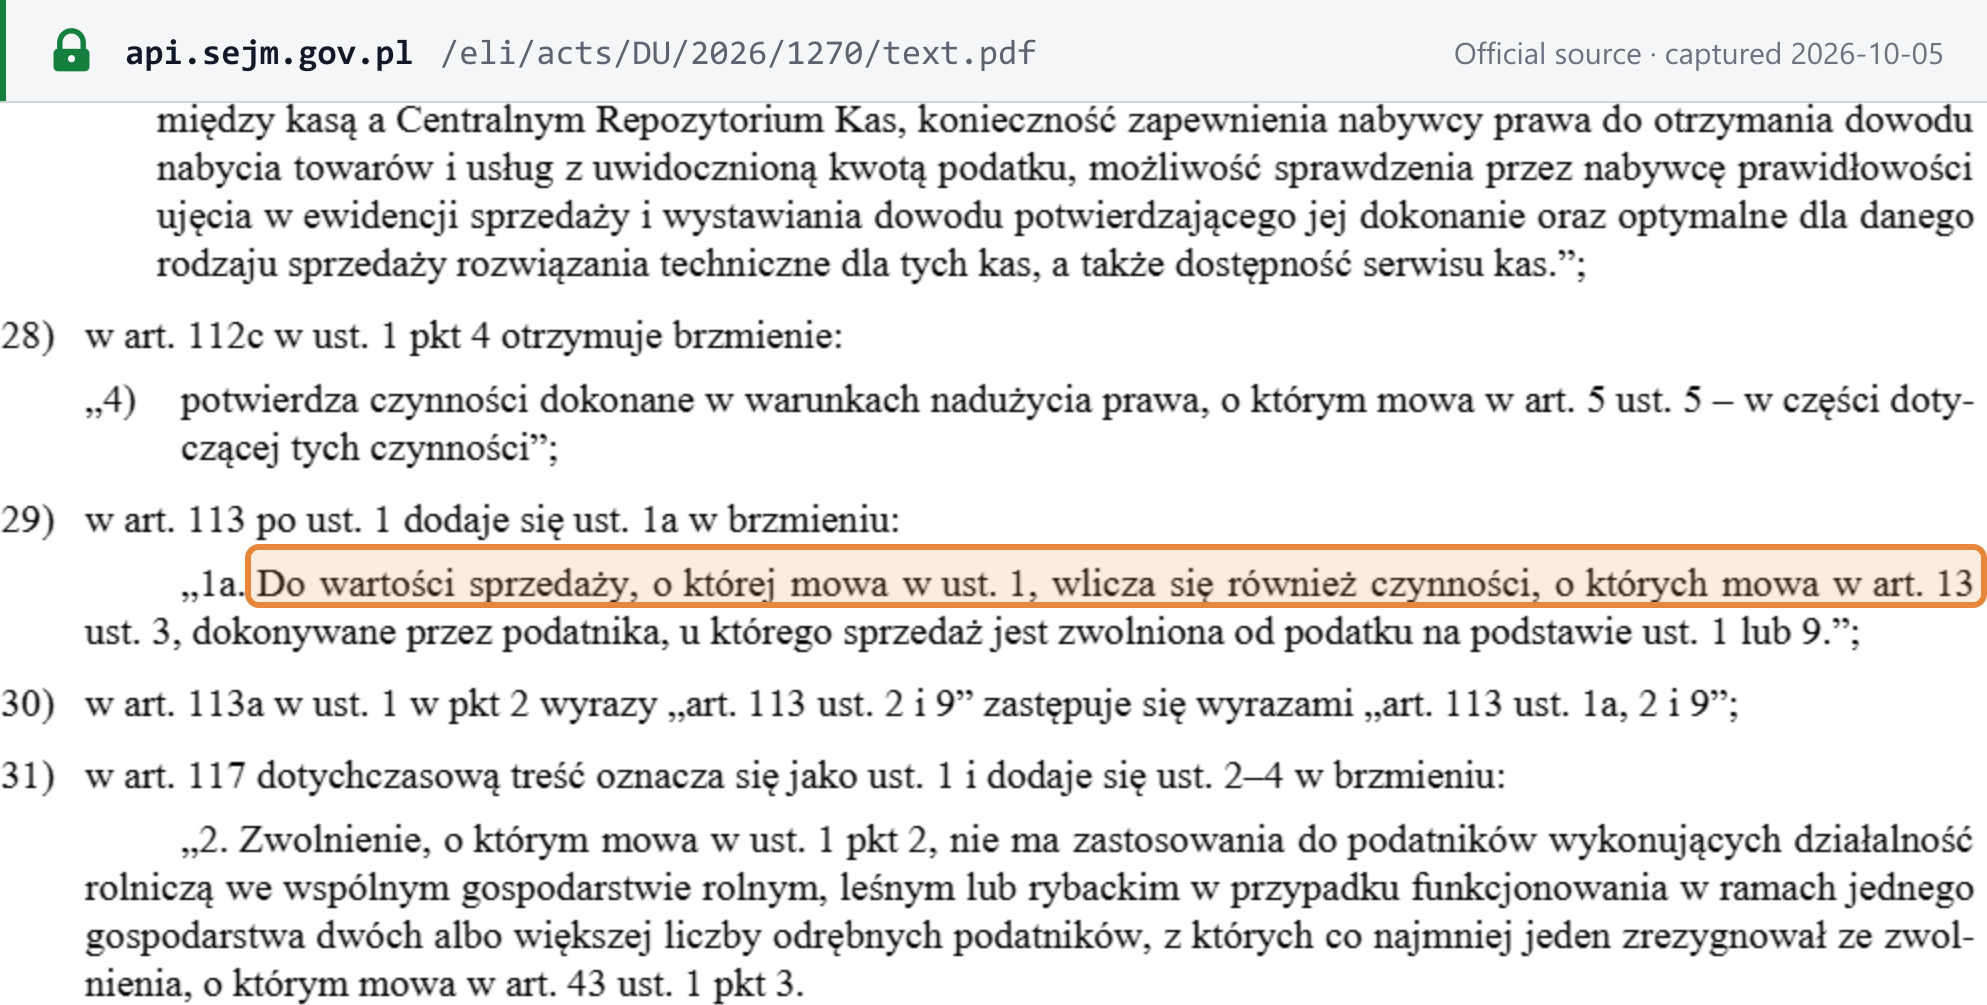 Source snapshot of the official page. Open full size ↗