Poland applies an 8% VAT rate to motor petrol and diesel from 3 October to 31 December 2026
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 2 October 2026
- Effective
- 3 October 2026
- Authority
- Dziennik Ustaw Rzeczypospolitej Polskiej
- Systems
- ERP, Invoicing, Tax engine, POS
- Verified
- Fetched from official source · high confidence
Fuel producers, importers, wholesalers and retailers in Poland supplying motor petrol, diesel and fuel biocomponents.
Apply the 8% rate to fuel supplies from 3 October 2026; the standard rate resumes from 1 January 2027 unless extended.
ERPInvoicingTax enginePOS
Poland's Minister of Finance and Economy issued a Regulation of 2 October 2026 (Dz.U. 2026 poz. 1288) adding § 11c to the Regulation of 9 December 2023 on reduced VAT rates: from 3 October 2026 to 31 December 2026 an 8% VAT rate applies to the supply, intra-Community acquisition and import of motor petrol, diesel and fuel biocomponents. The regulation entered into force on publication (2 October 2026).
What changed in detail
Poland’s Minister of Finance and Economy issued a Regulation of 2 October 2026 (Dz.U. 2026 poz. 1288). It adds § 11c to the Regulation of 9 December 2023 on reduced VAT rates.
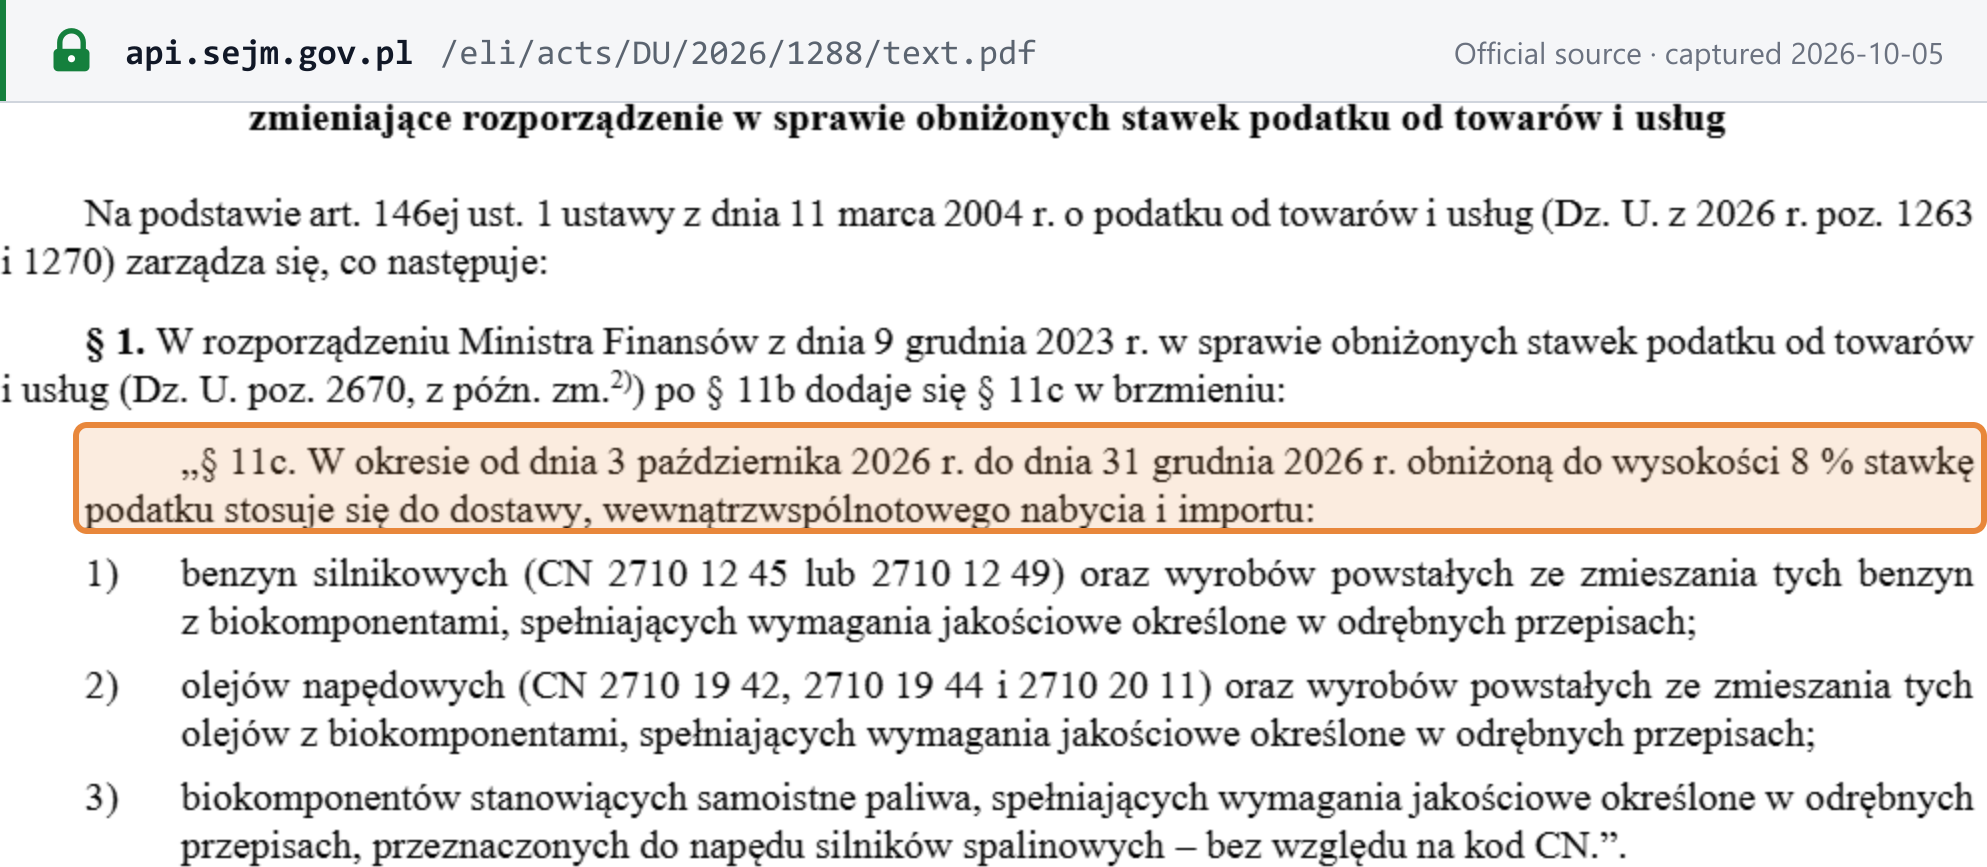
From 3 October 2026 to 31 December 2026, an 8% VAT rate applies to the supply, intra-Community acquisition and import of motor petrol, diesel (including blends with biocomponents) and biocomponents that are standalone fuels for combustion engines. The regulation entered into force on publication, 2 October 2026.
What it means
The rate applies to the supply, the intra-Community acquisition and the import, so the whole chain is covered rather than only retail sales. The window is short, from 3 October to 31 December 2026, so systems need a rate that reverts after 31 December unless it is extended. The regulation was published the day before it applied, which leaves little time to reconfigure pricing and invoicing.
Proof
„§ 11c. W okresie od dnia 3 października 2026 r. do dnia 31 grudnia 2026 r. obniżoną do wysokości 8 % stawkę podatku stosuje się do dostawy, wewnątrzwspólnotowego nabycia i importu:§ 11c. In the period from 3 October 2026 to 31 December 2026, the VAT rate reduced to 8% applies to the supply, intra-Community acquisition and import of:
 Source snapshot of the official page. Open full size ↗