Poland drafts 23% VAT on non-alcoholic drinks that mimic alcoholic or energy drinks
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 22 September 2026
- Effective
- 1 January 2027
- Authority
- Ministerstwo Finansów
- Verified
- Fetched from official source · high confidence
Producers and retailers of non-alcoholic drinks containing at least 20% fruit, vegetable or fruit-and-vegetable juice, drinks with added caffeine or taurine, and non-alcoholic beers — no action while this remains a bill.
No action — monitoring only.
Poland's Council of Ministers adopted on 22 September 2026 a draft law raising VAT to 23% on selected non-alcoholic drinks containing at least 20% fruit, vegetable or fruit-and-vegetable juice, and on drinks with added caffeine or taurine: from 5% in retail and from 8% in catering. All non-alcoholic beers would be taxed at the standard rate regardless of added juice. The planned entry into force is 1 January 2027; the bill must pass Parliament.
What changed in detail
This is a draft, not law. Poland’s Council of Ministers adopted, on 22 September 2026, a draft law raising VAT to the standard 23% rate on selected non-alcoholic drinks: those containing at least 20% fruit, vegetable or fruit-and-vegetable juice (up from 5% in retail and 8% in catering), and drinks with added caffeine or taurine. All non-alcoholic beers would move to the standard rate regardless of any added juice content. The Ministry of Finance frames the change as removing a preferential rate for drinks that function as alcoholic- or energy-drink substitutes.
The planned entry-into-force date is 1 January 2027. The bill must still pass through Parliament before it can take effect.
What it means
Beverage makers using the reduced rate on juice-content or non-alcoholic-beer products should model the 23% rate now, since the increase is a rate multiple (over 4x for the retail juice rate, nearly 3x in catering) rather than an incremental adjustment — repricing and margin work takes longer than a rate-table change. Nothing is due yet: this is a Council of Ministers draft awaiting parliamentary passage, and the 1 January 2027 date is the government’s planned date, not an enacted one.
Proof
Stawka VAT wzrośnie z 5% do 23% w obrocie handlowym oraz z 8%. do 23% w gastronomii na wybrane napoje bezalkoholowe zawierające co najmniej 20% soku owocowego, warzywnego lub owocowo-warzywnego.The VAT rate will rise from 5% to 23% in retail trade, and from 8% to 23% in catering, on selected non-alcoholic drinks containing at least 20% fruit, vegetable or fruit-and-vegetable juice.
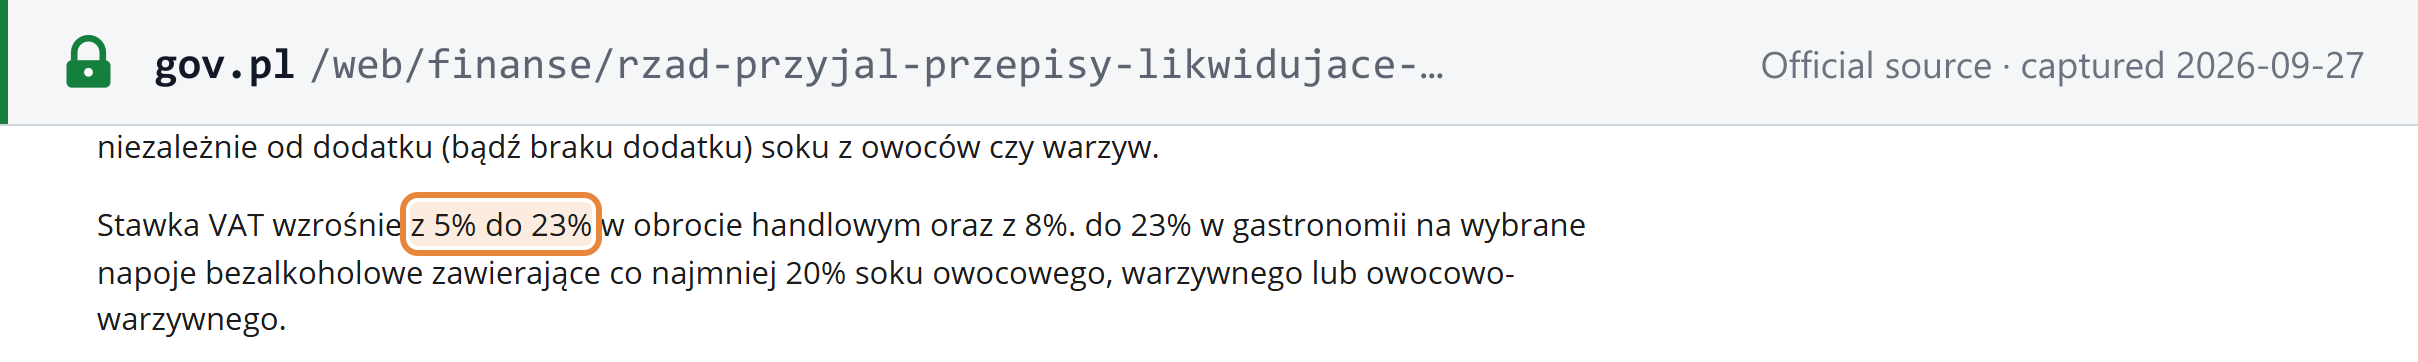 Source snapshot of the official page. Open full size ↗