Poland: Sejm passes the bill raising VAT to 23% on certain non-alcoholic and energy drinks; it is not law yet and goes to the Senate
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Plan ahead
- Announced
- 22 October 2026
- Effective
- 1 January 2027
- Authority
- Sejm Rzeczypospolitej Polskiej (lower house of the Polish Parliament)
- Systems
- ERP, Invoicing, Tax engine, POS, E-commerce
- Verified
- Fetched from official source · high confidence
Producers, importers, retailers and caterers selling non-alcoholic equivalents of alcoholic drinks, energy drinks and juice-containing drinks in Poland.
Re-map VAT rate codes for affected non-alcoholic and energy drinks ahead of 1 January 2027, subject to Senate and presidential action.
ERPInvoicingTax enginePOSE-commerce
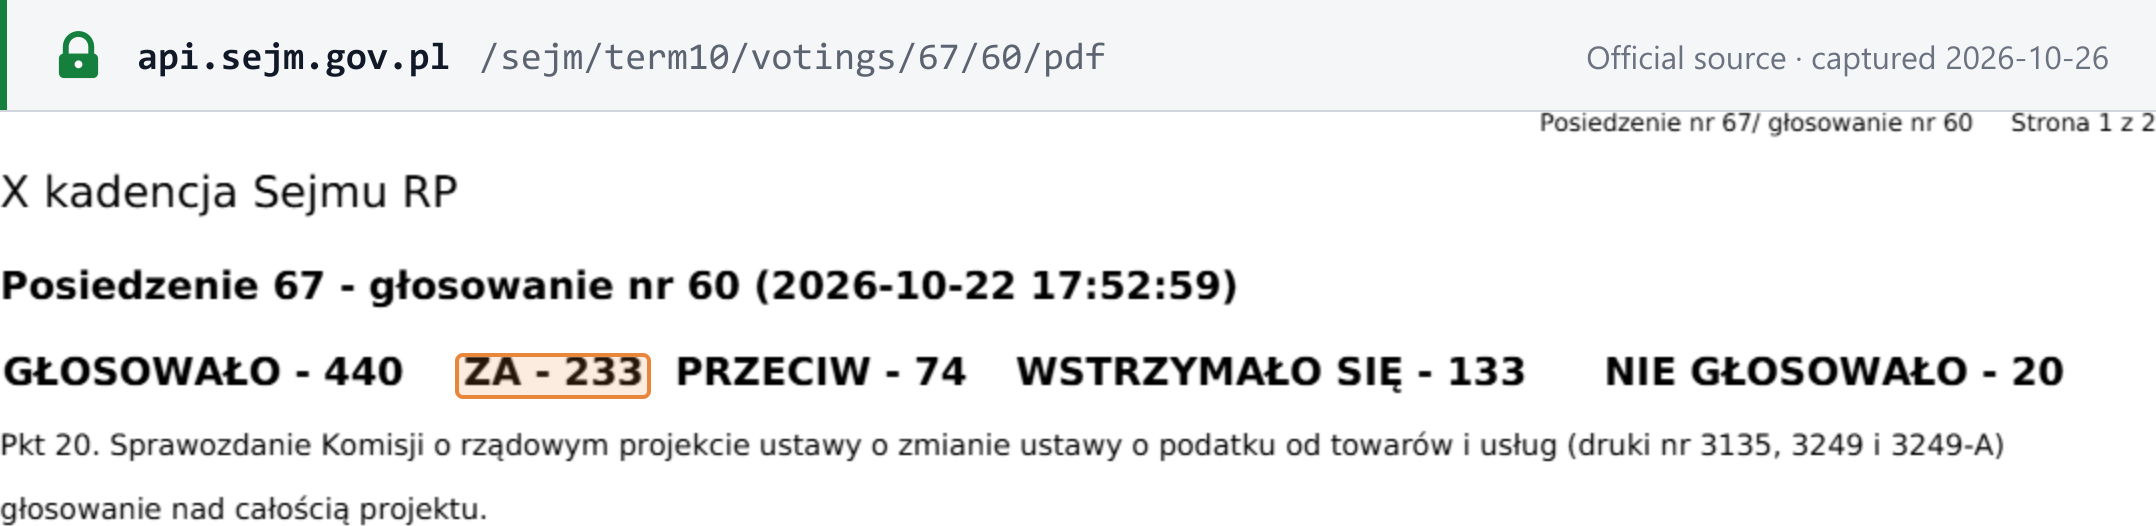
On 22 October 2026 (Sejm sitting 67) the Sejm passed at third reading the government bill amending the VAT Act that ends the preferential VAT treatment of non-alcoholic equivalents of alcoholic drinks and of energy drinks and raises VAT to 23% on certain non-alcoholic drinks containing at least 20% fruit, vegetable or fruit-and-vegetable juice (druki 3135, 3249 and 3249-A; 233 votes for, 74 against, 133 abstaining). The bill now goes to the Senate.
What changed in detail
The bill has passed the Sejm but is not law. On 22 October 2026, at sitting 67, the Sejm passed at third reading the government bill amending the VAT Act (druki 3135, 3249 and 3249-A). The vote was 233 for, 74 against and 133 abstaining. The bill now goes to the Senate.
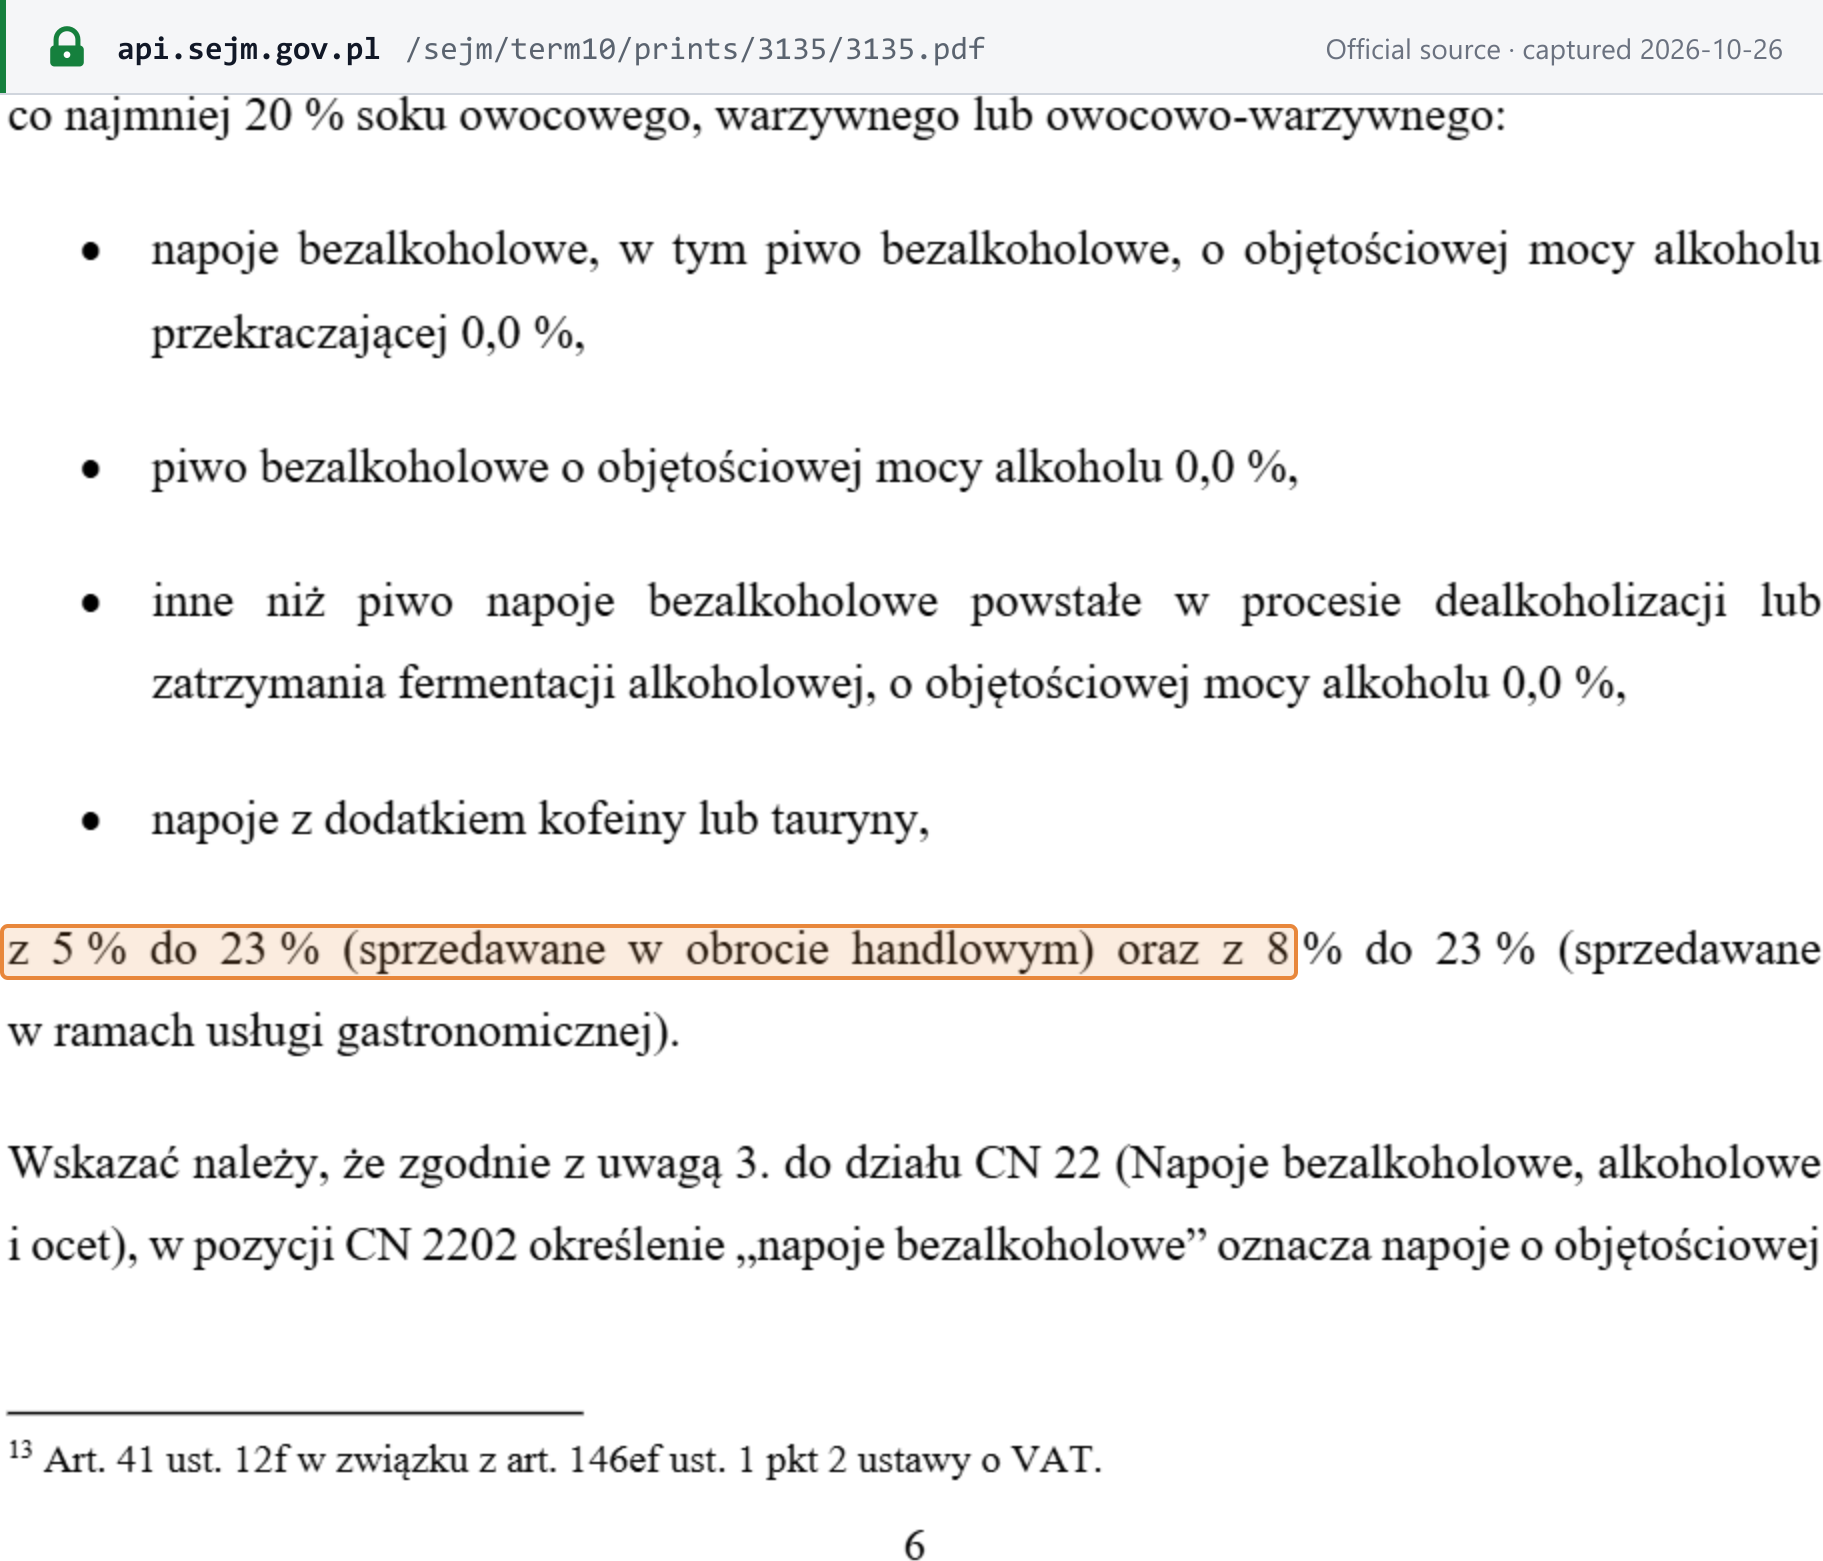
The bill ends the preferential VAT treatment of non-alcoholic equivalents of alcoholic drinks and of energy drinks, and raises VAT to 23% on certain non-alcoholic drinks containing at least 20% fruit, vegetable or fruit-and-vegetable juice. The explanatory memorandum to print 3135 puts the increase at 5% to 23% for drinks sold in retail trade and 8% to 23% for drinks sold as part of a catering service. Art. 2 of the bill sets entry into force on 1 January 2027.
This moves the bill recorded at the Sejm print 3135 stage through the Sejm.
What it means
The Senate can still propose amendments, and the President must sign before publication, so 1 January 2027 is the bill’s date rather than a settled one. The window is short: if the act is published late in the year, businesses may have little notice.
Producers, retailers and caterers should identify which products fall in the affected categories now, and prepare the rate change in tills, ERP and e-commerce price lists so it can be switched on once the act is published.
Proof
GŁOSOWAŁO - 440 ZA - 233 PRZECIW - 74 WSTRZYMAŁO SIĘ - 133VOTED - 440 FOR - 233 AGAINST - 74 ABSTAINED - 133
 Source snapshot of the official page. Open full size ↗
z 5 % do 23 % (sprzedawane w obrocie handlowym) oraz z 8 % do 23 % (sprzedawane w ramach usługi gastronomicznej)from 5% to 23% (sold in retail trade) and from 8% to 23% (sold as part of a catering service)
 Source snapshot of the official page. Open full size ↗