Poland: VAT act awaiting signature (druk 2838) would let exporters prove the 0% rate with carrier, postal or foreign import documents - not yet law
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Compliance
- Status
- Proposed
- Impact
- Plan ahead
- Announced
- 12 October 2026
- Authority
- Sejm Rzeczypospolitej Polskiej (lower house of the Polish Parliament)
- Systems
- ERP, Tax engine, Reporting, Customs
- Verified
- Fetched from official source · high confidence
Polish VAT taxpayers exporting goods outside the EU, and the carriers, forwarders and postal operators whose documents they rely on.
Update export 0% VAT evidence checklists to accept carrier, postal and third-country import documents once the act is signed and published.
ERPTax engineReportingCustoms
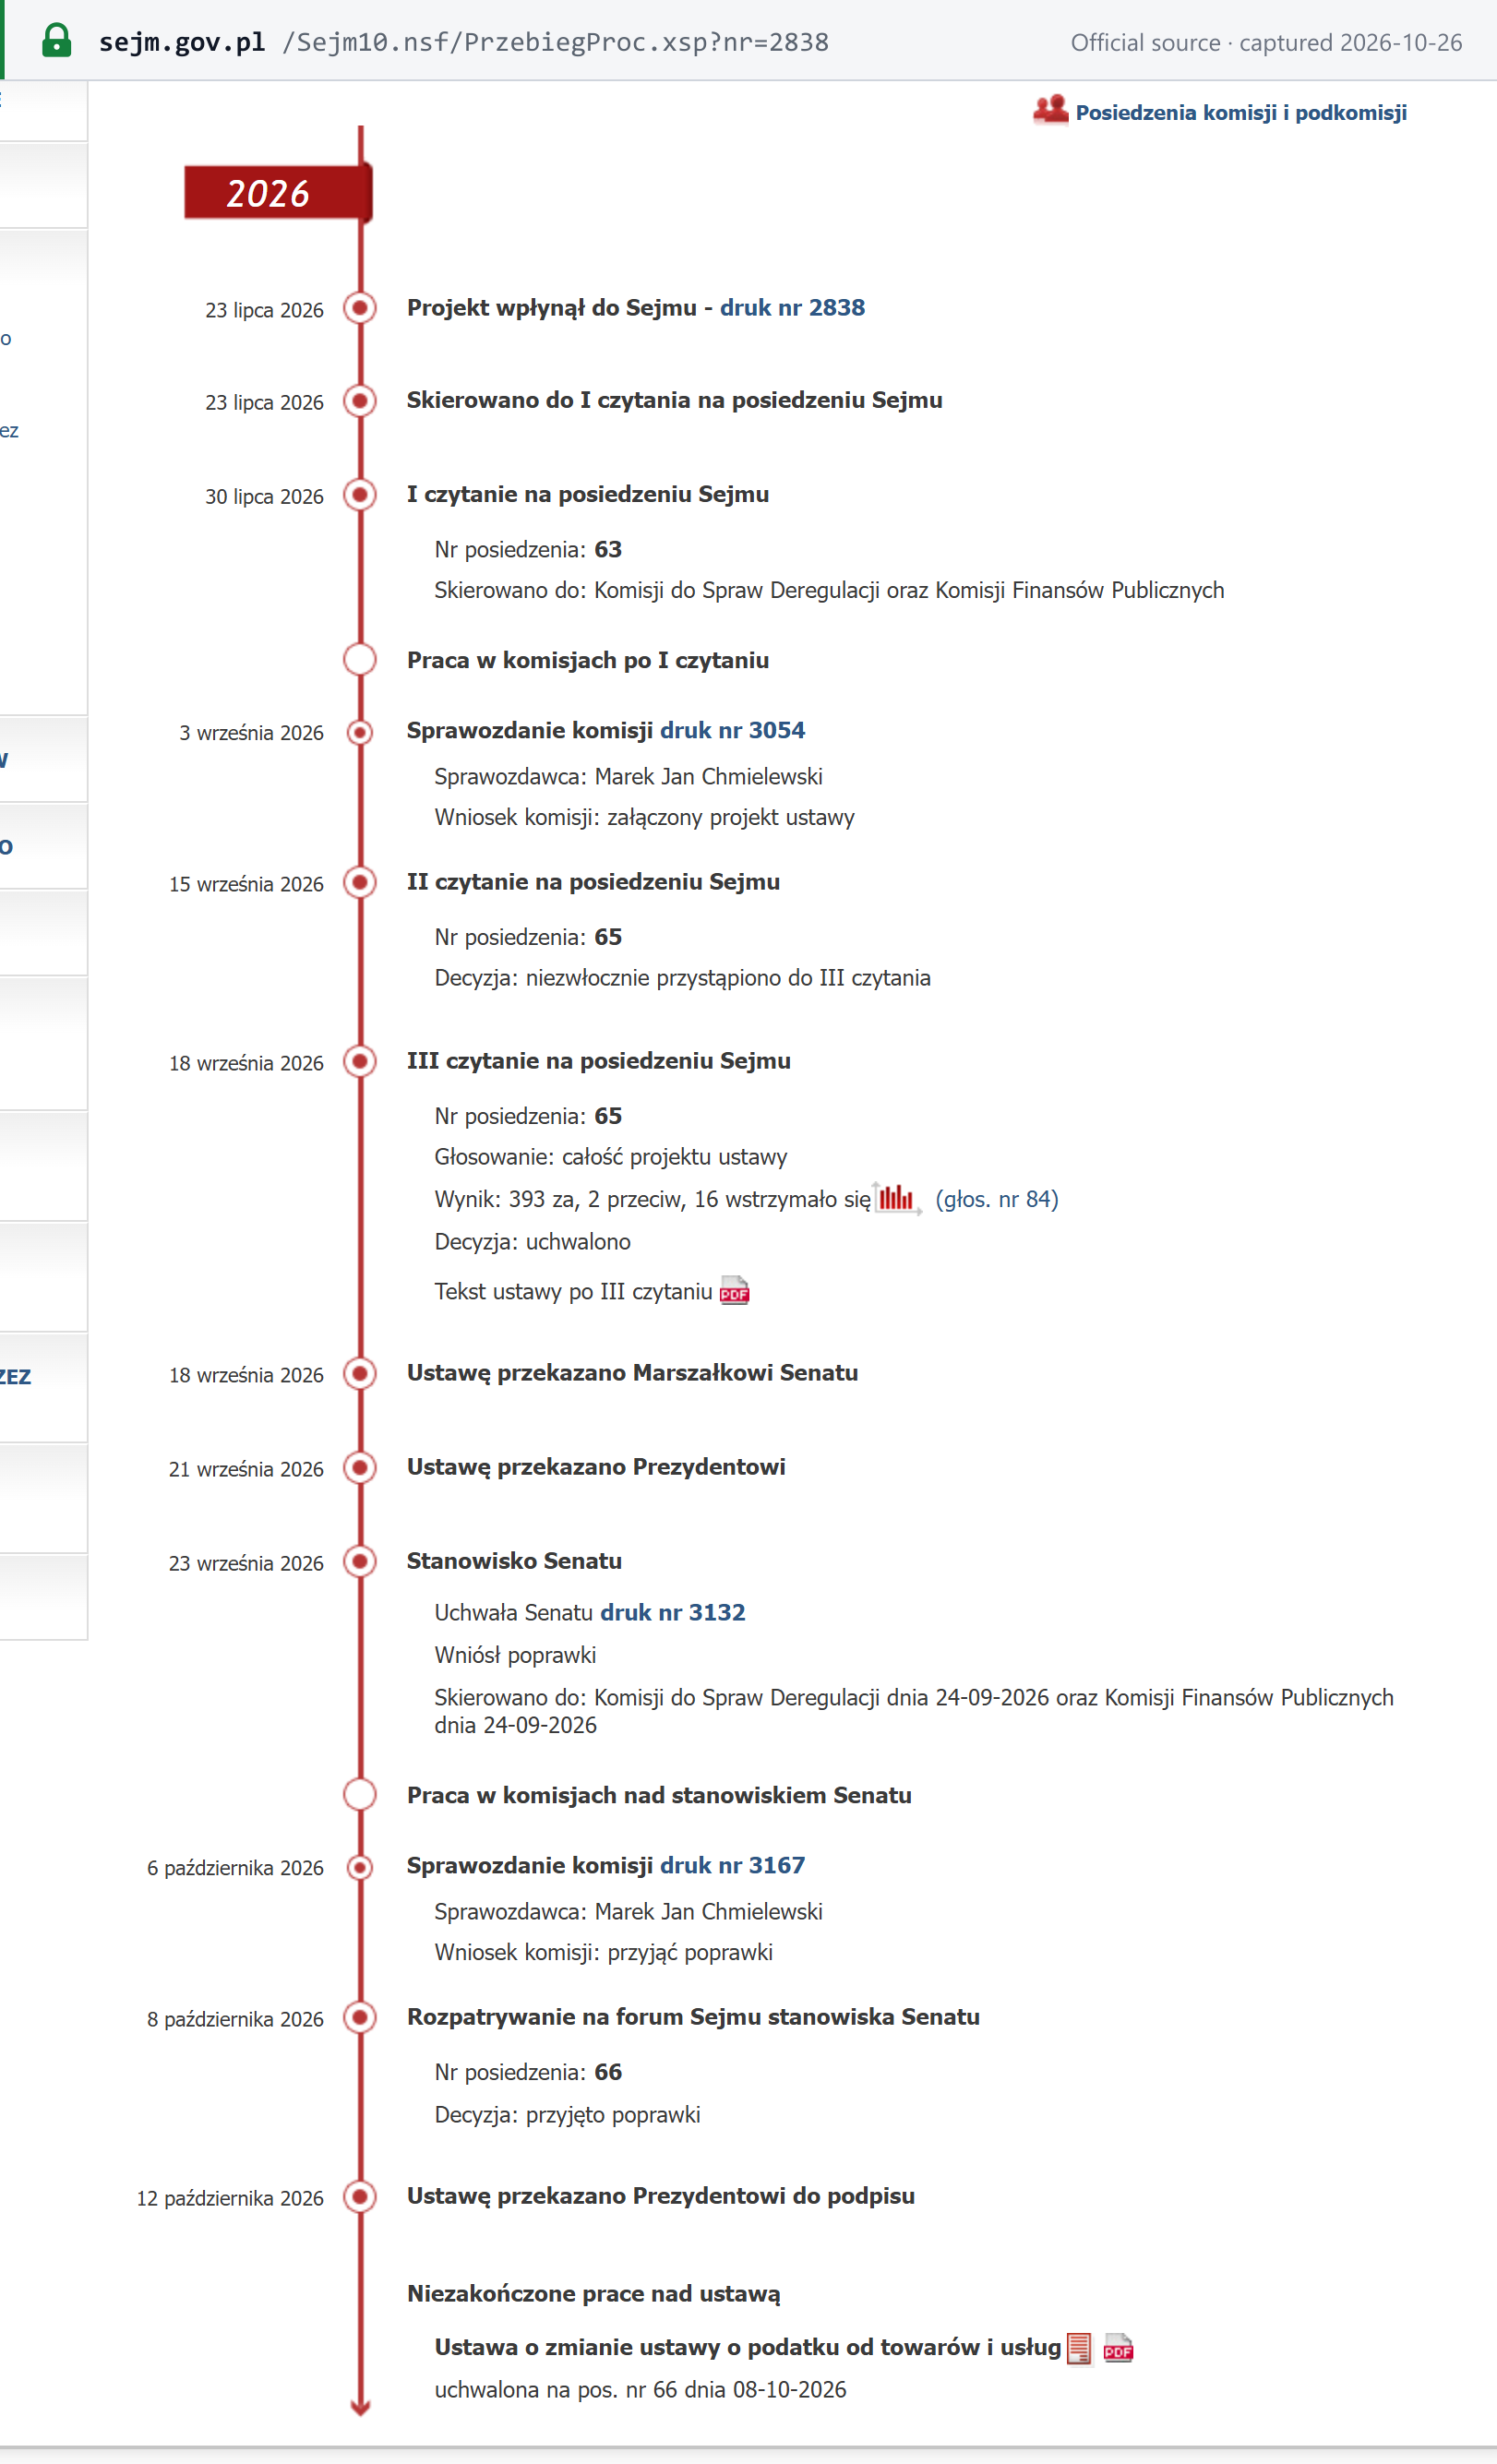
The Polish VAT Act amendment bill (Sejm print 2838, passed by the Sejm 18 September 2026, Senate amendments accepted 8 October 2026, passed to the President 12 October 2026) redefines export of goods in art. 2 pt 8 without the requirement of customs confirmation of exit, and in new art. 41(6c) additionally accepts as evidence for the 0% rate a carrier or forwarder transport document, a postal-operator delivery confirmation, or a third-country customs import document together with a written statement from the purchaser. The 0% rate applies if, before the return filing deadline for the period, the taxpayer holds evidence that the goods left the EU. The act enters into force 14 days after publication (arts 1 pts 5, 7, 8 and arts 4-5 the day after publication) and applies to exports whose return deadline has not expired before entry into force. This describes the Sejm committee text (print 3054); the three Senate amendments accepted on 8 October 2026 are not reflected here.
What changed in detail
The act is not yet law: it awaits the President’s signature and publication. The bill amending the VAT Act (Sejm print 2838) was passed by the Sejm on 18 September 2026; the Sejm accepted the Senate’s amendments on 8 October 2026, and the act was passed to the President on 12 October 2026.
In the committee text (print 3054), the act:
- redefines export of goods in art. 2 pt 8 of the VAT Act without the requirement of customs confirmation of exit;
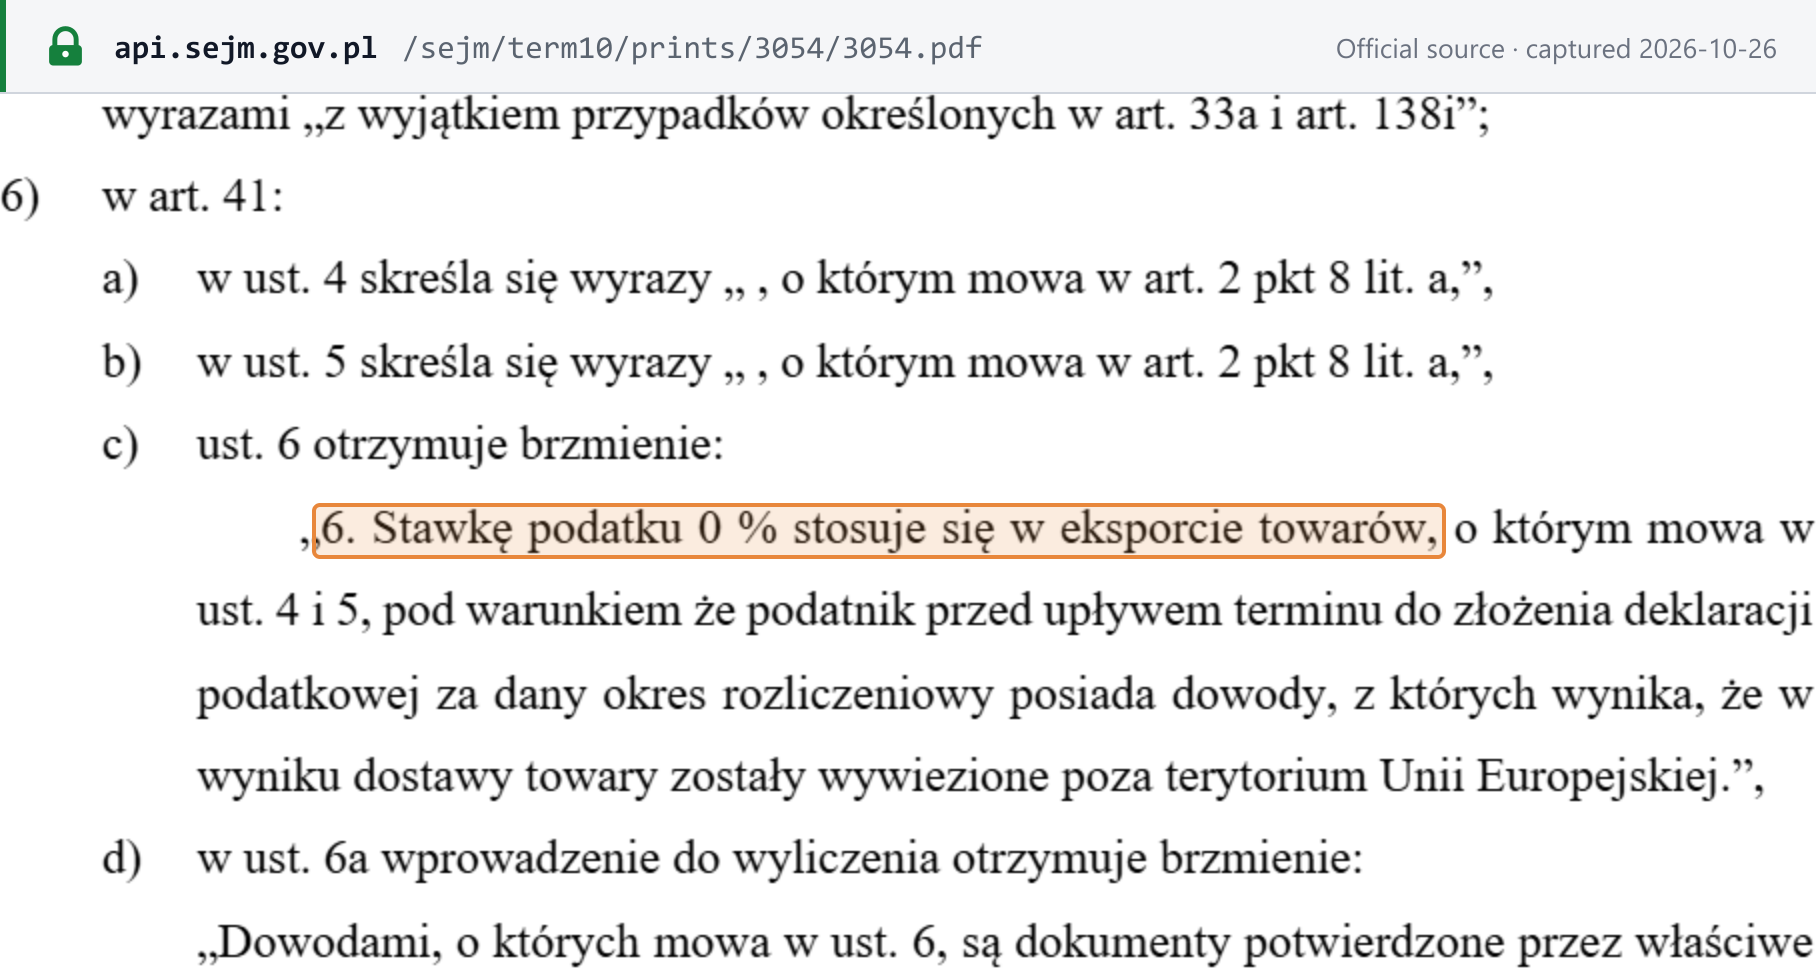
- applies the 0% rate if, before the return filing deadline for the period, the taxpayer holds evidence that the goods left the EU (art. 41(6)); and
- in new art. 41(6c), additionally accepts as evidence a transport document from the carrier or forwarder, a postal operator’s confirmation of delivery, or a third-country customs document confirming import, together with a written statement from the purchaser.
The act enters into force 14 days after publication, with arts 1 pts 5, 7 and 8 and arts 4 and 5 in force the day after publication. The new rules apply to exports whose return deadline has not expired before entry into force. The text read is the committee version, before the three Senate amendments.
The same act’s import-declaration changes are recorded at the Sejm’s acceptance of the Senate amendments.
What it means
Once in force, exporters would no longer depend solely on customs exit confirmation to support the 0% rate; commercial transport and postal records, or the foreign import document with a buyer statement, would also do. Because the rule reaches exports whose return deadline is still open at entry into force, some recent exports could benefit.
Until the act is signed and published, keep using customs evidence. Prepare updated evidence checklists, and check the published text in case the Senate amendments touched these provisions.
Proof
„6. Stawkę podatku 0 % stosuje się w eksporcie towarów, o którym mowa w ust. 4 i 5, pod warunkiem że podatnik przed upływem terminu do złożenia deklaracji podatkowej za dany okres rozliczeniowy posiada dowody, z których wynika, że w wyniku dostawy towary zostały wywiezione poza terytorium Unii Europejskiej.”"6. The 0% rate applies to the export of goods referred to in paragraphs 4 and 5 provided that, before the deadline for filing the tax return for the period, the taxpayer holds evidence showing that, as a result of the supply, the goods left the territory of the European Union."
 Source snapshot of the official page. Open full size ↗
Ustawę przekazano Prezydentowi do podpisuThe act was passed to the President for signature
 Source snapshot of the official page. Open full size ↗