Poland: draft law, not yet passed, would defer KSeF error penalties to 31 December 2027 and extend the energy and allowance reverse charge to 30 June 2030
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- E-invoicing
- Status
- Proposed
- Impact
- Watch
- Announced
- 20 October 2026
- Effective
- 31 December 2026
- Authority
- Ministerstwo Finansów
- Systems
- Invoicing, ERP, Tax engine
- Verified
- Fetched from official source · high confidence
All Polish businesses issuing invoices through KSeF, and suppliers and buyers of gas, electricity and greenhouse-gas emission allowances under the reverse charge.
Plan for mandatory KSeF issuance from 1 January 2027 (including micro-businesses); track the bill through the Sejm for the penalty-deferral and reverse-charge dates.
InvoicingERPTax engine
On 20 October 2026 Poland's Council of Ministers adopted a draft law that extends to 31 December 2027 the deferral of financial penalties for errors in using KSeF, and extends to 30 June 2030 the VAT reverse-charge mechanism for supplies of gas in the gas system, electricity and greenhouse-gas emission allowances. The Ministry of Finance states that from 1 January 2027 KSeF becomes mandatory for all businesses (the transitional period for taxpayers with monthly invoiced sales up to PLN 10,000 gross expires at end-2026). The draft goes to parliament and is intended to enter into force on 31 December 2026.
What changed in detail
This is a draft law adopted by the government, not an enacted statute. On 20 October 2026 Poland’s Council of Ministers adopted a draft law that extends to 31 December 2027 the deferral of financial penalties for errors in using KSeF, and extends to 30 June 2030 the VAT reverse-charge mechanism for supplies of gas in the gas system, electricity and greenhouse-gas emission allowances.
The Ministry of Finance states that from 1 January 2027 KSeF becomes mandatory for all businesses; the transitional period for taxpayers with monthly invoiced sales up to PLN 10,000 gross expires at the end of 2026. The draft goes to parliament and is intended to enter into force on 31 December 2026.
What it means
The intended entry into force leaves almost no time before the reverse charge and penalty deferral would otherwise end, so passage in parliament before year-end is the thing to watch. KSeF becomes mandatory for all businesses from 1 January 2027 regardless of this draft; the draft changes the penalty deferral and the reverse-charge period.
Proof
Przyjęty projekt ustawy przedłuża też do 30 czerwca 2030 r. mechanizm odwrotnego obciążenia VAT w obrocie gazem, energią elektryczną i uprawnieniami do emisji.The adopted draft law also extends to 30 June 2030 the VAT reverse-charge mechanism for trade in gas, electricity and emission allowances.
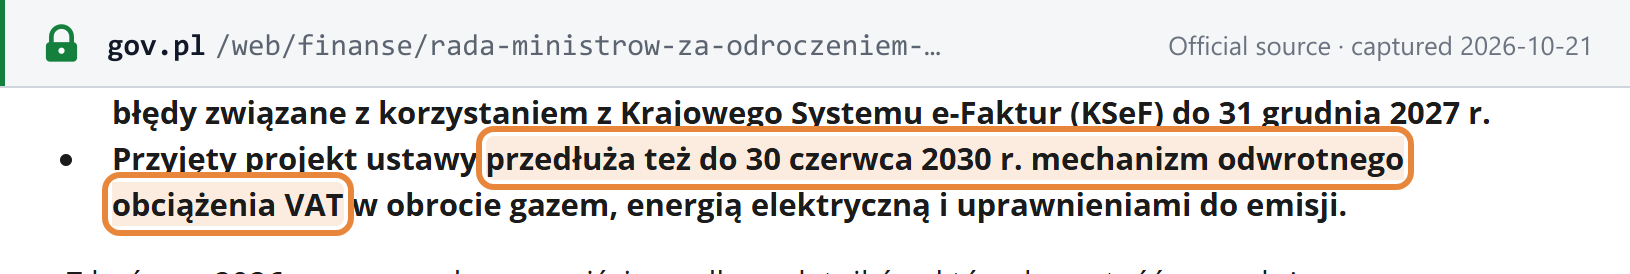 Source snapshot of the official page. Open full size ↗