Sierra Leone denies input tax on digital services bought from suppliers with no local presence
- Jurisdiction
- Sierra Leone
- Tax
- GST
- Change type
- Digital services
- Status
- In force
- Impact
- Plan ahead
- Announced
- 7 January 2026
- Effective
- 1 January 2026
- Authority
- National Revenue Authority (Sierra Leone)
- Systems
- Tax engine, ERP
- Verified
- Fetched from official source · high confidence
GST-registered businesses in Sierra Leone that buy digital services from suppliers with no physical presence or registered office in the country.
Review input-tax claims relating to digital services procured from non-resident suppliers with no Sierra Leone presence; such input tax is now disallowed.
Tax engineERP
Sierra Leone's Finance Act, 2026 amended section 28(2) of the Goods and Services Tax Act 2009 to deny input tax deduction where the acquisition or expense is incurred in the supply of a digital service by a person who has no physical presence or registered office in Sierra Leone, effective 1 January 2026.
What changed in detail
The Finance Act, 2026 (Act No. 1 of 2026), published as a supplement to the Sierra Leone Gazette Extraordinary Vol. CLXVII, No. 3 of 7 January 2026, amends the Goods and Services Tax Act, 2009. Section 20 of the Finance Act amends section 28(2) of the GST Act — the provision listing acquisitions and expenses for which input tax is not deductible — by inserting a new paragraph (h) immediately after paragraph (g).
The new paragraph applies where the acquisition or expense is incurred in the supply of a digital service by a person who has no physical presence or registered office in Sierra Leone. The test in the clause is the supplier’s presence, not the nature of the service or the identity of the buyer.
Section 1 of the Finance Act provides that, unless otherwise stated, the Act is deemed to have come into operation on 1 January 2026. The Act was passed in Parliament on 25 November 2025 and signed by the President on 29 December 2025. The same Act adds a registration trigger for those suppliers at section 15(4)(c) and, at section 24, requires them to appoint a Sierra Leone representative.
What it means
The denial and the registration trigger point in opposite directions, and that tension is the thing to plan around. A non-resident digital-services supplier is now required to register and to appoint a local representative — yet tax arising on its supplies is blocked from deduction while it lacks a physical presence or registered office. The cost of the non-resident’s non-presence lands on the buyer.
Practically, the deduction question turns on a fact about the supplier that the buyer does not hold by default. Procurement records built around a supplier’s name and invoice will not answer it; whether that supplier has a Sierra Leone office or registered address will. Expect this to become a vendor-onboarding field rather than a period-end adjustment.
Proof
that acquisition or expense is incurred in the supply of digital service by a person who has no physical presence or registered office in Sierra Leone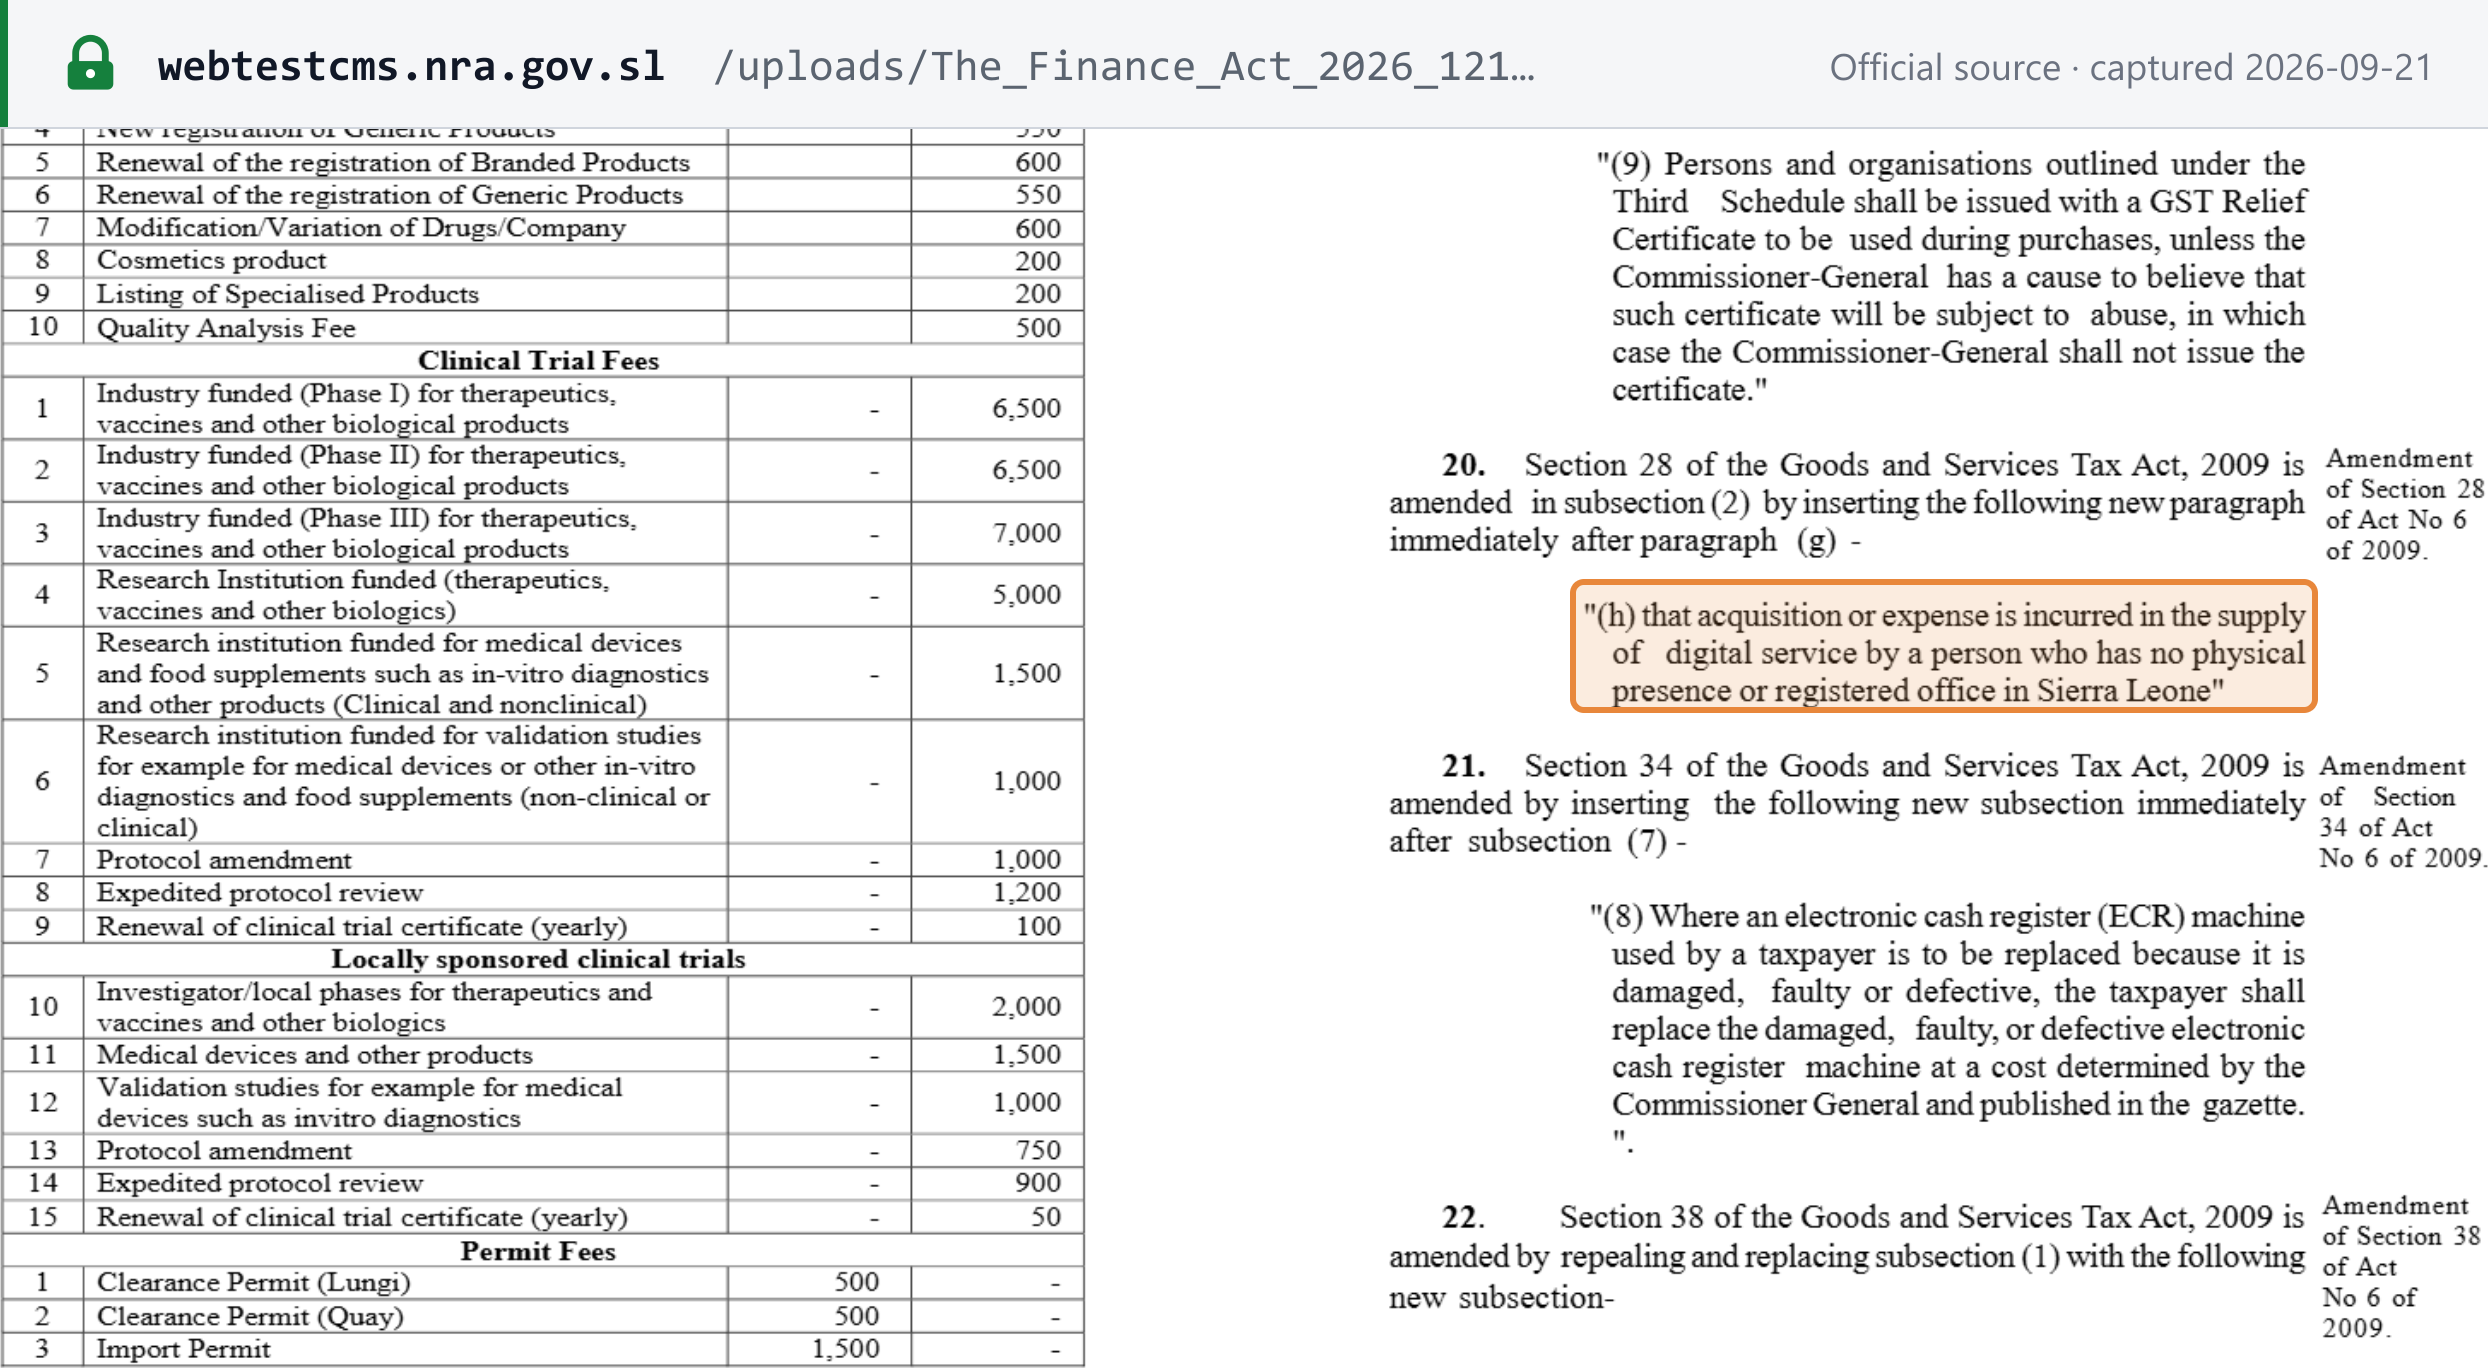 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · The Finance Act, 2026 (Act No. 1 of 2026) — Supplement to the Sierra Leone Gazette Extraordinary Vol. CLXVII, No. 3 of 7 January 2026, s.20 inserting GST Act 2009 s.28(2)(h) · webtestcms.nra.gov.sl