Spain sets a conditional 10% VAT rate on electricity and gas for November and December 2026
This page records one dated change. For the rules in Spain as they stand today, see the Spain guide →
- Jurisdiction
- Spain
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 30 September 2026
- Effective
- 1 November 2026
- Authority
- Boletín Oficial del Estado (BOE)
- Systems
- Tax engine, Invoicing, ERP
- Verified
- Fetched from official source · high confidence
Electricity and gas suppliers; for electricity, customers with up to 10 kW contracted power and severely vulnerable bono social recipients; gas, pellets and firewood are not limited by customer group.
Configure a conditional 10% VAT rate for Nov and Dec 2026 on electricity (<=10 kW / severely vulnerable) and on gas, pellets and firewood. Switch it on only if INE's CPI release meets the >15% trigger, and watch Congress validation.
Tax engineInvoicingERP
Real Decreto-ley 25/2026 of 29 September 2026 (BOE no. 241, 30 September 2026, BOE-A-2026-20265; in force 1 October 2026) provides a conditional 10% VAT rate for November and December 2026. The electricity trigger: if September 2026 CPI for subclass 04.5.1.0 Electricity is more than 15% above September 2025 (per INE's October release), 10% applies in November 2026 to supplies, imports and intra-EU acquisitions of electricity. It covers holders of contracts with contracted power up to 10 kW and severely vulnerable bono social recipients. The same test on subclass 04.5.2.1 Natural gas triggers 10% for natural gas, biomass briquettes and pellets, and firewood. Article 19 repeats the mechanism for December 2026, based on October 2026 CPI. The decree-law still needs validation by the Congreso de los Diputados, and none had been published as of 5 October 2026.
What changed in detail
Real Decreto-ley 25/2026 of 29 September 2026 (BOE no. 241, 30 September 2026, BOE-A-2026-20265) entered into force on 1 October 2026. It provides a conditional 10% VAT rate for November and December 2026.
Electricity trigger: if the September 2026 CPI for subclass 04.5.1.0 Electricity is more than 15% above September 2025, per INE’s October release, 10% applies in November 2026 to supplies, imports and intra-EU acquisitions of electricity. It covers holders of contracts with contracted power up to 10 kW and severely vulnerable bono social recipients.
The same test on subclass 04.5.2.1 Natural gas triggers 10% for natural gas, biomass briquettes and pellets, and firewood.
Article 19 repeats the mechanism for December 2026, based on October 2026 CPI.
The decree-law is subject to validation by the Congreso de los Diputados within 30 days of publication; no validation had been published as of 5 October 2026.
What it means
This depends on a number that has not been published yet. Whether November carries 10% turns on INE’s October release of the September CPI, so suppliers cannot fix their November rate until then.
The electricity relief covers only the stated customer groups, not all electricity supply. Billing systems need two rate paths for November and a second decision for December, and the decree-law’s validation by Congress adds further uncertainty.
Proof
1. Si en el mes de septiembre de 2026 el IPC de la subclase 04.5.1.0 Electricidad supera en más de un 15 por ciento el IPC del mismo mes del año anterior, de acuerdo con la información que publique en octubre el Instituto Nacional de Estadística, durante el mes de noviembre de 2026 se aplicará el tipo del 10 por ciento del Impuesto sobre el Valor Añadido a las entregas, importaciones y adquisiciones intracomunitarias de energía eléctrica efectuadas a favor de: 1. If in September 2026 the CPI of subclass 04.5.1.0 Electricity exceeds by more than 15 percent the CPI of the same month of the previous year, according to the information published in October by the Instituto Nacional de Estadística, during November 2026 the 10 percent rate of Value Added Tax will apply to supplies, imports and intra-Community acquisitions of electrical energy made to:
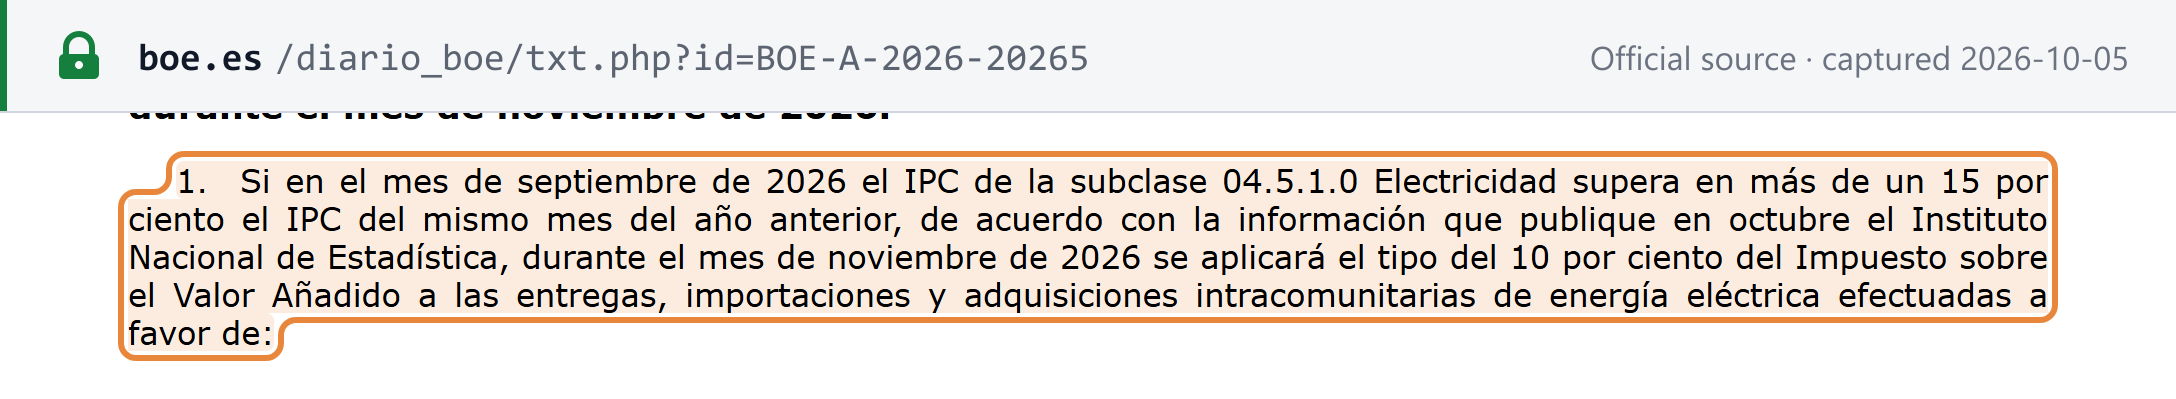 Source snapshot of the official page. Open full size ↗
Sources
- Real Decreto-ley 25/2026, de 29 de septiembre, por el que se adoptan y se prorrogan determinadas medidas en el marco del Plan Integral de Respuesta a la Crisis en Oriente Medio
- Real Decreto-ley 25/2026, de 29 de septiembre (BOE-A-2026-20265)
- Real Decreto-ley 25/2026, de 29 de septiembre
- Council of Ministers tax measures press release, 29 September 2026
What this replaces
- Spain phases down its fuel duty cut and lets the temporary 10% energy VAT rate lapse effective 1 July 2026