Spain's Veri*factu invoicing-software deadlines are 1 January 2027 for corporate income taxpayers and 1 July 2027 for others
This page records one dated change. For the rules in Spain as they stand today, see the Spain guide →
- Jurisdiction
- Spain
- Tax
- VAT
- Change type
- E-invoicing
- Status
- Enacted
- Impact
- Action required
- Announced
- 3 December 2025
- Effective
- 1 January 2027
- Authority
- Boletín Oficial del Estado (BOE)
- Systems
- Invoicing, POS, ERP, Reporting
- Verified
- Fetched from official source · high confidence
Spanish taxpayers using invoicing software: corporate income taxpayers (article 3.1.a) from 1 January 2027 and all other obliged taxpayers from 1 July 2027.
Confirm invoicing/POS software meets the SIF/Veri*factu requirements before 1 January 2027 (corporate-tax filers) or 1 July 2027 (all others).
InvoicingPOSERPReporting
Real Decreto-ley 15/2025 of 2 December 2025 extended the deadline for adapting invoicing software systems (Sistemas Informaticos de Facturacion, the Veri*factu regime under Real Decreto 1007/2023) to 1 January 2027 for taxpayers filing Corporate Income Tax (Article 3.1.a) and to 1 July 2027 for all other obliged taxpayers. The AEAT states the period before those dates is a testing period during which test records need not be sent and other invoicing systems may be used.
What changed in detail
Real Decreto-ley 15/2025 of 2 December 2025 (published in the BOE on 3 December 2025) extended the deadline for adapting invoicing software systems (Sistemas Informáticos de Facturación, the Veri*factu regime under Real Decreto 1007/2023).
Systems must be adapted before 1 January 2027 for taxpayers filing Corporate Income Tax (Article 3.1.a) and 1 July 2027 for all other obliged taxpayers.
The Agencia Tributaria (AEAT) states that the period before those dates is a testing period during which test records need not be sent and other invoicing systems may be used.
What it means
The two dates split by taxpayer type, not by size or sector. The first question is whether the business files Corporate Income Tax, which puts it on the January date, or not, which puts it on the July date.
The AEAT’s testing-period statement means no obligation to send records before the deadline, but software vendors still need a compliant release ready in time for their customers.
Proof
para los obligados del artículo 3.1.a): 1 de enero de 2027, y para el resto de los obligados del artículo 3.1: 1 de julio de 2027.for those obliged under article 3.1.a): 1 January 2027, and for the rest of those obliged under article 3.1: 1 July 2027.
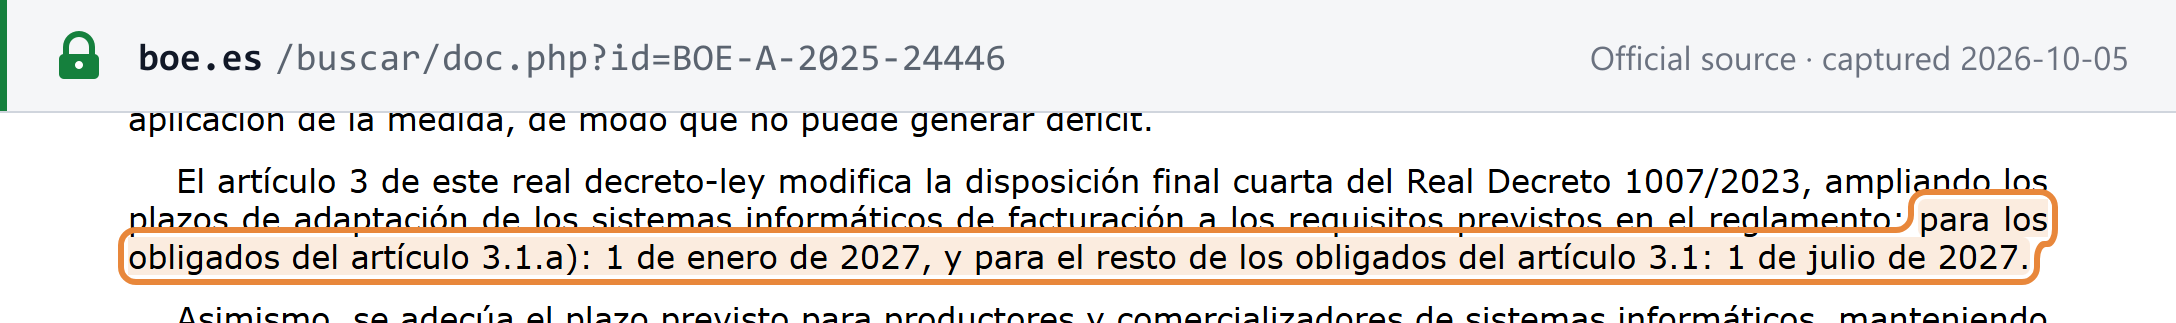 Source snapshot of the official page. Open full size ↗