Switzerland: Parliament extends the 3.8% accommodation VAT rate to 2031, subject to a referendum until 21 January 2027
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Switzerland as they stand today, see the Switzerland guide →
- Jurisdiction
- Switzerland
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 13 October 2026
- Effective
- 1 January 2028
- Authority
- Bundeskanzlei (Swiss Federal Chancellery)
- Systems
- Tax engine, POS, Invoicing
- Verified
- Fetched from official source · high confidence
Hotels and other businesses supplying accommodation services in Switzerland.
No action — monitoring only. Hotel and accommodation operators: keep 3.8% on 2028 pricing assumptions unless a referendum is called by 21 January 2027.
Tax enginePOSInvoicing
On 2 October 2026 the Swiss National Council and Council of States both adopted, in the final vote, an amendment to the Federal VAT Act (MWSTG, Art. 25 para. 4) extending the special 3.8% rate for accommodation services until 31 December 2031. The text was published in the Federal Gazette (BBl 2026 2723) on 13 October 2026 and is subject to an optional referendum, whose deadline expires on 21 January 2027; if no referendum is called it enters into force on 1 January 2028, otherwise the Federal Council sets the date.
What changed in detail
The extension is not yet in force: it is subject to an optional referendum, and the referendum period runs until 21 January 2027. On 2 October 2026 the National Council and the Council of States both adopted, in the final vote, an amendment to the Federal VAT Act (MWSTG, Art. 25 para. 4, second sentence) under which the special rate for accommodation services, 3.8%, would apply until 31 December 2031.
The amendment was published in the Federal Gazette on 13 October 2026 (BBl 2026 2723). If, ten days after the referendum period ends, it is established that no referendum has been called, the amendment enters into force on 1 January 2028. Otherwise the Federal Council sets the date of entry into force.
What it means
The vote removes the risk that the accommodation rate lapses at the end of 2027, but it is not settled until the referendum window closes on 21 January 2027 without a challenge. Hotels and accommodation providers can keep 3.8% in their 2028 pricing assumptions, and should check after 21 January 2027 whether a referendum was called before treating the extension as final.
Proof
Der Sondersatz gilt bis zum 31. Dezember 2031.The special rate applies until 31 December 2031.
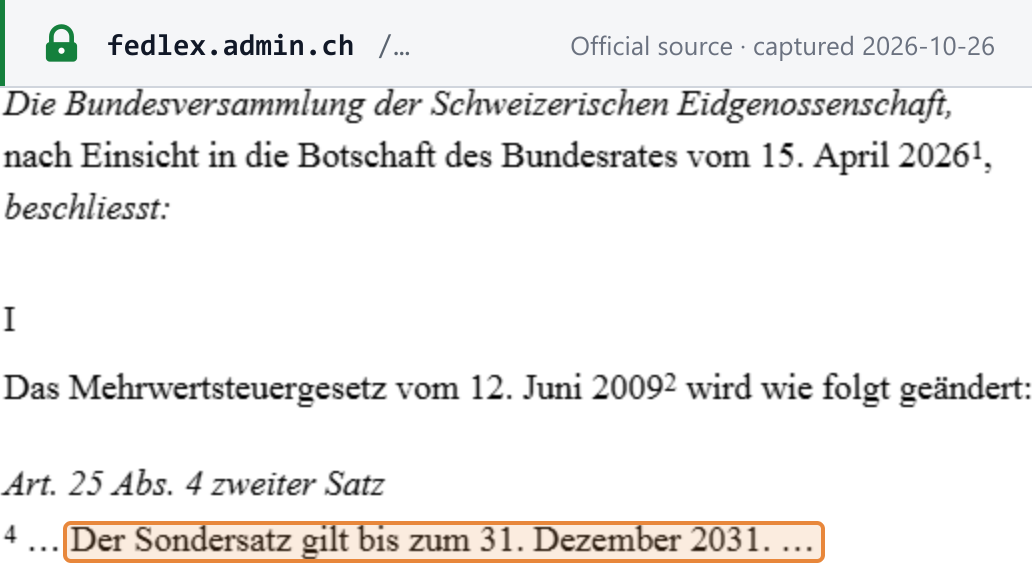 Source snapshot of the official page. Open full size ↗
Dieses Gesetz untersteht dem fakultativen Referendum.This Act is subject to an optional referendum.
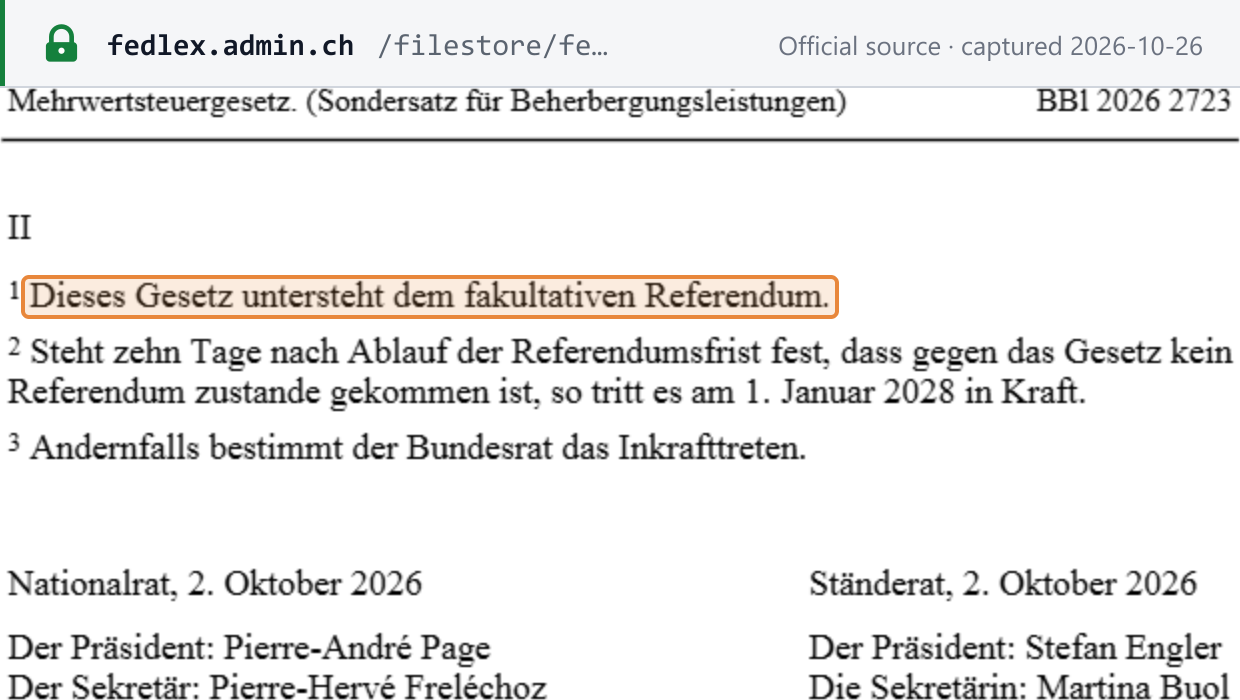 Source snapshot of the official page. Open full size ↗