Proposed, not yet law: Trinidad and Tobago Budget 2027 would apply VAT to digital services from non-resident providers from 1 March 2027
This change is proposed and is not law. The rules below describe what would change if it is adopted.
- Jurisdiction
- Trinidad and Tobago
- Tax
- VAT
- Change type
- Digital services
- Status
- Proposed
- Impact
- Watch
- Announced
- 12 October 2026
- Effective
- 1 March 2027
- Authority
- Ministry of Finance, Trinidad and Tobago
- Systems
- Tax engine, E-commerce, Invoicing
- Verified
- Fetched from official source · high confidence
Non-resident suppliers of digital services to persons in Trinidad and Tobago, including suppliers of taxable services connected with real property in Trinidad and Tobago.
Non-resident digital suppliers: prepare for Trinidad and Tobago VAT registration and collection from 1 March 2027 once legislated.
Tax engineE-commerceInvoicing
The Trinidad and Tobago 2027 Budget Statement (delivered 12 October 2026) proposes to apply VAT to digital services supplied by non-resident providers to persons in Trinidad and Tobago, with simplified electronic registration, collection and remittance for non-resident suppliers (including suppliers of taxable services connected with real property in Trinidad and Tobago), taking effect on 1 March 2027. Not yet legislated.
What changed in detail
This is a proposal in a budget speech, not law, and it has not yet been legislated. The Trinidad and Tobago 2027 Budget Statement, delivered on 12 October 2026, proposes to apply VAT to digital services supplied by non-resident providers to persons in Trinidad and Tobago.
To facilitate compliance and collection, a simplified electronic registration, collection and remittance process would be introduced for non-resident suppliers, including suppliers of taxable services connected with real property situated in Trinidad and Tobago. The proposed effective date is 1 March 2027.
What it means
If legislated, foreign digital providers with Trinidad and Tobago customers would need to register for VAT and remit it. Until a bill is passed, the proposal can still change, including its date and scope. Providers can start by working out how many customers they have in the country and how they would capture the customer’s location.
Proof
Accordingly, the Government proposes to apply VAT to digital services supplied by non-resident providers to persons in Trinidad and Tobago.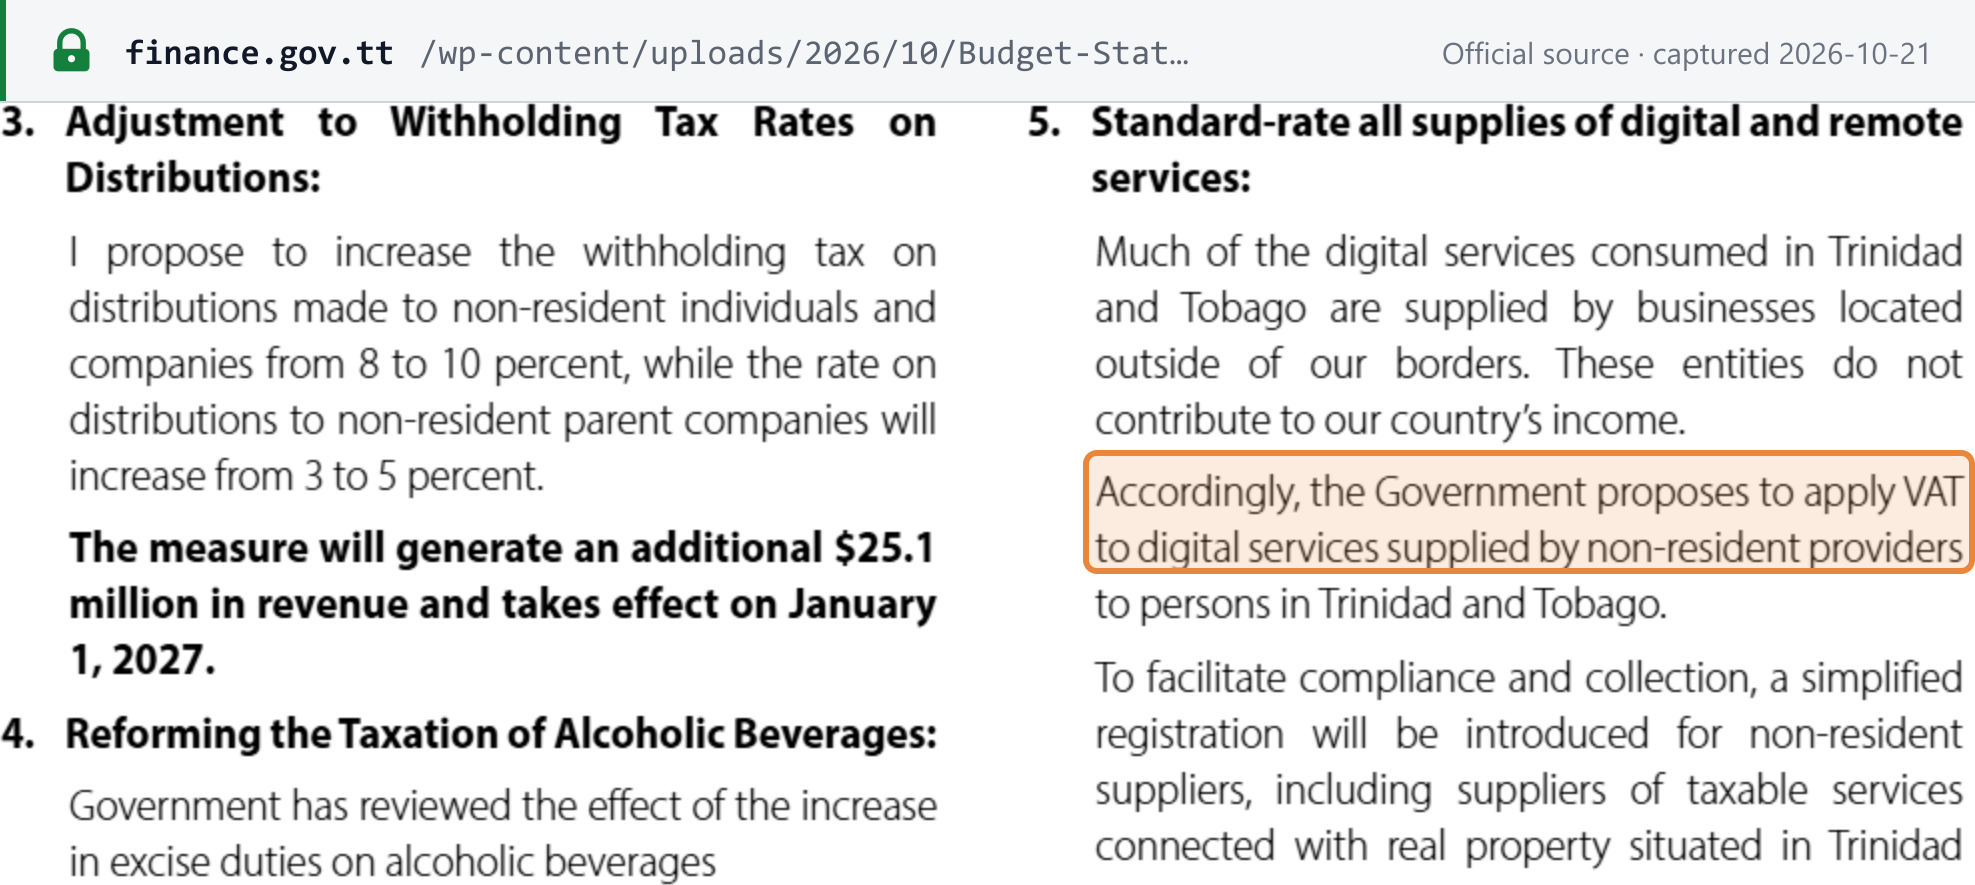 Source snapshot of the official page. Open full size ↗