UAE Ministerial Decision No. 197 of 2026 amends the e-invoicing rules: Tax Group transactions excluded for 24 months and the UAE data-storage rule replaced
This page records one dated change. For the rules in United Arab Emirates as they stand today, see the United Arab Emirates guide →
- Jurisdiction
- United Arab Emirates
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- Plan ahead
- Announced
- 19 October 2026
- Effective
- 1 October 2026
- Authority
- UAE Ministry of Finance
- Systems
- ERP, Invoicing, Reporting
- Verified
- Fetched from official source · high confidence
Businesses in scope of the UAE Electronic Invoicing System, in particular members of VAT Tax Groups and businesses that store e-invoice data or notify system failures.
Exclude UAE Tax Group intra-group flows from e-invoice scope until end-2028 in ERP mapping, and drop UAE-only hosting requirements for e-invoice archives.
ERPInvoicingReporting
UAE Ministerial Decision No. 197 of 2026 amends Ministerial Decision No. 243 of 2025 on the Electronic Invoicing System, in force from 1 October 2026 (announced by the Ministry of Finance on 19 October 2026). Transactions between members of the same Tax Group are Excluded Transactions for 24 months starting 1 January 2027; the requirement to store e-invoice data inside the UAE is replaced by a retention-and-production-on-request duty; the System Failure definition and Article 12 (two-business-day failure notification) are repealed; Article 6(5) is restated with a 14-Business-Day issuance window from the Date of Business Transaction.
What changed in detail
Ministerial Decision No. 197 of 2026 amends Ministerial Decision No. 243 of 2025 on the Electronic Invoicing System. It is in force from 1 October 2026; the Ministry of Finance announced it on 19 October 2026.
- Transactions between members of the same Tax Group are Excluded Transactions for 24 months starting 1 January 2027.
- The requirement to store e-invoice data inside the UAE is replaced by a duty to retain the data and produce it on request.
- The System Failure definition and Article 12 (notification of a failure within two business days) are repealed.
- Article 6(5) is restated with a 14-Business-Day window to issue the invoice from the Date of Business Transaction.
What it means
The Tax Group exclusion is time-limited, so intra-group flows come back into scope after the 24 months unless the Minister extends it. Removing the in-country storage rule eases hosting choices, but retention and production on request still need an accessible archive.
Proof
f) Business Transactions carried out between Persons who are members of the same Tax Group, for a period of twenty-four (24) months starting from 1 January 2027.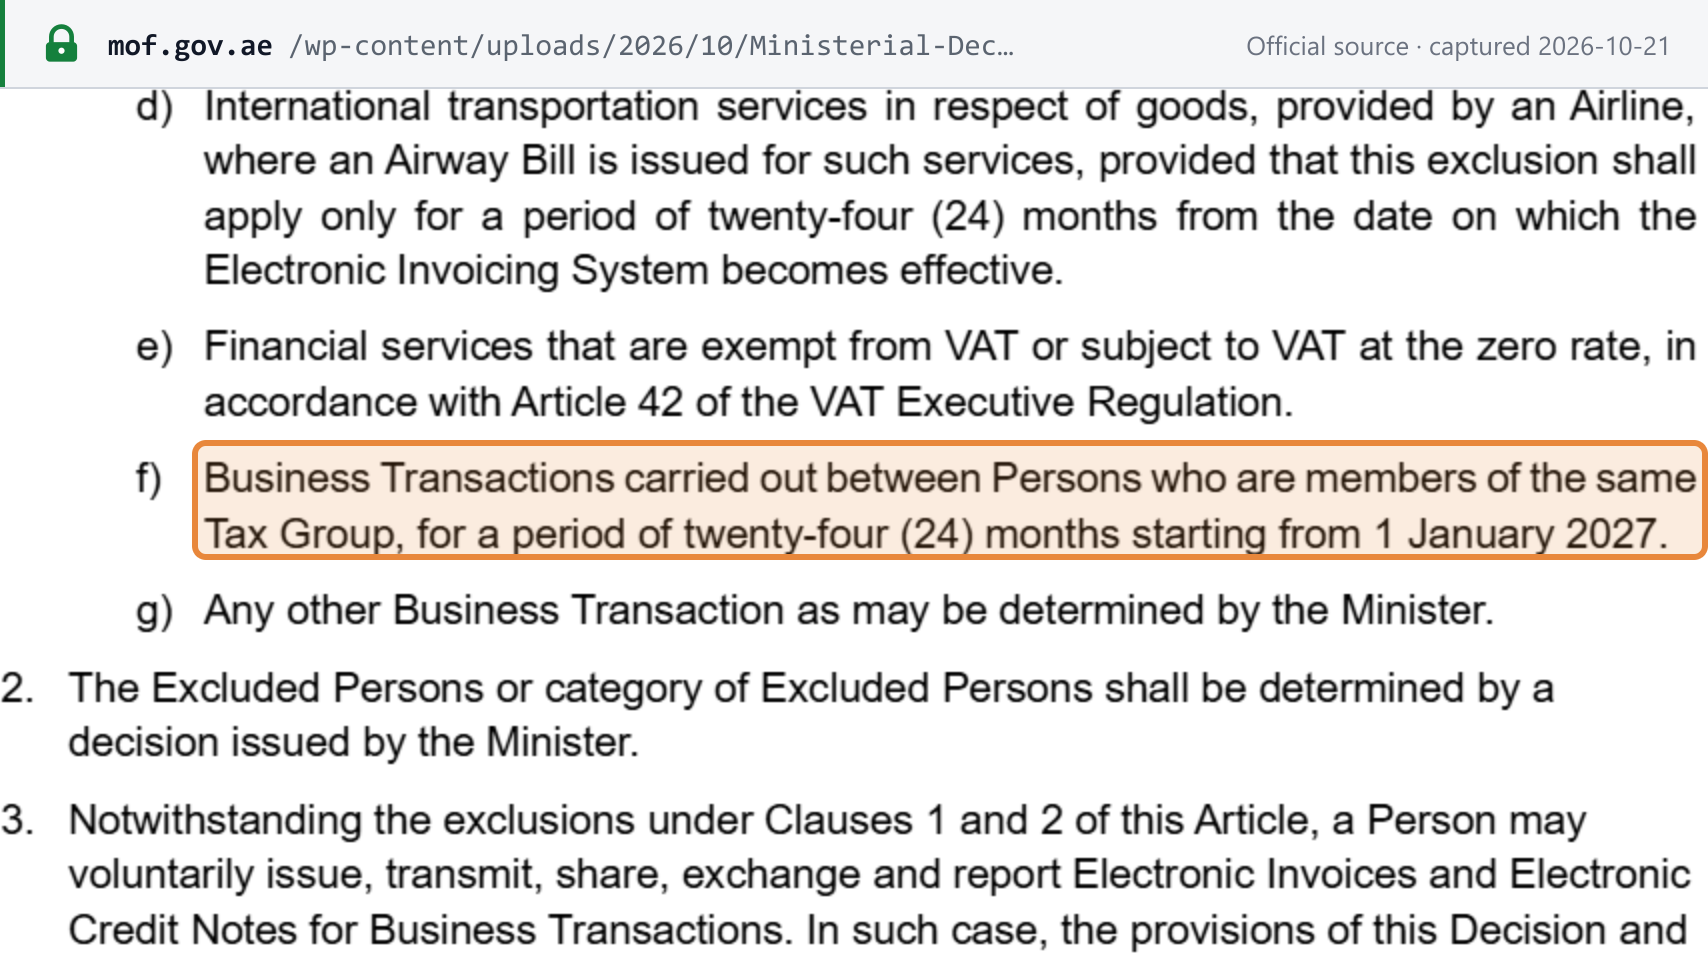 Source snapshot of the official page. Open full size ↗