UAE explains the metal scrap reverse charge under Cabinet Decision No. 153 of 2025
This page records one dated change. For the rules in United Arab Emirates as they stand today, see the United Arab Emirates guide →
- Jurisdiction
- United Arab Emirates
- Tax
- VAT
- Change type
- Update
- Status
- In force
- Impact
- Plan ahead
- Effective
- 14 January 2026
- Authority
- Federal Tax Authority (UAE)
- Systems
- ERP, Invoicing, Tax engine, Reporting
- Verified
- Fetched from official source · medium confidence
VAT-registered suppliers and recipients of metal scrap for resale or processing in the UAE.
Confirm metal-scrap trading customers/suppliers are flagged for reverse-charge treatment and that the pre-supply declarations described in VATP047 are held.
ERPInvoicingTax engineReporting
FTA VAT Public Clarification VATP047 (listed as new on the FTA guides page, file dated October 2026) explains the reverse charge on supplies of Metal Scrap between VAT registrants under Cabinet Decision No. 153 of 2025. The recipient accounts for the VAT on supplies of Metal Scrap for resale or processing, subject to the Decision's conditions; supplier and recipient must meet additional compliance requirements before the date of supply. Where the conditions are not met the supplier accounts for VAT and the recipient cannot recover the related input tax under article 54(1)(a) and (b) of the VAT Law. The Decision applies to Metal Scrap supplied on or after 14 January 2026.
What changed in detail
The Federal Tax Authority published VAT Public Clarification VATP047, listed as new on the FTA guides page in October 2026, on the reverse charge for supplies of Metal Scrap between VAT registrants under Cabinet Decision No. 153 of 2025. The Decision applies to Metal Scrap supplied on or after 14 January 2026.
Under the reverse charge the recipient, not the supplier, accounts for the VAT on supplies of Metal Scrap made for resale or processing, subject to the Decision’s conditions. Both the supplier and the recipient must also meet additional compliance requirements before the date of supply.
Where the conditions are not met, the supplier must account for the VAT and the recipient cannot recover the related input tax under article 54(1)(a) and (b) of the VAT Law.
What it means
The risk sits mainly with the recipient. If a condition is missed, the supplier charges VAT in the normal way and the buyer loses the input tax claim, so the reverse charge is not something to apply by default. Both parties should confirm the pre-supply compliance requirements are met before the date of supply, and agree in advance who accounts for the tax. Supplies made before 14 January 2026 are outside the Decision.
Proof
Metal Scrap supplied on or after 14 January 2026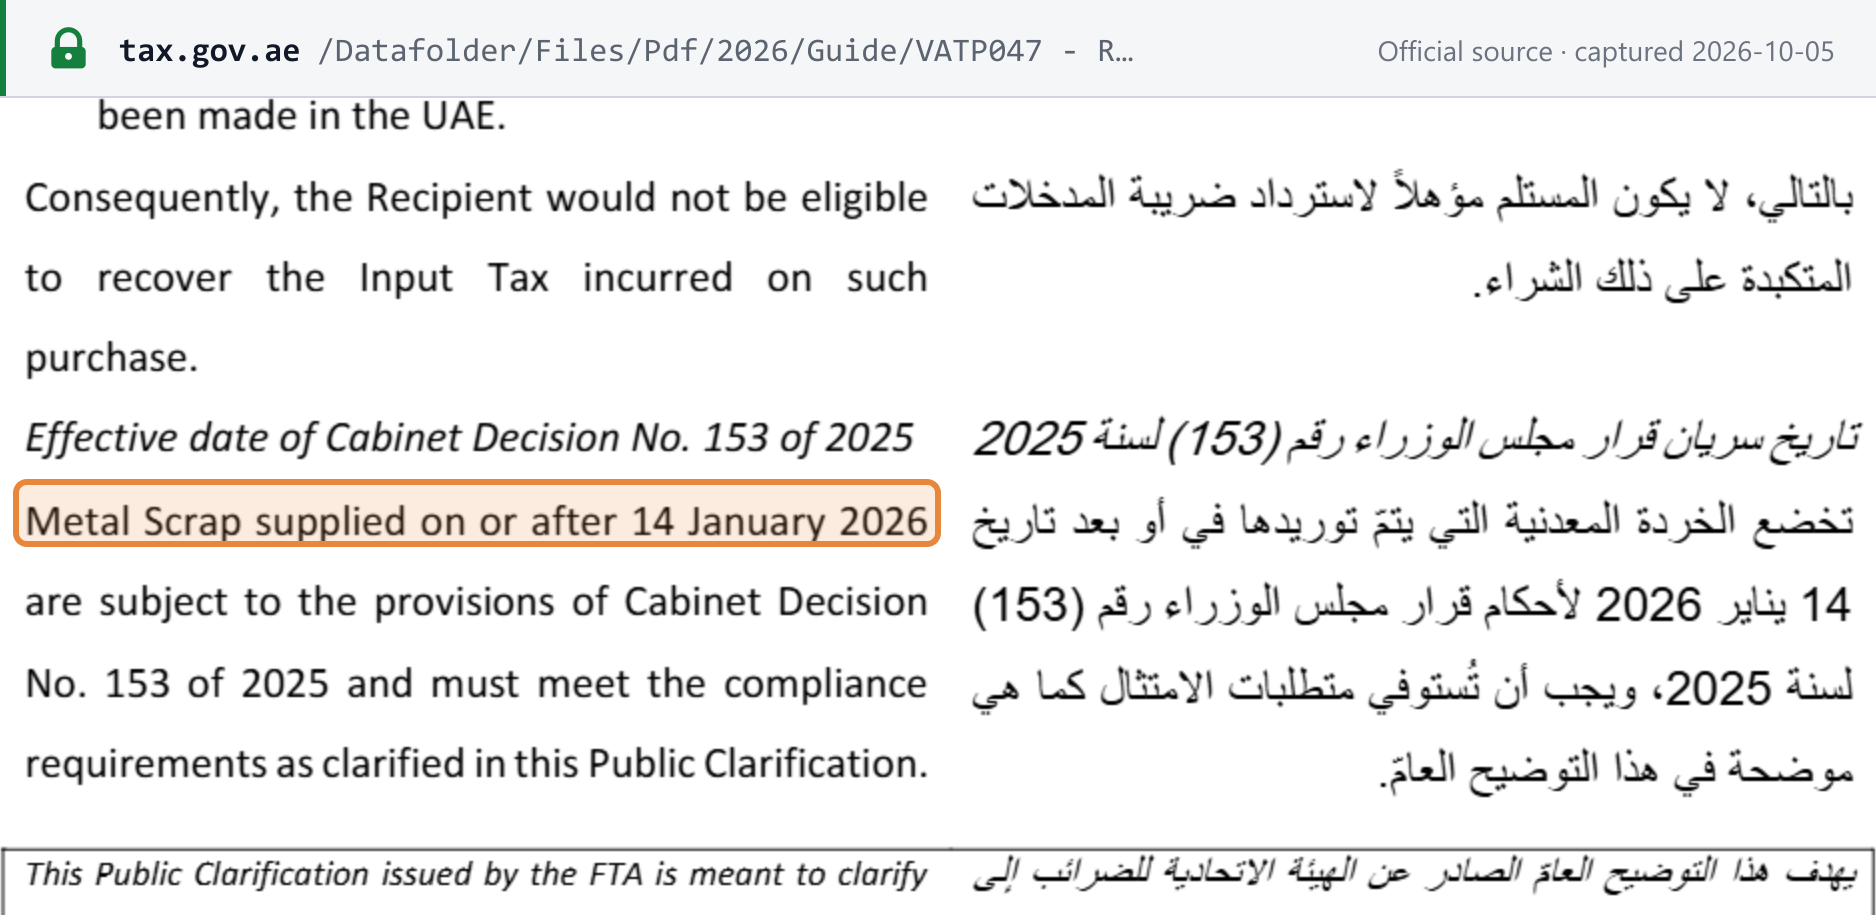 Source snapshot of the official page. Open full size ↗