UAE lets businesses recover input VAT on listed employee benefits from 1 October 2026
This page records one dated change. For the rules in United Arab Emirates as they stand today, see the United Arab Emirates guide →
- Jurisdiction
- United Arab Emirates
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Announced
- 9 September 2026
- Effective
- 1 October 2026
- Authority
- Federal Tax Authority (UAE)
- Systems
- ERP, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
UAE VAT-registered employers that provide goods or services to employees free of charge under a contract or documented policy.
Review employee-benefit expense categories (transport, meals, accommodation, mobile/internet, parking) against the Article 2 conditions before the 1 October 2026 input-tax claims.
ERPTax engineReporting
Federal Tax Authority Decision No. 17 of 2026, issued 9 September 2026 and effective 1 October 2026, sets the cases and conditions for recovering input tax on goods or services bought for employees at no charge where a contractual obligation or documented policy requires them (Cabinet Decision No. 52 of 2017, article 53(1)(c)(2)). Article 2 covers employee transport, food and beverages, accommodation (including temporary accommodation for new joiners), mobile and internet services and parking, each subject to listed conditions.
What changed in detail
Federal Tax Authority Decision No. 17 of 2026 was issued on 9 September 2026 and applies from 1 October 2026. It sets the cases and conditions in which a business may recover input tax on goods or services it buys for its employees at no charge, where a contractual obligation or a documented policy requires it to provide them. The legal basis is article 53(1)(c)(2) of Cabinet Decision No. 52 of 2017.
Article 2 lists the covered categories: employee transport, food and beverages, accommodation (including temporary accommodation for new joiners), mobile and internet services, and parking. Each category carries its own listed conditions, which the Decision sets out.
What it means
The Decision does not give a blanket right to recover VAT on staff costs. Recovery is limited to the five listed categories and only where the employer is obliged, by contract or a documented policy, to provide the benefit. Employers should check that their employment contracts or written policies actually create that obligation, and that each category’s listed conditions are met, before claiming input tax on periods from 1 October 2026. Benefits outside the list stay governed by the general rules.
Proof
Federal Tax Authority Decision No. 17 of 2026 – Issued 9 Sep 2026 (Effective from 1 Oct 2026)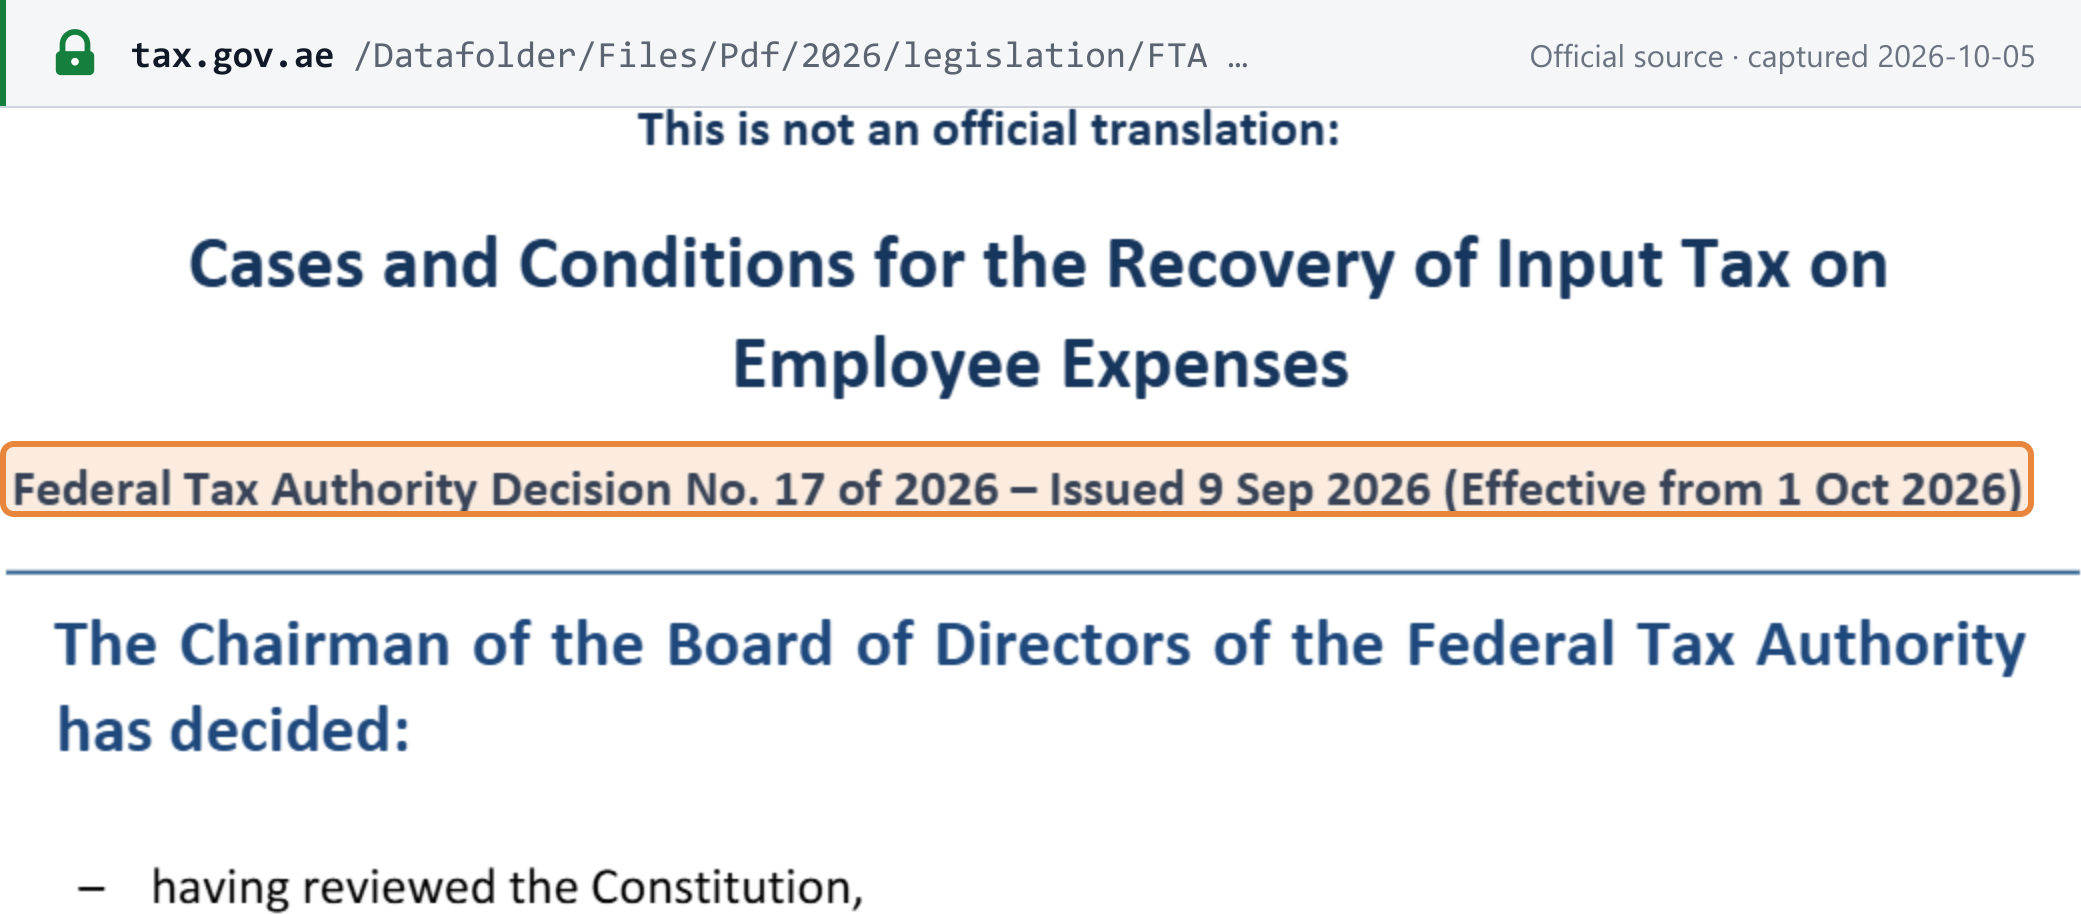 Source snapshot of the official page. Open full size ↗