Great Britain zero-rates domestic electricity from 1 October 2026 to 31 March 2027
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in United Kingdom as they stand today, see the United Kingdom guide →
- Jurisdiction
- United Kingdom
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Action required
- Announced
- 8 September 2026
- Effective
- 1 October 2026
- Authority
- HM Revenue & Customs
- Systems
- Invoicing, ERP, Tax engine
- Verified
- Fetched from official source · high confidence
Suppliers of qualifying domestic electricity in England, Wales and Scotland, and the households receiving those supplies. Northern Ireland supplies and every other domestic fuel are unaffected.
Prepare billing/tax-engine configuration for a 0% VAT treatment on Great Britain domestic electricity supplies from 1 October 2026 to 31 March 2027 (Northern Ireland and other domestic fuels remain at 5%), but do not finalise go-live configuration until the Treasury Order is confirmed made - monitor legislation.gov.uk/uksi/2026 and gov.uk for the instrument.
InvoicingERPTax engine
HMRC published Revenue and Customs Brief 10 (2026) and an accompanying Tax Information and Impact Note (TIIN) on 8 September 2026, confirming a temporary zero rate of VAT (down from the current 5% reduced rate) for qualifying domestic electricity supplies in Great Britain (England, Wales, Scotland) for the period 1 October 2026 to 31 March 2027. Northern Ireland stays at the 5% reduced rate throughout. The TIIN states the change will be made via a Treasury Order (under VATA 1994 ss.29A(3)/96(9)) amending Schedule 7A and inserting a new Group 24 into Schedule 8 of the VAT Act 1994. As of this capture (2026-09-12), no such statutory instrument has been found made, laid, or published anywhere official, and the TIIN itself says 'New guidance will be published alongside the legislation' (future tense, as of 8 September).
What changed in detail
On 8 September 2026 HMRC published Revenue and Customs Brief 10 (2026) and an accompanying Tax Information and Impact Note (TIIN). The measure was announced on 21 July 2026.
The TIIN states that the measure introduces a temporary zero rate of VAT for qualifying supplies of electricity in Great Britain for the period 1 October 2026 to 31 March 2027, and that the rate remains 5% on all other types of domestic fuel UK-wide. In Northern Ireland the rate on qualifying electricity is unchanged, and supplies there continue to be charged at the reduced rate where they qualify for relief.
The mechanism is a Treasury Order. HMRC cites sections 29A(3) and 96(9) of the Value Added Tax Act 1994 as the power to amend Schedule 7A, and sections 30(4) and 96(9) as the power to amend Schedule 8. The Order restricts the Schedule 7A Group 1 reduced rate for electricity to supplies in Northern Ireland, and inserts a new Group 24 into Schedule 8, “Domestic Electricity: England and Wales and Scotland”, carrying the same qualifying descriptions as the existing relief.
That Order has been made. The Value Added Tax (Supplies of Domestic Electricity) Order 2026, SI 2026/987, was made on 7 September 2026 and laid before the House of Commons on 8 September 2026, coming into force on 1 October 2026.
:::note Correction, 21 September 2026 This record originally said the Treasury Order was “still to be made”, because the frozen change it overlays recorded that no instrument had been found at its capture date of 12 September 2026. The Order had in fact been made on 7 September and laid on 8 September — both before that capture date. The measure is law; only our search for it came back empty. The frozen entry still carries status: proposed and is append-only, so the correction is recorded here and is owed upstream as a superseding entry.
This is the same measure announced on 21 July 2026 and recorded at that earlier stage as gb-domestic-electricity-zero-rate-2026; neither entry carries a supersedes edge today. :::
What it means
A rate change with a start date three weeks out and no instrument yet is an awkward thing to configure for. HMRC does not usually publish a Brief and a TIIN for a measure that then fails to appear, so building the 0% treatment now is sensible — but going live on it before the Order is made means charging 0% with no legal basis, and unwinding that is a credit-note exercise across every domestic bill in the window.
Two traps sit in the detail. The split is geographic, not fuel-based: Northern Ireland stays at 5%, so a supplier with customers on both sides of the Irish Sea needs two treatments rather than one. And gas, heat and every other domestic fuel stay at 5% UK-wide — this is electricity only, for six months.
Proof
This measure introduces a temporary zero rate of VAT for qualifying supplies of electricity in Great Britain, for the period 1 October 2026 to 31 March 2027. The rate will remain 5% on all other types of domestic fuel UK-wide.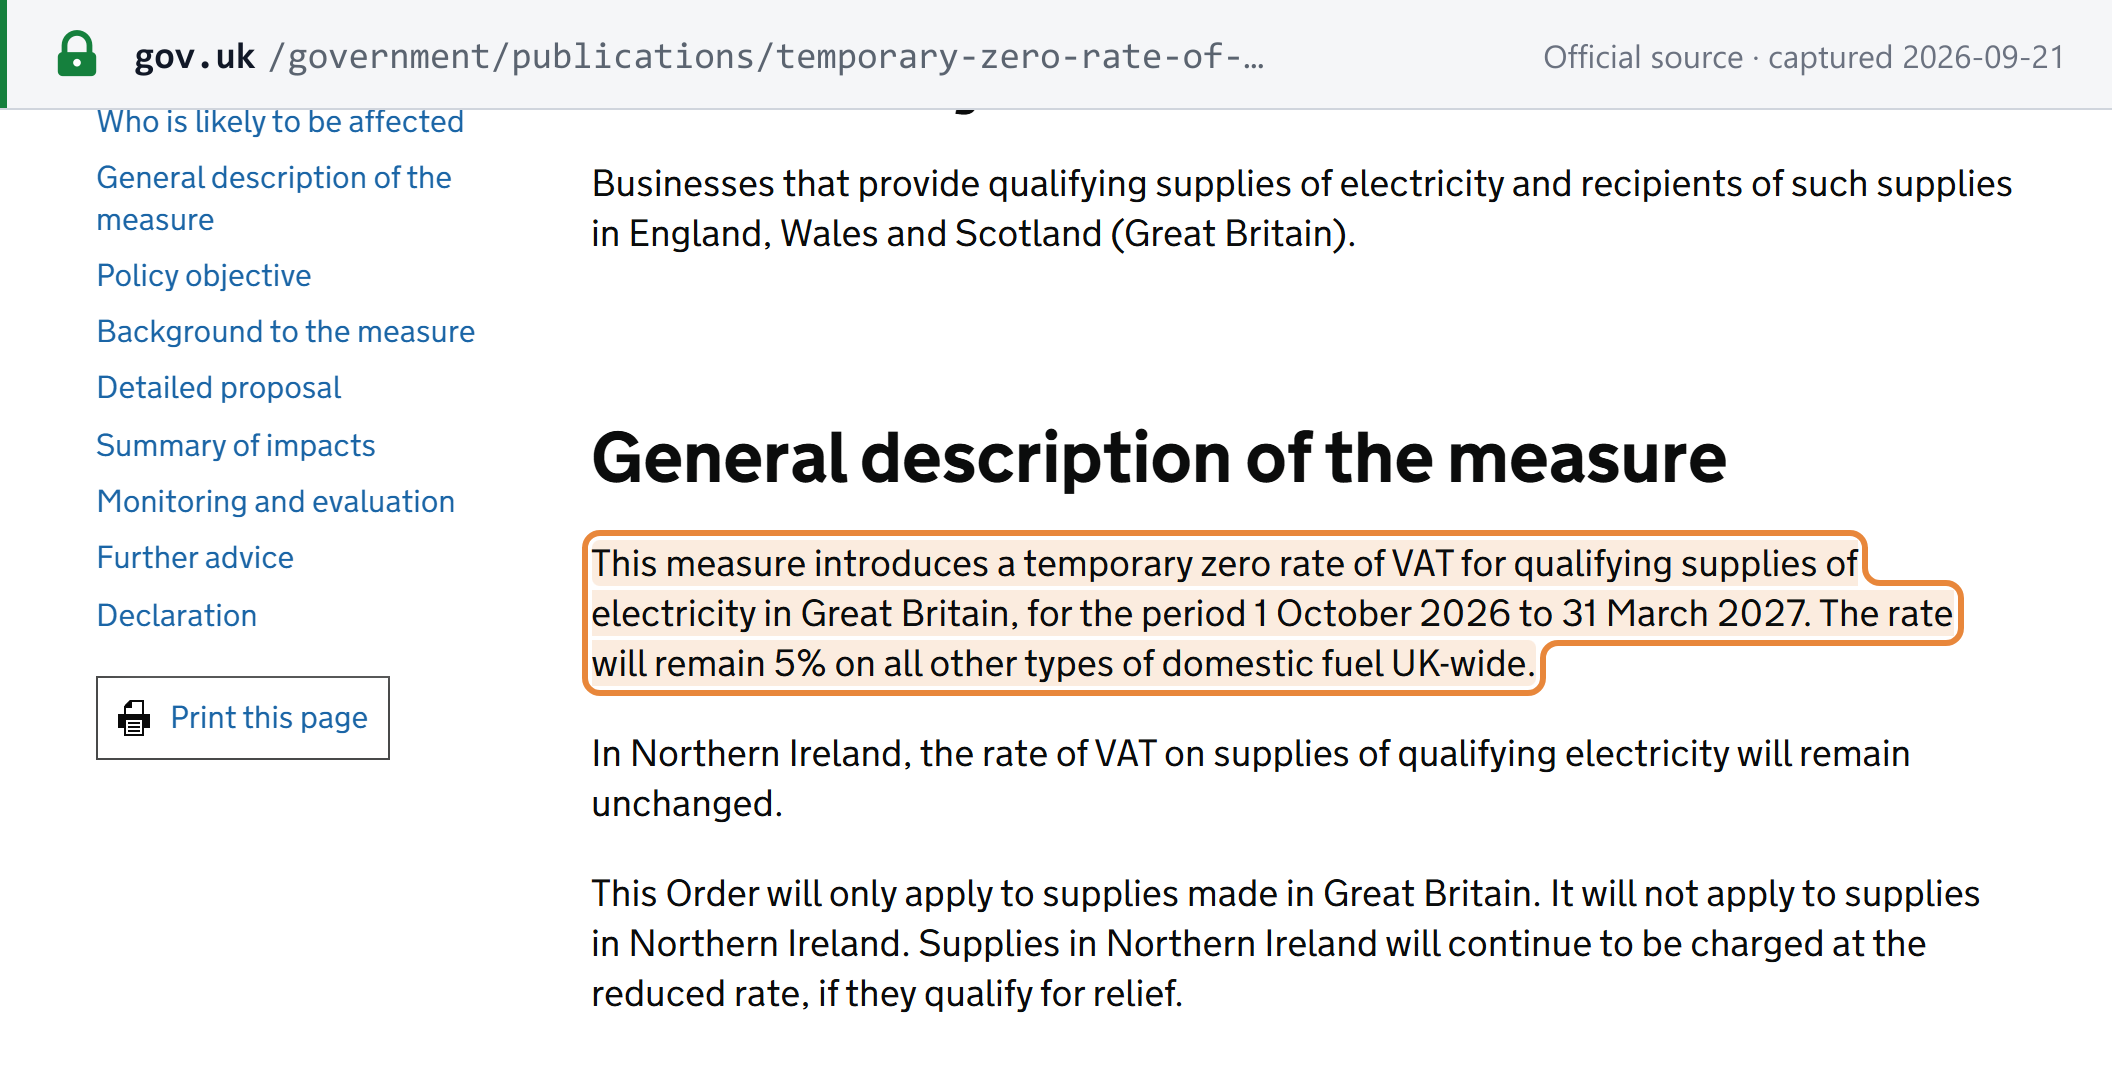 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Tax Information and Impact Note — Temporary zero rate of VAT in Great Britain for domestic electricity, published 8 September 2026 · www.gov.uk