S.I. 2026/987 zero-rates domestic electricity in Great Britain from 1 October 2026
This page records one dated change. For the rules in United Kingdom as they stand today, see the United Kingdom guide →
- Jurisdiction
- United Kingdom
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Action required
- Announced
- 7 September 2026
- Effective
- 1 October 2026
- Authority
- The National Archives (legislation.gov.uk) / HM Treasury
- Systems
- Tax engine, Invoicing, ERP
- Verified
- Fetched from official source · high confidence
Electricity suppliers making qualifying supplies of domestic electricity in England, Wales and Scotland from 1 October 2026 to 31 March 2027. Northern Ireland keeps the existing 5% reduced rate.
Electricity suppliers in Great Britain: apply 0% VAT to qualifying supplies of electricity for supplies made from 1 October 2026 to 31 March 2027; keep the 5% reduced rate for Northern Ireland supplies.
Tax engineInvoicingERP
The Value Added Tax (Supplies of Domestic Electricity) Order 2026, S.I. 2026 No. 987, was made by the Treasury on 7 September 2026 and laid before the House of Commons on 8 September 2026, and comes into force on 1 October 2026. It modifies Schedule 8 to the Value Added Tax Act 1994 to insert a new Group 24 (Supplies of Domestic Electricity: England and Wales and Scotland) zero-rating supplies in England, Wales and Scotland of electricity for qualifying use, and makes consequential modifications to Group 1 of Schedule 7A so that the 5% reduced rate is retained for supplies of electricity in Northern Ireland. The modifications have effect for supplies made in the period beginning 1 October 2026 and ending 31 March 2027. This supersedes the W38 entry, which recorded status 'proposed' and stated that no instrument had been found made or laid; the Order had in fact been made five days and laid four days before that entry's 12 September capture.
What changed in detail
The instrument exists, and it was made before the entry saying it did not. The Value Added Tax (Supplies of Domestic Electricity) Order 2026, S.I. 2026 No. 987, was made by the Treasury on 7 September 2026 and laid before the House of Commons on 8 September 2026. It comes into force on 1 October 2026.
The Order inserts a new Group 24 into Schedule 8 of the Value Added Tax Act 1994, zero-rating supplies in England, Wales and Scotland of electricity for qualifying use, and makes consequential changes to Group 1 of Schedule 7A so Northern Ireland keeps the 5% reduced rate. The modifications apply to supplies made from 1 October 2026 to 31 March 2027.
This corrects the earlier entry, which recorded status “proposed” and stated that no instrument had been found made or laid. In fact the Order had already been made five days, and laid four days, before that entry’s 12 September capture — it was a gap in what had been checked, not a gap in what HM Treasury had done.
What it means
Nothing about the rate itself changes: 0% for qualifying Great Britain electricity supplies from 1 October to 31 March, 5% unchanged in Northern Ireland. What changes is the citation — point to S.I. 2026/987 as the enacted instrument, not to the earlier “proposed” status. If a decision was being held pending confirmation that the SI existed, that confirmation is now available directly from legislation.gov.uk.
Proof
This Order may be cited as the Value Added Tax (Supplies of Domestic Electricity) Order 2026 and comes into force on 1st October 2026.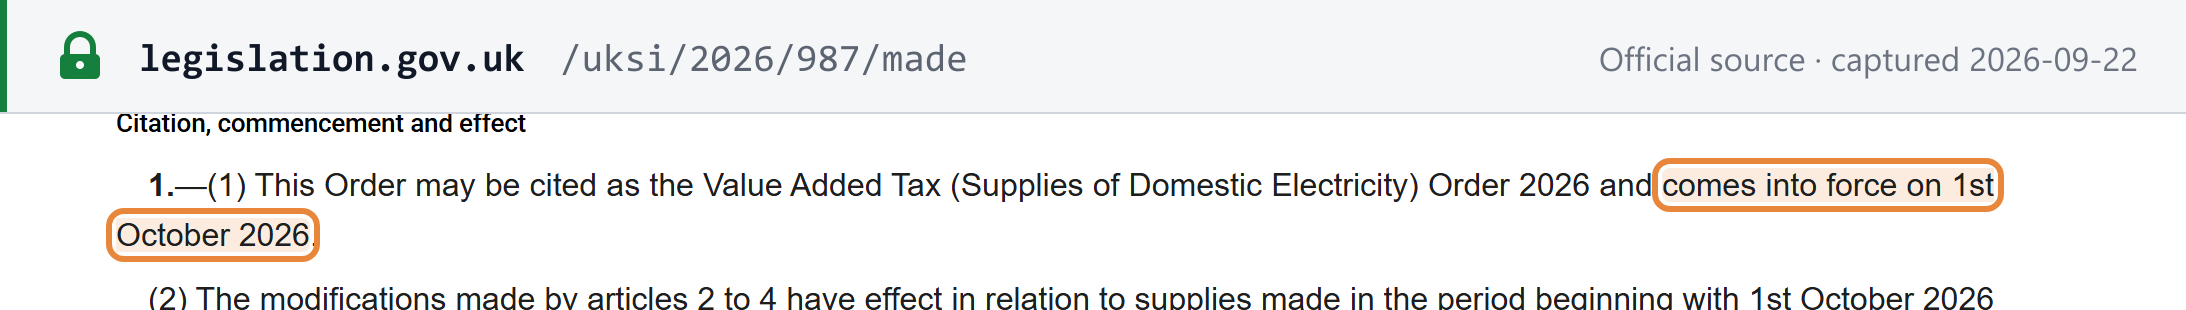 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Great Britain zero-rates domestic electricity from 1 October 2026 to 31 March 2027 effective 1 October 2026